

Why Finding Affordable Car Insurance is More Important Than Ever
Finding affordable car insurance isn’t just nice a ait’s essential when the average New York driver now pays $1,200 a a$2,000 each year for coverage. A few smart moves can slice hundreds of dollars off that bill without cutting protection.
Top ways to lower your premium:
- Compare quotes from several companies a asaves drivers about $882 a year
- Bundle policies to knock 5 a a15% off each policy
- Keep a clean driving record
- Choose a higher deductible to trim 15%+ from collision & comprehensive
- Ask for discounts such as good student, multi acar and safety afeature credits
Premiums rise because insurers look at your driving history, vehicle, location, and coverage choices. The upside? You control many of those factors. With guidance from an independent agency like Mitchell aJoseph Insurance, you can balance strong protection with a price that won’t strain your wallet.
What’s Behind the Price Tag? How Your Premium is Calculated
Ever wonder why your neighbor pays less? Insurers build your rate from a handful of data points. Understand the recipe and you can start lowering the cost.
Key ingredients you CAN influence
- Driving record aThe biggest factor. Tickets or accidents typically raise rates for 3 a5 years.
- Vehicle make & model aCars that are cheap to repair, rarely stolen, and highly rated for safety cost less to insure.
- Location aUrban ZIP codes bring more traffic, theft, and higher premiums than rural areas.
- Coverage limits & deductible aHigher limits add a few dollars a month; a higher deductible can cut 15% or more.
- Annual mileage aDrive under 10,000 miles? Low amileage or usage abased programs can shave 5 a20%.
- Age & experience aRates fall sharply after age 25 and keep easing with a clean record.
Additional factors that surprise many drivers
- Credit score (in NY it matters a abetter credit usually = lower risk = lower rate)
- Claims history (even glass or deer claims matter)
- Marital status (married drivers file fewer claims)
- Vehicle safety & anti atheft tech (five astar ratings and alarms earn discounts)
For a deeper dive, see Factors That Determine Your Auto Insurance Premium.
Building Your Policy: Understanding Mandatory vs. Optional Coverage
New York’s required limits are the legal floor abut they may not cover today’s medical or repair costs. Think of state minimums as bread and water nyou’ll survive, but a bigger accident could empty your savings and put your assets at risk.
Mandatory coverage in New York
- Personal Injury Protection (PIP) – As a no-fault state, New York requires a minimum of $50,000 in PIP coverage. This pays for medical expenses and lost wages for you and your passengers after an accident, regardless of who was at fault.
- Bodily Injury Liability – At least $25,000 per person and $50,000 per accident for injuries to others in an accident you cause.
- Property Damage Liability – A $10,000 minimum to cover damage to another person’s property. We strongly suggest $50,000 or more, as $10,000 barely covers a minor repair on many new vehicles.
- Uninsured/Underinsured Motorist (UM/UIM) – This must match your liability limits and protects you if the at-fault driver has no insurance or not enough to cover your injuries.
Optional coverage worth considering
- Collision – Repairs your car after a crash with another object or vehicle. Raising the deductible is a great way to keep this coverage affordable, and it’s typically required if you have a car loan.
- Comprehensive – Covers non-collision events like theft, fire, hail, vandalism, falling objects, and hitting a deer. Like collision, this is essential for protecting the value of your vehicle.
- Medical Payments (MedPay) – An inexpensive add-on that provides extra coverage for medical bills, filling gaps left by your health insurance or PIP.
- Rental Reimbursement – For just $20 a$30 per year, this ensures you have a rental car to use while yours is in the shop after a covered claim.
- Roadside Assistance – Often cheaper and more convenient than standalone auto club plans, this covers towing, lockouts, and jump-starts.
- Gap Insurance – If your new car is totaled, this pays the difference between the car’s actual cash value and the amount you still owe on your loan or lease.
Even doubling your liability limits often costs just $8 a$15 a month. See Automobile Financial Responsibility by State for a state aby astate view.
Your Ultimate Guide to Finding Affordable Car Insurance
Smart savings rarely mean cutting coverage. They mean shopping smarter and structuring your policy wisely.
- Compare quotes—Always compare apples to apples with identical limits and deductibles. Independent agents like us simplify this by shopping 24 carriers at once on your behalf.
- Raise deductibles—Moving your comprehensive and collision deductible from $500 to $1,000 is one of the fastest ways to lower your premium, often by 15% or more. Just be sure you can comfortably pay that amount out-of-pocket.
- Bundle policies—Combine your auto insurance with a home or renters policy from the same carrier. This is one of the biggest discounts available, often saving up to 25%.
- Telematics—If you’re a safe driver, prove it. Usage-based programs that track your driving habits via a smartphone app can earn you discounts of 5 a20% for being a low-risk driver.
- Defensive driving courses—In New York, completing a DMV-approved Point and Insurance Reduction Program (PIRP) course guarantees a 10% discount on your liability, collision, and no-fault premiums for three full years. It’s a guaranteed return on a small investment of time.
- Pick the right vehicle—Before you buy, check the insurance costs. A sensible sedan or SUV like a CR aV costs far less to insure than a high-performance Mustang or a heavy-duty truck due to repair costs and safety ratings.
For local pointers, visit Cheap Auto Insurance Rochester NY.
Discounts many people miss
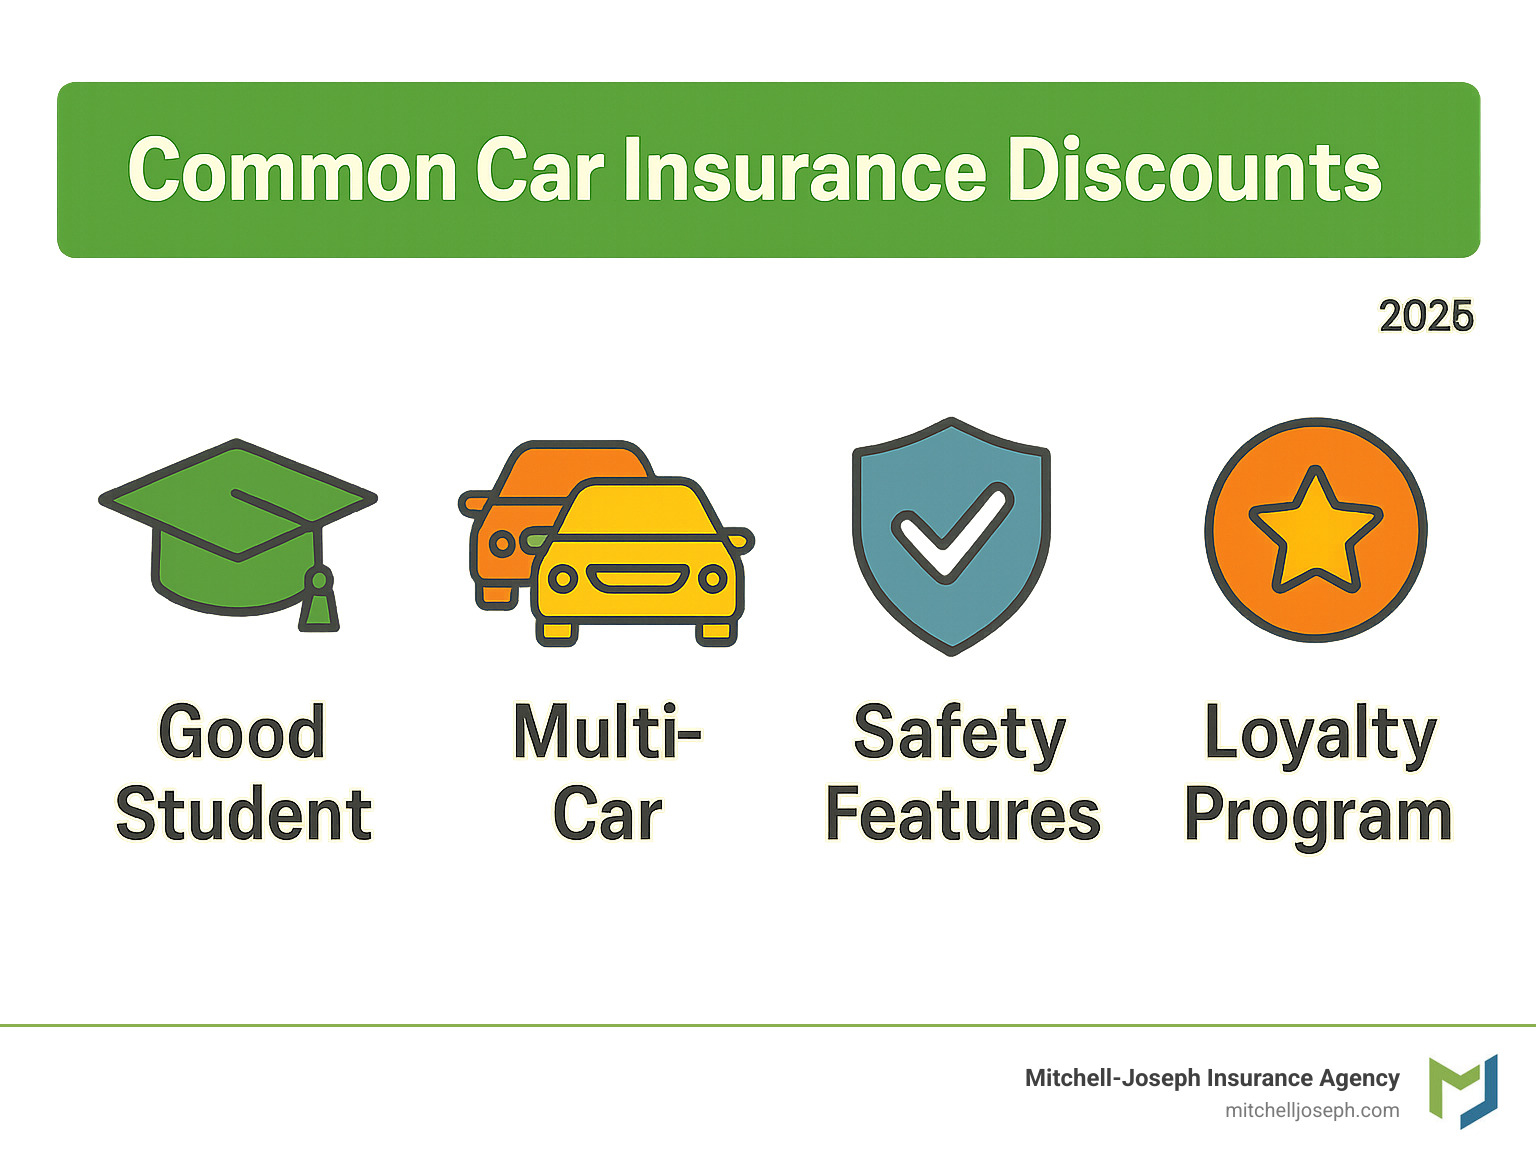
- Good student – 10 a15% for a high school or college student with a “B” average or better.
- Multi acar – Insuring two or more vehicles on the same policy can open up savings of 10 a25%.
- Paid-in-Full – Many insurers offer a small but meaningful discount if you pay your entire six-month or annual premium upfront rather than in monthly installments.
- Paperless Billing & Auto-Pay – Opting for electronic documents and automatic payments can often shave a few more dollars off your bill and reduce the risk of a late payment.
- Loyalty – Sticking with one carrier can earn you discounts over time, but you should still compare rates annually to ensure that loyalty is being rewarded with a competitive price.
- Low mileage – If you work from home or have a short commute, pay aper amile programs can cut costs up to 40%.
- Safety features – Advanced driver-assistance systems (ADAS) like automatic emergency braking and blind-spot monitoring can earn you a 5 a15% credit.
- Group affiliations – Don’t forget to check for discounts through your employer, alumni association, or professional groups.
Special Insurance Considerations for Every Driver
Different drivers need different strategies.
New & teen drivers
- Stay on a parent’s policy – almost always cheaper
- Good student & driver-ed discounts – together can trim 20%+
- Choose a modest, safe car – insurance on a used Corolla beats a Camaro every time
Senior drivers
- Mature adriver courses often earn an extra 5%.
- Review mileage—retirement usually means fewer annual miles and lower rates.
High-risk drivers
- A clean record for three years is the fastest path back to standard rates.
- Some carriers offer “second-chance” plans—an independent agent can spot them.
Specialty vehicles
- Electric vehicles – battery repair costs can raise premiums, but many carriers now offer EV credits.
- Classic cars – look for agreed-value policies so you’re paid the full collectible value after a total loss.
- High-performance cars – higher deductibles + garaging alarms keep premiums in check.
Frequently Asked Questions about Car Insurance
Is car insurance mandatory in New York?
Yes, absolutely. New York State law requires all registered vehicles to have liability insurance, personal injury protection (PIP), and uninsured motorist coverage. The minimums are $25,000/$50,000 for bodily injury, $10,000 for property damage, and $50,000 for PIP. Penalties for driving uninsured are severe, including fines up to $1,500, vehicle impoundment, and license suspension.
How often should I shop for quotes?
It’s wise to compare rates at least once a year upon renewal. You should also shop for new quotes whenever you have a major life change, such as moving, buying a new car, getting married, adding a teen driver to your policy, or seeing a significant improvement in your credit score. Insurers update their pricing models constantly, so the best company for you last year may not be the best one today.
Will one at-fault accident raise my rate forever?
No. While an at-fault accident will likely cause your premium to increase, this surcharge is not permanent. It typically stays on your policy for 3 to 5 years, depending on the insurer and the severity of the accident. Maintaining a clean driving record after the incident is the best way to see your rates come back down. Some policies also offer “accident forgiveness” as an optional add-on to prevent a rate hike after your first at-fault crash.
What happens if my friend borrows my car and has an accident?
In almost all cases, car insurance follows the vehicle, not the driver. This means if you give someone permission to drive your car, your own insurance policy would be the primary source of coverage for damages. This is a key reason why having adequate liability limits is so important ayou are protecting your financial well-being even when you’re not the one behind the wheel.
See more answers at our Auto Insurance FAQs.
Conclusion: Your Road to Savings Starts Here
Your journey to finding affordable car insurance doesn’t have to be complicated or overwhelming. The key is taking a proactive approach and making informed decisions based on what you’ve learned about how insurance works, what coverage you actually need, and which discounts you qualify for.
Think of it this way – you wouldn’t buy the first car you saw on the lot without comparing prices and features. The same principle applies to insurance. Comparing options from multiple insurers can save you hundreds of dollars annually, and the process is much easier than most people think.
The most important step is getting quotes from different companies because rates can vary dramatically between insurers for identical coverage. What makes one company expensive for you might make another company your best option. That’s where working with an independent agent makes all the difference.
At Mitchell-Joseph Insurance Agency, we’ve been helping our neighbors throughout the Finger Lakes region steer these choices for over two decades. Our independent status means we’re not tied to just one insurance company – we can compare quotes from 24 different carriers to find the best fit for your specific situation and budget.
Whether you’re dealing with a teen driver in your household, looking to insure a classic car, or simply want to make sure you’re not overpaying for basic coverage, we understand the unique challenges drivers face in communities like Rochester, Canandaigua, Victor, and throughout our region.
Long-term savings come from making smart choices today. Maintaining a clean driving record, taking advantage of available discounts, and regularly reviewing your policy ensures you’re always getting the best value. Even small changes – like adjusting your deductible or bundling policies – can add up to significant savings over time.
Don’t let another renewal period slip by without exploring your options. An independent agent at Mitchell-Joseph Insurance Agency can help you steer these choices and compare quotes from multiple carriers to find the best fit for your budget and needs.
Your road to savings really does start here. Get your personalized quote today and find how much you could save on your car insurance while keeping the protection that matters most to you and your family.

