

Why Understanding Water Backup Coverage is Critical for Homeowners
What does water sewer backup insurance cover is a question every homeowner should be able to answer. Water damage is already the second-most common homeowners claim, and a standard policy excludes backups entirely.
Quick Answer: Water Sewer Backup Insurance Covers
2 Structural repairs to floors, walls, ceilings
2 Personal property replacement (furniture, electronics, clothing)
2 Mold remediation after the event
2 Additional living expenses (hotel, meals)
2 Debris removal & professional cleanup
Not Covered
2 Floodwater coming from outside
2 The broken sump pump itself
2 Gradual leaks or wear and tear
With more than 500,000 miles of aging U.S. sewer lines and backup claims growing about 3 % every year, the gap matters. A single basement event now averages more than $12,000.
I’m Jeffrey Joseph of Mitchell-Joseph Insurance Agency, and we see this loss regularly in Monroe County and the Finger Lakes. The good news? Adding the endorsement usually costs less than a family streaming subscription.

Key links if you want to dive deeper:
- does homeowners insurance cover water damage from sewer backup
- water damage due to rain
- does sewer line protection covers clogged tub
Water & Sewer Backup 101: How It Differs From Standard and Flood Insurance
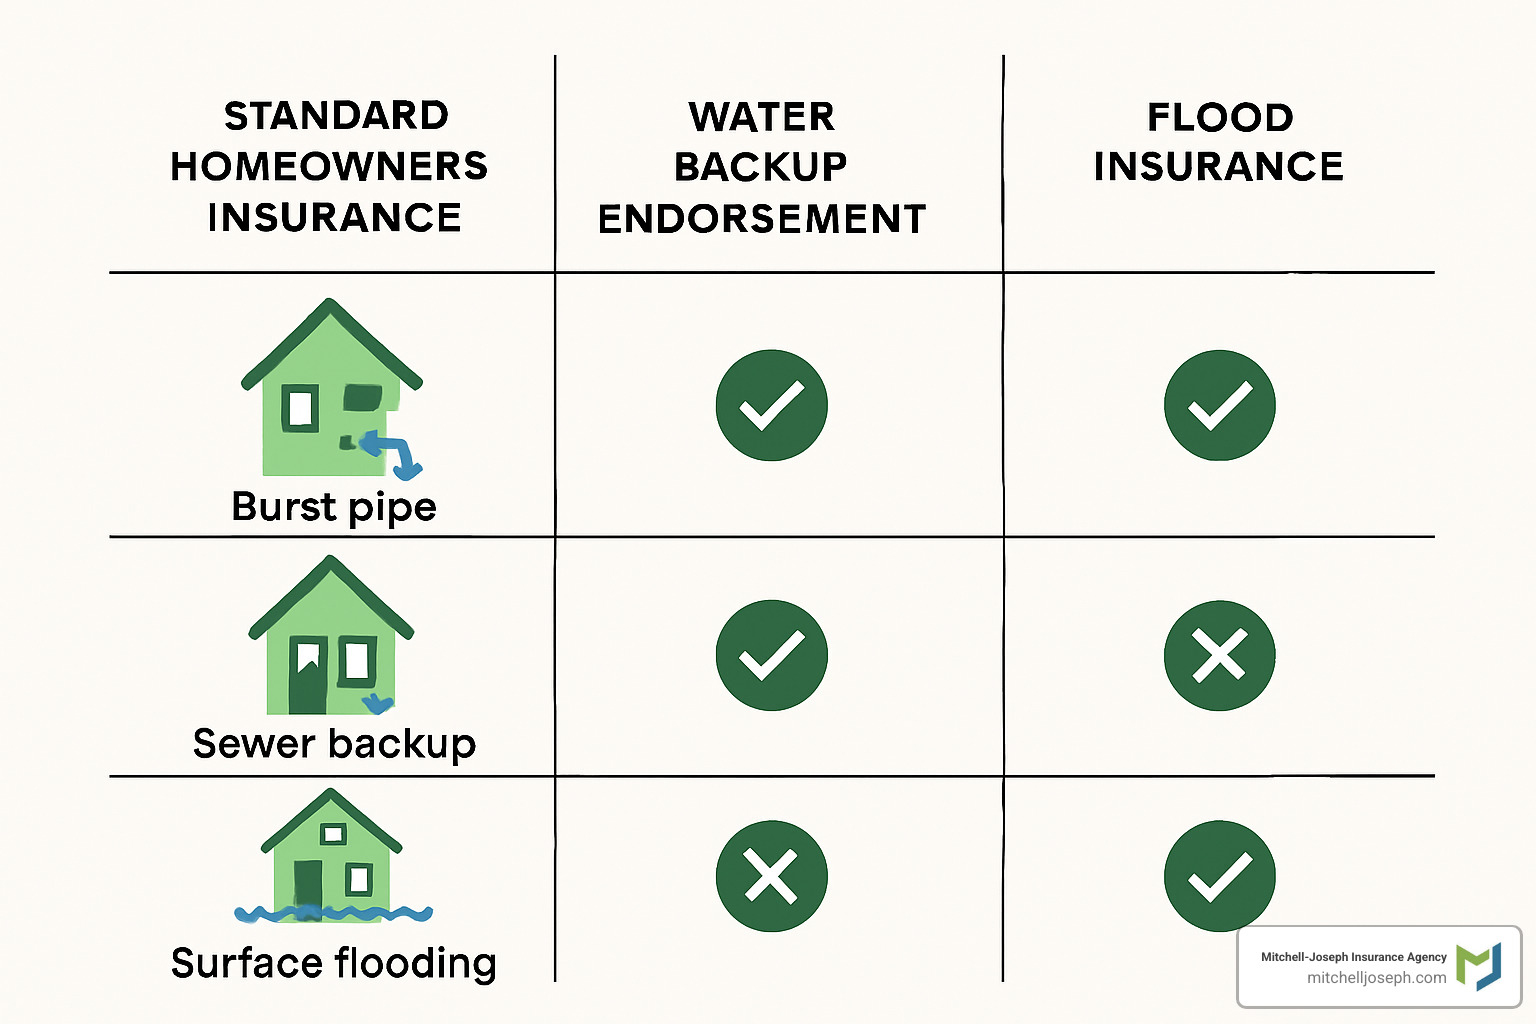
Your basic homeowners policy pays for sudden bursts (think frozen pipe) but excludes any water that comes up through drains, sewers, or a failed sump pump. That gap is filled by the water backup endorsement, which usually runs $50 – $250 a year for limits between $5,000 and your home’s full replacement cost.
Why the exclusion? Backups are predictable with aging infrastructure, so carriers price them separately. In our area many sewer systems date to the 1960s–70s and struggle during today’s heavier rain events.
Common Triggers
- Tree roots invading old clay or cast-iron pipes
- Heavy rain that overwhelms combined sewers
- Power outages that silence sump pumps
- Grease, wipes, or other debris clogs
How Other Policies Fit In
Flood insurance (through the NFIP) covers surface water entering from outside; service-line coverage pays to dig up and fix the broken pipe in your yard. Water backup insurance pays for the mess inside your home. Many of our Victor, Pittsford, and Canandaigua clients carry all three.
More detail: Service Line Coverage | Water Backup vs Flood
What Does Water Sewer Backup Insurance Cover?
Imagine reaching the basement and stepping into an inch of sewage. The endorsement steps in where your base policy stops.
2 Structural repairs – tear-out and replacement of damaged walls, flooring, wiring, and built-ins.
2 Personal property – replacement-cost coverage for the TV, sofa, storage boxes, and more.
2 Mold remediation – professional drying, testing, and removal.
2 Additional living expenses – hotel bills, restaurant meals, pet boarding while repairs occur.
2 Debris removal – certified crews to pump out, disinfect, and haul away contaminated materials.

Real-World Examples Around the Finger Lakes
• Pittsford: tree-root blockage in the municipal main affected six homes; average payout $20,000 each.
• Mendon: septic tank overflow during spring rain; $25,000 loss, all covered.
• Honeoye Falls: power outage killed a sump pump and ruined a finished basement theater; $35,000 claim.
Limits & Exclusions
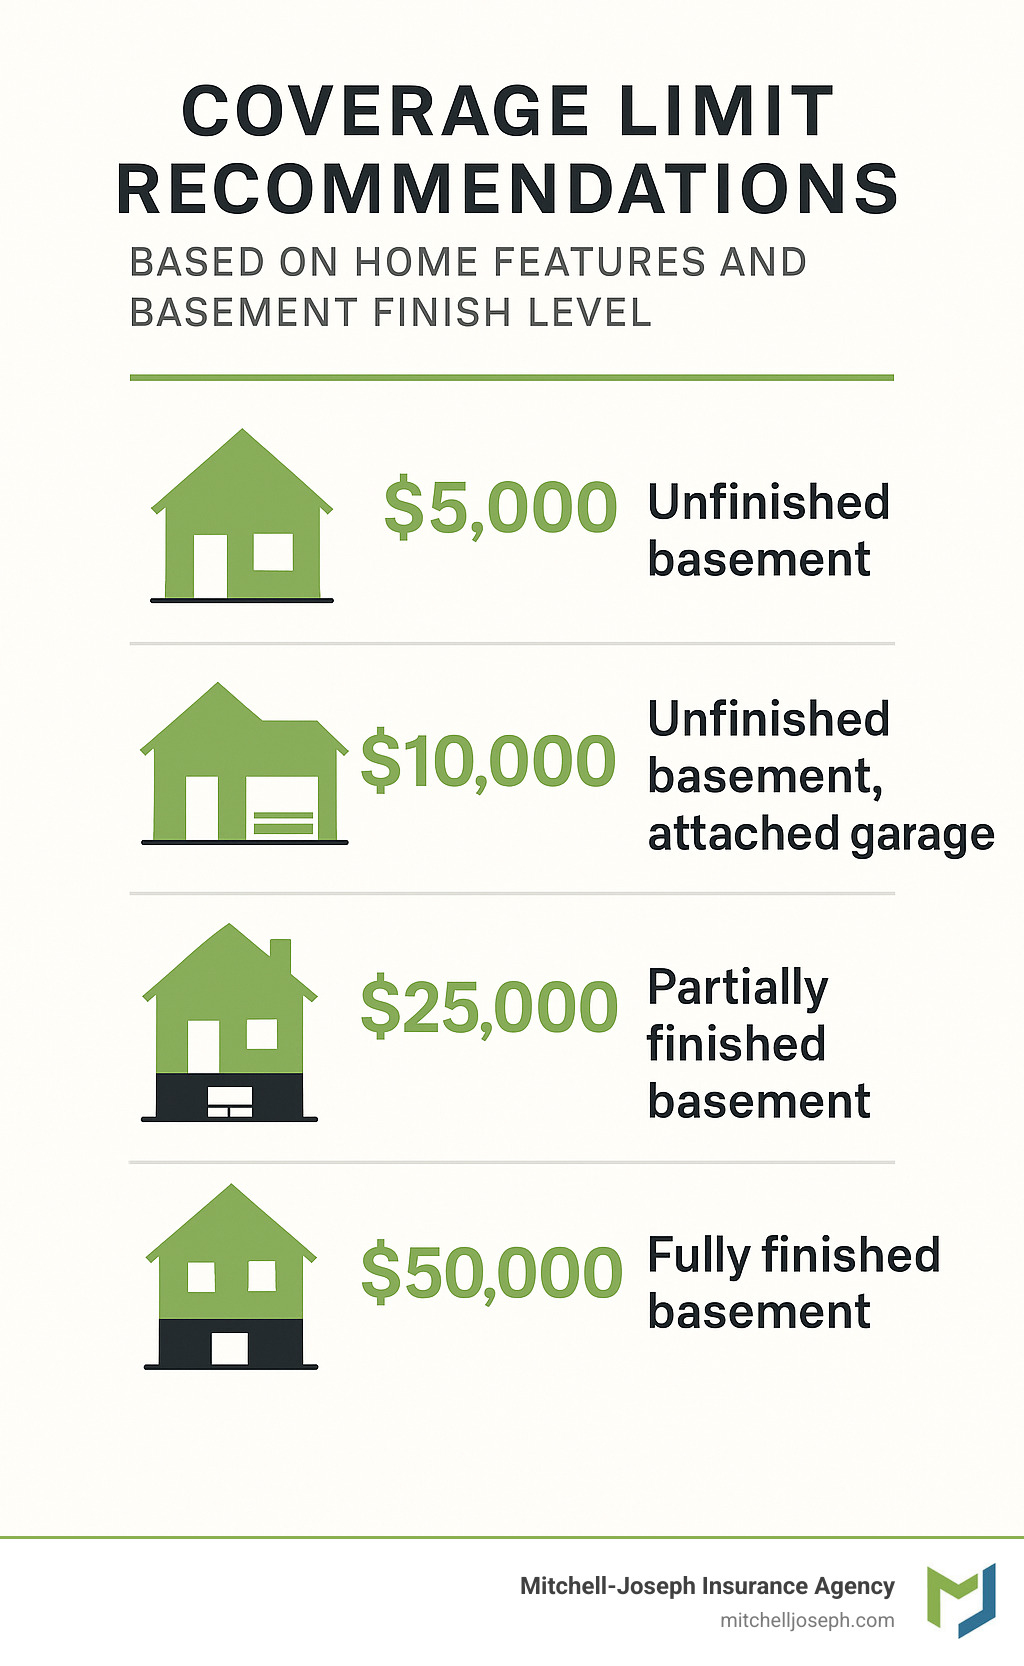
- Choose $5k–$100k; we often recommend at least $25k for finished basements.
- Separate deductible ($250–$1,000) may apply.
- Policy repairs the damage, not the broken pump or pipe.
- Surface floodwater, seepage, or long-term maintenance problems remain excluded.
More detail: Water Sewer Backup Coverage for Homeowners
How Much Coverage Do You Need & What Will It Cost?
Walk through your basement with a calculator: flooring, drywall, electronics, storage boxes. Finished spaces in our region often reach $25,000+ before you blink.
Pricing is modest: about $30–$70 per year for the first $5,000 and $25–$35 for each extra $5,000. Even a $50,000 limit usually stays below $250 annually.
Deductibles & Claim Math
$17,000 loss – $20,000 limit – $500 deductible = $16,500 insurer payment, $500 from you.
Additional-living-expense coverage usually has no deductible.
Adding the Endorsement
Call, text, or email your agent. We quote with 24 partner companies and look for bundle discounts on home/auto. Step-by-step guide: Does Homeowners Insurance Cover Water Damage from Sewer Backup?
Prevention, Response & Filing a Claim
Prevention is cheaper than claims.
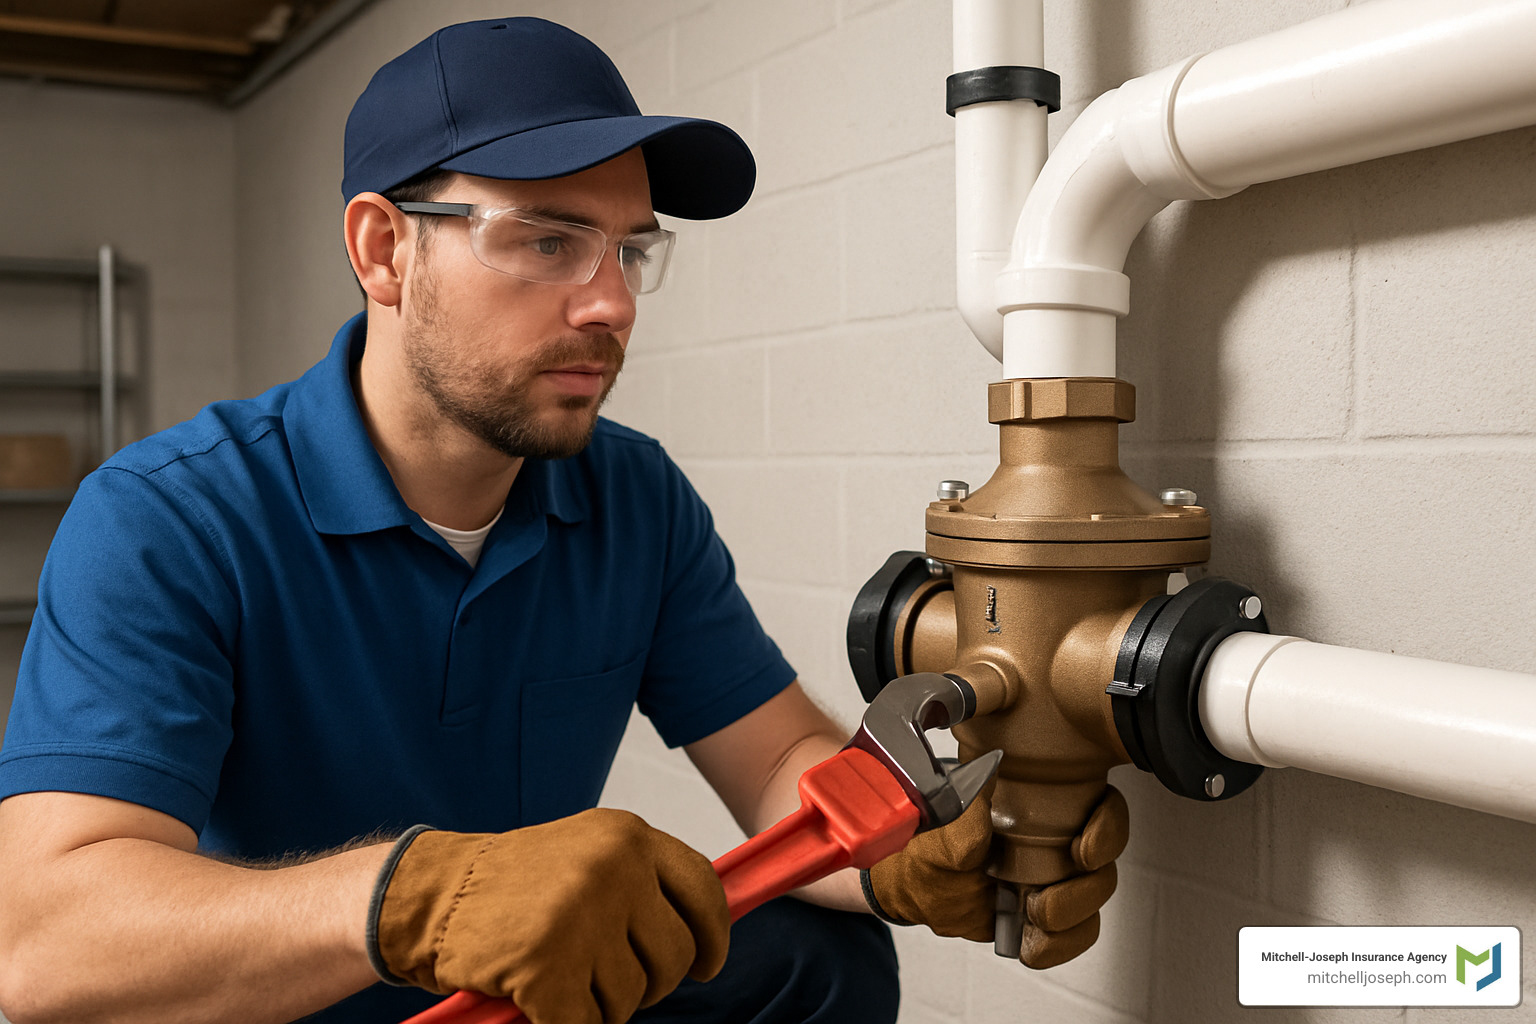
- Install a backwater valve (one-way door in the sewer line).
- Add a battery-backup sump pump and test monthly.
- Clean gutters and dispose of grease & wipes properly.
If a Backup Happens
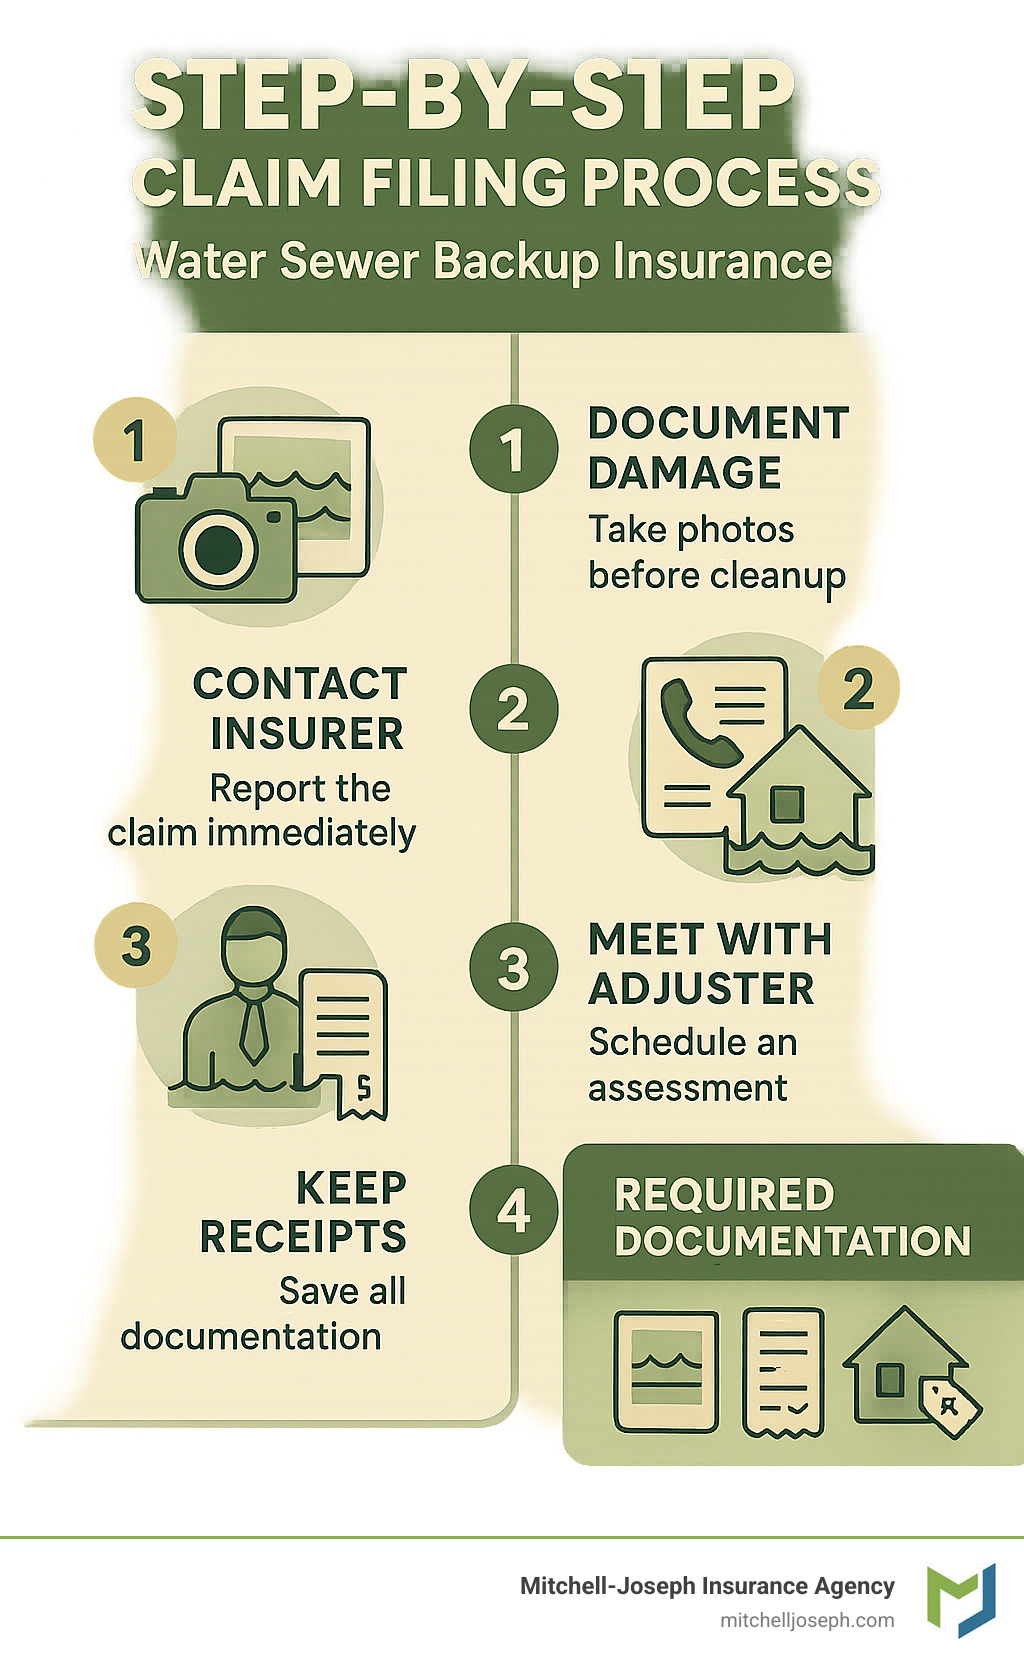
- Stay safe – electricity off, protective gear on.
- Stop the flow if you can.
- Document with photos/video before cleanup.
- Call your insurer 24/7 to open a claim and authorize emergency services.
- Save receipts for cleanup, repairs, and any hotel bills.
Long-term checklist: annual camera inspection of sewer line, root cutting as needed, verify soil grading, and test pumps. More tips: Water Backup Damage
Frequently Asked Questions about what does water sewer backup insurance cover
Is mold cleanup covered?
Yes, when mold comes from a covered backup, but sub-limits (often $5k–$10k) may apply.
Does the policy pay to replace my sump pump?
No. It covers the water damage, not the failed equipment. Ask about equipment-breakdown or manufacturer warranties for the pump itself.
Will my rates go up after a claim?
One claim rarely causes large increases, but multiple claims can trigger surcharges or even non-renewal. Prevention keeps premiums stable.
How fast should I file?
Immediately. Quick reporting allows the carrier to dispatch crews and limit secondary damage.
What documentation helps?
Clear photos/video, a room-by-room list of damaged items (with dates and costs if possible), and all receipts for cleanup, repairs, or temporary living expenses.
Conclusion
A sewer or sump-pump backup can turn a peaceful night in Honeoye Falls, Pittsford, or Victor into a $20,000 headache. For the cost of a family pizza night, water backup coverage turns that nightmare into a covered inconvenience.
Mitchell-Joseph Insurance Agency is an independent, family-owned business with more than 200 combined years of experience and access to 24 insurers. We work for you, not a single carrier, to tailor protection that fits your home and budget.
Have questions or want a quick quote? Visit our flood & water backup solutions page or call our Honeoye Falls office at (585) 624-2180. Let’s close the coverage gap before the next storm does it for you.

