

Introduction: Protecting Your Property from Underground Surprises
Water Line Insurance is specialized coverage that protects homeowners from the significant costs of repairing or replacing the underground water pipes that run from the street to their home. Many homeowners find too late that they are responsible for this line—and that standard homeowners insurance doesn’t cover failures from normal wear and tear.
Quick Facts About Water Line Insurance:
- What it covers: Repair or replacement of your exterior water service line, plus excavation and landscape restoration
- Typical cost: $25-$75 per year as an add-on to your homeowners policy
- Coverage limits: Usually $10,000 to $25,000 per incident, with a deductible around $500
- What it doesn’t cover: Standard homeowners insurance typically excludes water line failures from normal wear and tear
- Average repair cost: $3,750 to replace a main water line, but can reach $22,500 in worst-case scenarios
The risk isn’t small. As one water utility advisory notes, “There are two ways to find that your water main is leaking: slowly, and suddenly.” Either way, you could face thousands in unexpected repair bills. Factors like pipe age (especially lines over 50 years old), corrosion, tree roots, and freezing temperatures all contribute to failures. In communities that offer optional repair programs, utilities routinely see hundreds of claims over short periods—evidence that underground line failures are more common than many homeowners expect.
At Mitchell-Joseph Insurance Agency, we’ve helped homeowners across the Finger Lakes region find the right Water Line Insurance solutions to protect against these costly underground surprises and prevent financial hardship when aging infrastructure fails.
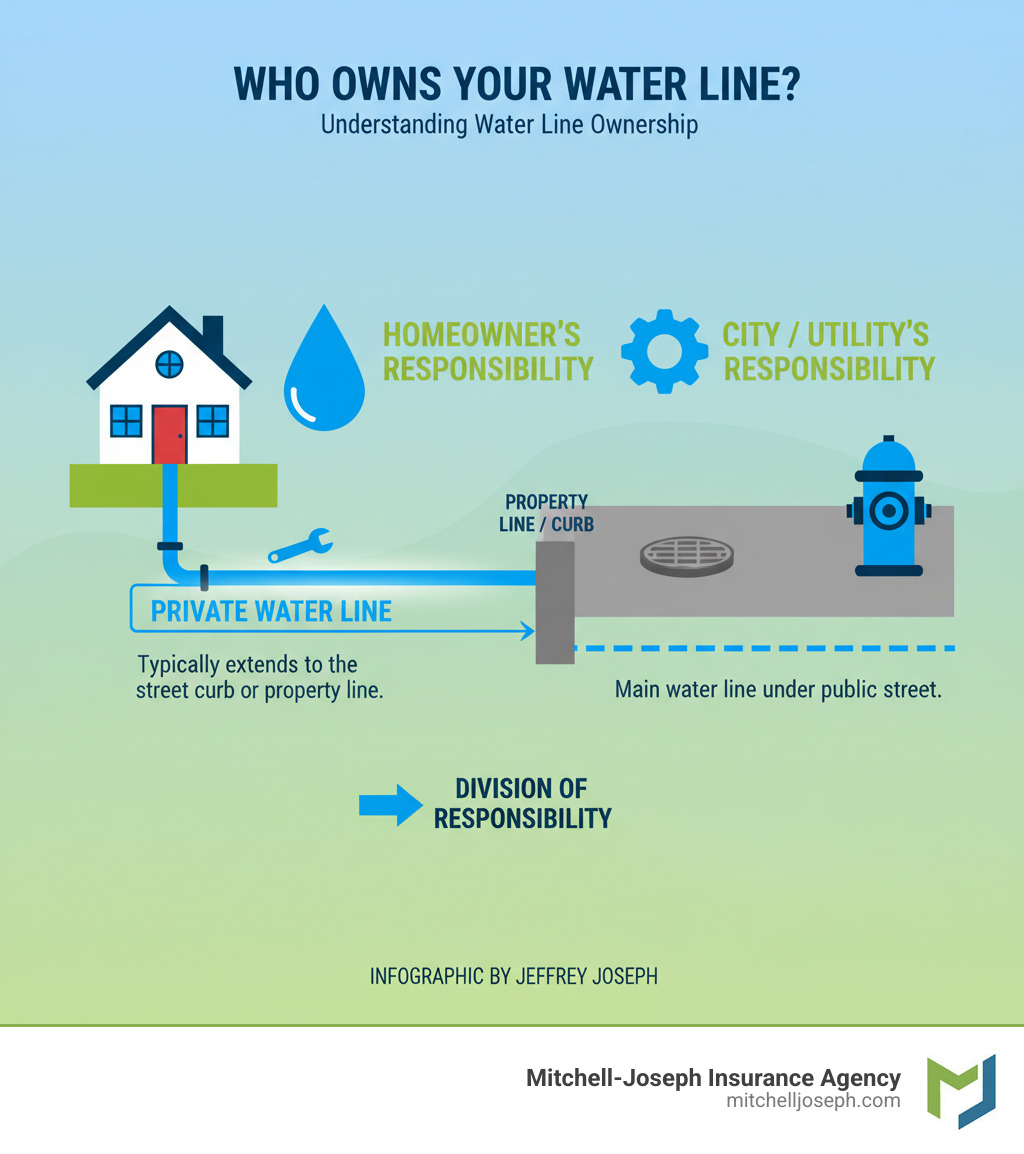
Know your Water Line Insurance terms:
Understanding Your Water Line Insurance Options
Now that you know you’re responsible for the water line to your home, let’s dig into what Water Line Insurance is, how it works, and what you need to know to make an informed decision.
What is Water Line Insurance and What Does It Cover?
Water Line Insurance is a specialized policy, often an endorsement added to your homeowners insurance, that covers the repair or replacement of the underground water line on your property. Most homeowners in the Finger Lakes region are surprised to learn this line is their responsibility, not the city’s.
This coverage is designed to fill a critical gap left by standard homeowners policies. It typically covers:
- Repair or replacement of the exterior water line due to leaks, breaks, or collapse from common causes like corrosion, tree roots, and ground shifting.
- Excavation costs to access the damaged pipe, which can be a significant part of the bill.
- Landscape restoration, including repairs to your lawn, driveway, or sidewalks that were disturbed during the work.
Coverage limits usually range from $10,000 to $25,000 per incident, with a typical deductible of $500. That some policies may offer lower limits for very old pipes. This insurance specifically covers the exterior line from the street to your home’s foundation; damage to interior plumbing is handled separately by your standard homeowners policy.
How Water Line Insurance Works with Your Homeowners Policy
A common misconception is that standard homeowners insurance covers your exterior water line. It doesn’t. Homeowners policies are designed for sudden, accidental damage to your home’s structure, not for issues like corrosion, tree roots, or ground shifting that cause most water line failures. As Fixr.com bluntly puts it, “Your homeowner’s insurance likely won’t cover water pipes outside your house, and your friendly local water utility won’t come out and fix it for free, either.”
This is the gap Water Line Insurance is designed to fill.
The easiest way to get this protection is by adding a service line endorsement to your homeowners policy. This integrates the coverage seamlessly. Standalone service plans from third-party companies also exist, but they function as service contracts and may have different terms and waiting periods.
If you have an endorsement and need to file a claim, you simply contact your insurance provider. They will guide you through the process and help arrange for a professional repair, with costs covered up to your limit after the deductible.
Here’s how the two types of coverage compare:
| Feature | Standard Homeowners Policy | Water Line Insurance Endorsement |
|---|---|---|
| Coverage Scope | Damage to home structure/contents from sudden, accidental perils; liability. | Repair/replacement of exterior water service line; excavation; landscape restoration. |
| Covered Events | Fire, theft, windstorm, internal pipe burst (sudden). | Corrosion, tree roots, freezing, ground shifting, mechanical breakdown. |
| Claim Process | Contact your homeowners insurance provider. | Contact your homeowners insurance provider (via endorsement). |
| Typical Cost | Base premium. | Small additional premium (e.g., $25-$75/year). |
Common Causes and Costs of Water Line Damage
Several factors contribute to water line failure, many of which are common in the Finger Lakes region. Understanding these risks helps clarify why Water Line Insurance is a smart investment.
Common causes include:
- Age: Pipes over 50 years old are at high risk of becoming brittle and failing.
- Corrosion: Older metal pipes can rust and degrade from the inside out.
- Tree Roots: Roots seeking water can invade and crush pipes.
- Ground Shifting & Freezing: New York’s freeze-thaw cycles put immense stress on underground lines, leading to cracks and breaks.
The financial impact of a failure can be substantial. According to Fixr.com, the average cost to replace a main water line is $3,750. However, costs can range from $1,215 for a simple PVC repair to over $22,500 for a complex replacement under a driveway. As HomeAdvisor data on similar underground repairs shows, these are not minor expenses. Without coverage, a homeowner must bear these costs alone.
Typical Exclusions and Limitations to Be Aware Of
Like any policy, Water Line Insurance has exclusions and limitations. It’s important to understand what isn’t covered to avoid surprises.
- Pre-existing conditions: Damage that existed before your policy began is not covered.
- Waiting periods: Most policies have a 30-day waiting period before you can file a claim.
- Age-based limits: Coverage may be reduced for very old pipes (e.g., 50+ years).
- Interior plumbing: The policy covers the exterior line to your foundation, not pipes inside your home.
- Septic systems and well components: These typically require separate coverage for components like the tank or pump, though the line itself may be covered.
- Blockages without damage: Clogs or low pressure are usually not covered unless there is a physical break or leak in the pipe.
- Other exclusions: Policies may also exclude damage from natural disasters (like earthquakes), faulty workmanship, or issues with non-operational lines.
Reviewing these details with an agent ensures you understand the boundaries of your protection.
Making the Right Decision for Your Home
Deciding on coverage requires weighing the risks against the costs. Here’s how to determine if it’s a smart investment for your property.
Is Water Line Insurance Worth the Cost for You?
Is spending $25 to $75 a year on Water Line Insurance a good investment? For many homeowners in communities like Bloomfield, Bristol, or Canandaigua, the answer is a clear yes. To decide if it’s right for you, consider these questions:
- How old is your home? If it’s over 50 years old, your water line is likely nearing the end of its lifespan. Older materials like galvanized steel are especially vulnerable.
- What’s your environment like? Mature trees, heavy clay soil, and the harsh freeze-thaw cycles common in New York all increase the risk of pipe damage.
- Have neighbors had issues? Water line breaks on your street can be a sign of aging infrastructure affecting the whole neighborhood.
- Can your finances handle a surprise bill? Repair costs average $3,750 but can soar to $22,500, according to data from Fixr.com and HomeAdvisor. If a bill that large would strain your savings, insurance provides crucial peace of mind. As AARP suggests, an emergency fund is vital, but insurance can protect that fund from being depleted by a single event.
For those in newer homes with modern piping and a robust emergency fund, the risk may be lower. But for most others, especially those in older homes, the small annual cost is a smart way to prevent a major financial headache.
How to Find and Evaluate Your Water Line Insurance Options
Finding the right Water Line Insurance is straightforward.
1. Review Your Current Policy: Start by checking your homeowners policy for an existing “service line” or “buried utility lines” endorsement. If you’re unsure, an agent can help.
2. Contact an Independent Agent: This is where we can help. At Mitchell-Joseph Insurance Agency, we serve families throughout the Finger Lakes region. As an independent agency, we work with 24 different insurers, not just one. This allows us to shop for the best coverage and rates on your behalf, custom to your home’s specific risks.
3. Evaluate Your Options: When comparing policies, look for:
- Coverage Limits: Aim for $10,000 to $25,000 to cover a major repair.
- Deductible: A $500 deductible is common and reasonable.
- Exclusions: Understand what isn’t covered, such as pre-existing conditions or age-based limits.
- Waiting Period: Be aware of any delay (often 30 days) before coverage begins.
- Provider Reputation: Ensure the company has a good track record for handling claims efficiently.
We’re here to walk you through these details, answer your questions, and help you find the right protection. Don’t wait for an emergency to find a gap in your coverage.
Ready to get started? Explore your water line insurance options with Mitchell-Joseph Insurance Agency today. We’ll help you find the right protection for your home and your peace of mind.

