

Your Guide to Understanding New York Home Insurance
New York home insurance quotes are essential for protecting your property investment in the Empire State. Here’s what you need to know:
Quick Answer: What to Expect from NY Home Insurance Quotes
- Average Cost: $1,715-$2,295 per year for standard coverage (below the national average)
- What’s Included: Dwelling, personal property, liability, loss of use, and medical payments
- Required Coverage: Not legally mandated, but mortgage lenders require it
- Key Factors: Location, home age, construction materials, claims history, and credit score
- Regional Differences: NYC averages $2,625/year vs. Rochester at $1,464/year
- Common Add-Ons: Flood insurance, water backup, and increased liability limits
New York homeowners face unique challenges, from harsh winters with frozen pipes to coastal hurricane threats. Understanding your insurance options is crucial to protect your home and finances from these risks. Getting accurate quotes requires specific details about your property, and the process of comparing policies can feel overwhelming.
I’m Jeffrey Joseph, and I’ve been helping homeowners steer New York home insurance quotes since 1999 at Mitchell-Joseph Insurance Agency. Serving the Finger Lakes Region, including Rochester and Canandaigua, my experience has shown me how dramatically rates and coverage needs vary across our state.
New York home insurance quotes terms at a glance:
Decoding New York Home Insurance Quotes & Coverage
Understanding your homeowners insurance in New York is about finding the right protection for your unique home and lifestyle. We’re here to help you decipher the complexities, from average costs to essential coverages and the specific risks New York homeowners face.
Average Cost of New York Home Insurance Quotes & Key Factors
The average annual cost of homeowners insurance in New York ranges from $1,755 to $2,404. While this may seem high, New York’s average premium of $1,816 (for $300k dwelling coverage) is actually below the national average of $2,601. However, this is just an average, and your specific New York home insurance quotes will vary based on several key factors:
- Location: Your home’s location significantly impacts rates. Factors include risks of natural disasters (flooding, winter storms), local crime rates, and proximity to fire services. Coastal homes often have higher premiums due to hurricane risk.
- Home Age and Condition: Older homes can have higher insurance costs due to outdated systems. Newer or recently renovated homes may qualify for discounts.
- Construction Materials: Homes built with resilient materials like brick may have lower premiums than frame homes due to their durability.
- Claims History: A clean personal and property claims history often leads to lower premiums. Insurers use a CLUE report to check for claims in the past seven years.
- Credit Score: In New York, insurers can use a credit-based insurance score to help determine premiums. A good score may lead to lower rates.
- Coverage Limits and Deductibles: Higher coverage limits increase your premium, while a higher deductible typically lowers it.
For more detailed information on how these factors affect your rates, we invite you to explore our page on New York Home Insurance Rates.
Standard Policy Coverage vs. Recommended Add-Ons
A standard HO-3 policy in New York protects your home from many perils, but it’s crucial to know what’s included and where you might need extra coverage.
Here’s what typically comes standard:
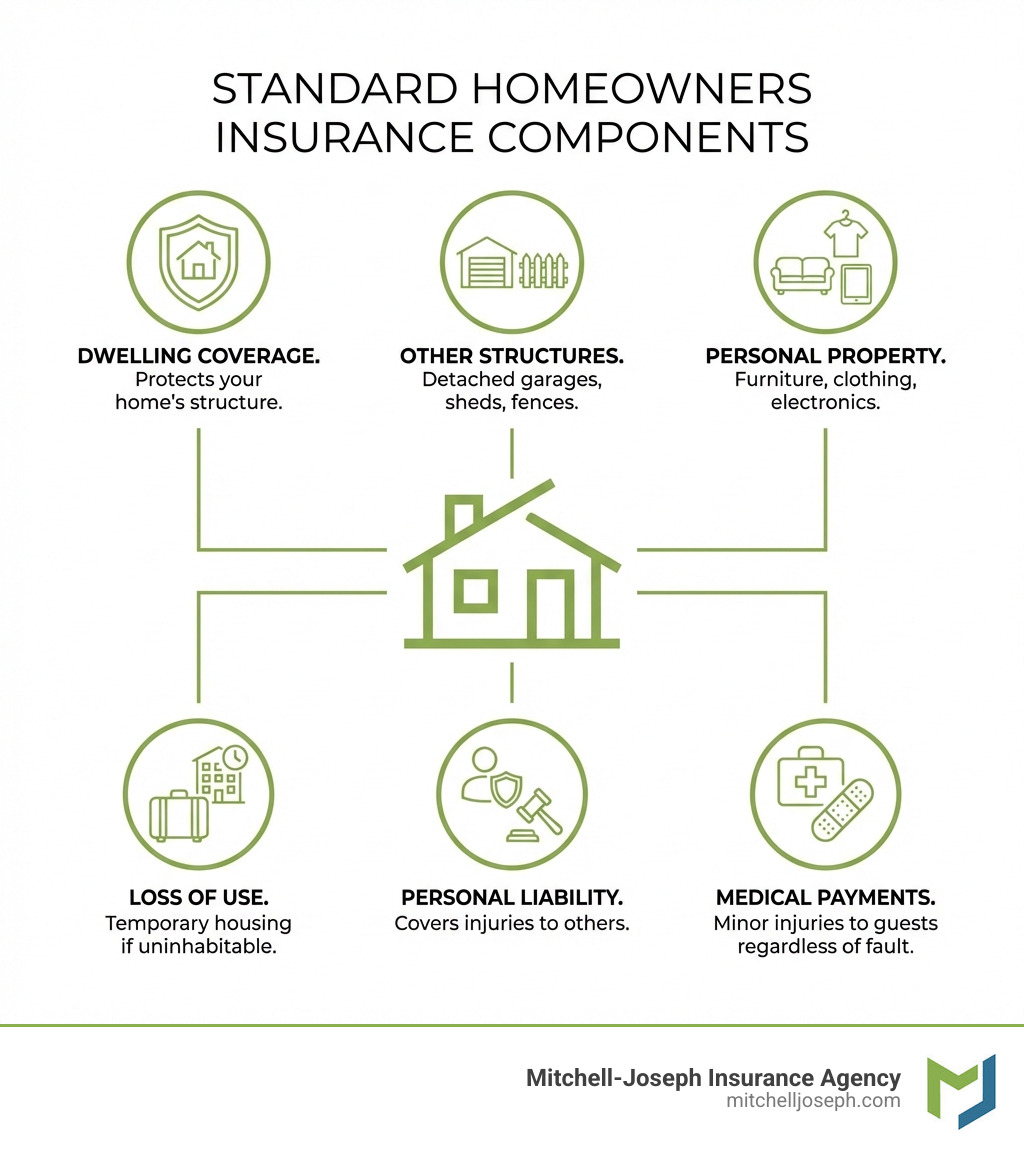
- Dwelling Coverage (Coverage A): Protects your home’s physical structure (foundation, walls, roof). We recommend insuring for full replacement cost.
- Other Structures Coverage (Coverage B): Covers structures not attached to your home, like detached garages, sheds, and fences.
- Personal Property Coverage (Coverage C): Protects your belongings. For high-value items like jewelry, consider a “Scheduled Personal Property Endorsement” for adequate protection.
- Loss of Use Coverage (Coverage D): Also known as Additional Living Expenses, this covers costs like hotel stays if your home is uninhabitable after a covered loss.
- Personal Liability Coverage (Coverage E): Protects you financially if someone is injured on your property. We typically recommend at least $300,000 in coverage.
- Medical Payments to Others (Coverage F): Covers minor medical bills for guests injured on your property, regardless of fault.
While standard coverage is robust, we often recommend these add-ons for New York homeowners:
- Flood Insurance: Standard policies do not cover flood damage. With New York’s vulnerability to flooding, this separate policy is crucial. It’s available through the National Flood Insurance Program (NFIP) or private insurers.
- Water Backup and Sump Pump Overflow Coverage: Covers damage from water backing up through sewers or drains. It’s a valuable addition for many NY homes, especially those with basements. Learn more on our Sewer and Water Backup Insurance page.
- Service Line Coverage: Protects against expensive repairs to your underground utility lines (water, sewer), which are not covered by standard policies.
- Extended Replacement Cost: Provides an extra cushion (typically 20-25%) above your dwelling limit to cover rebuilding costs if they surge after a widespread disaster.
- Building Code Upgrade (Law and Ordinance): Helps pay for the increased costs of rebuilding your home to current, stricter building codes after a covered loss.
For a deeper dive, visit our Home Insurance Coverage Types page and our guide on Homeowners Insurance and Flood Insurance.
Navigating NY-Specific Risks and Requirements
Understanding New York’s local nuances is key to securing comprehensive New York home insurance quotes.
Homeowners insurance is not legally required by New York State, but mortgage lenders mandate it to protect their investment. Going uninsured is a major financial risk we strongly advise against.
New York’s weather presents several risks:
- Harsh Winters: Heavy snow, freezing temperatures, and ice dams can lead to burst pipes and water damage.
- Thunderstorms and Hail: Summer storms can damage roofs and siding.
- Coastal Threats: Proximity to the Great Lakes and other large water bodies brings risks of high winds, storm surges, and flooding, especially from hurricane remnants.
If you live in a coastal area, your policy may include a hurricane deductible. This is a percentage (e.g., 2-5%) of your dwelling coverage, not a fixed dollar amount. For a home insured at $300,000 with a 2% deductible, you’d pay the first $6,000 for hurricane damage. It’s vital to know if your policy has one, as its absence could mean no hurricane coverage at all.
For more on how severe weather impacts your insurance, see our article on Weathering the Storms: Severe Weather Damage. The general need for flood awareness is high across the state, as even areas like New York City are highly vulnerable to flooding.
How to Get the Best New York Home Insurance Quotes
Getting the best New York home insurance quotes means finding the right coverage at a competitive rate. The process is smoother if you have the necessary information ready.
To get an accurate quote, have this information ready:
- Property Address
- Year Built and Square Footage
- Construction Materials (roof, exterior)
- Safety and Security Features (alarms, smoke detectors)
- Personal Information (name, date of birth, SSN for credit-based score)
- Mortgage Lender Information
- Existing Policy Details (if applicable)
City vs. State Cost Differences:
Rates fluctuate significantly across New York. For example, NYC’s average rate of $2,625 is much higher than Rochester’s at $1,464, due to factors like population density and property values. This highlights the importance of local expertise. We specialize in the Finger Lakes region, understanding its unique insurance landscape. For specific insights, visit our page on Home Insurance Rochester.
Smart Strategies for Lowering Your Premiums
While you can’t control every factor influencing your New York home insurance quotes, several strategies can help lower your premiums.
Here are our top money-saving tips:
- Increase Your Deductible: A higher deductible lowers your premium but increases your out-of-pocket cost for a claim. Choose an amount you can comfortably afford.
- Bundle Your Policies: Insuring your home and auto with the same company often leads to significant savings.
- Install Security and Safety Systems: Monitored security systems, fire alarms, and other protective devices can earn you discounts.
- Maintain Your Home: Keeping your roof, plumbing, and electrical systems in good repair can prevent claims and may lower rates.
- Improve Your Credit Score: A good credit history can translate to better insurance rates.
- Review Your Coverage Annually: Meet with us yearly to ensure your coverage matches your current needs and that you’re getting all eligible discounts.
- Ask About All Available Discounts: We can help you find discounts for loyalty, being claim-free, having a new home, and more.
- Go Paperless and Pay in Full: Some insurers offer small discounts for paperless billing or paying your annual premium at once.
By implementing these strategies, you can make a real difference in your insurance costs. For more details, visit our Homeowners Insurance Discounts page.
Partner with an Expert for Your NY Home Insurance Needs
Navigating New York home insurance quotes can be complex. We’ve covered costs, coverages, NY-specific risks, and money-saving strategies. The key takeaway is that protecting your most significant investment requires more than a generic policy—it demands coverage custom to your property and lifestyle. This is where an independent insurance agent provides immense value.
As an independent, family-owned business with over 200 years of combined experience, Mitchell-Joseph Insurance Agency isn’t tied to one company. We work with 24 carriers to shop for the best New York home insurance quotes for your needs and budget. We provide personalized service, taking time to understand your situation and explain your options clearly.
We serve our neighbors in Honeoye Falls, Pittsford, Naples, Rushville, Avon, Bloomfield, Bristol, Canadice, Canandaigua, Cohocton, Fishers, Gorham, Honeoye, Ionia, Lima, Mendon, Middlesex, Potter, Rochester, Rush, South Bristol, Stanley, Victor, Wayland, and West Bloomfield.
Let us put our expertise to work for you. Contact us today for a free, no-obligation quote, and let’s ensure your New York home is protected. We’re dedicated to helping you find the Cheapest Home Insurance New York without compromising on the coverage you deserve.

