

Your Guide to Lower Home Insurance Premiums
Save on home insurance by taking advantage of these proven strategies that can reduce your premiums by hundreds of dollars annually:
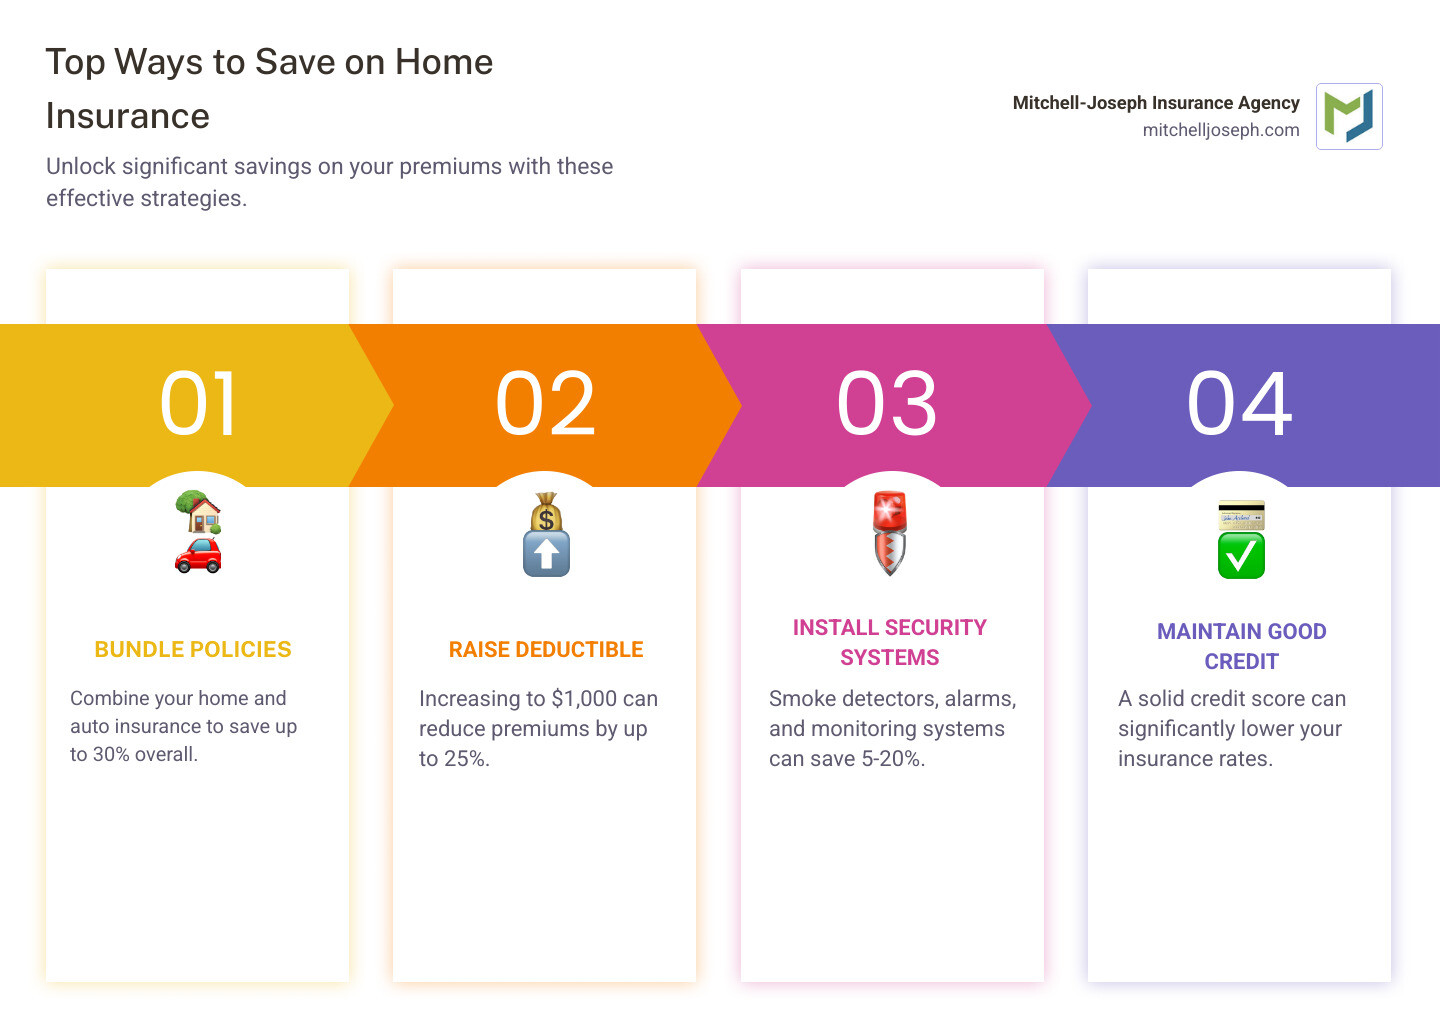
- Bundle your policies – Combine home and auto insurance to save up to 30% overall
- Raise your deductible – Increasing from $500 to $1,000 can reduce premiums by up to 25%
- Install security systems – Smoke detectors, burglar alarms, and monitoring systems can save 5-20%
- Improve disaster resistance – Upgrade your roof, add storm shutters, or modernize systems
- Maintain good credit – A solid credit score can significantly lower your rates
- Pay annually – Avoid monthly processing fees and save 5-10%
- Review coverage regularly – Ensure you’re not over-insured or missing discounts
You don’t have to live in a disaster-prone area for your homeowners insurance bill to feel like disaster has struck. Homeowners saw an average 12% jump in premiums in 2023, followed by another 6.9% increase in the first half of 2024. These sharp rises far exceed the historical average of about 5% per year.
The good news? You have more control over your insurance costs than you might think.
Unlike factors such as your home’s location or age, many premium-reducing strategies are entirely within your reach. From making smart policy adjustments to investing in home improvements that lower your risk profile, there are numerous ways to cut costs without sacrificing the protection you need.
Some savings are immediate. Raising your deductible or bundling policies can reduce your premium right away. Other strategies, like upgrading your roof or installing a security system, require upfront investment but pay dividends through long-term savings and added home value.
The key is understanding which discounts apply to your situation and how to stack them effectively. Insurance companies offer various discounts, but they don’t all offer the same ones in every state, and many homeowners miss out simply because they don’t ask.
I’m Jeffrey Joseph, and I’ve been helping homeowners save on home insurance since 1999 at Mitchell-Joseph Insurance Agency in the Finger Lakes region. Throughout my career, I’ve seen how the right combination of coverage adjustments, home improvements, and discount strategies can dramatically reduce insurance costs while maintaining comprehensive protection.
How to Save on Home Insurance: Smart Strategies and Discounts
With construction costs up 40% since 2019 and severe weather on the rise, it’s easy to feel helpless as premiums climb. However, you have more control than you think. The following strategies can put hundreds of dollars back in your pocket annually. Some offer immediate savings, while others are long-term investments. All are proven ways to save on home insurance without compromising the protection your family needs.
Adjust Your Policy and Payments for Immediate Savings
Sometimes the fastest way to lower your premium doesn’t involve any home improvements at all. A few strategic tweaks to your policy can deliver immediate savings.
Raising your deductible is a powerful way to lower your premium. The deductible is what you pay out-of-pocket on a claim before insurance pays. A higher deductible means a lower premium because you assume more initial risk. The savings are substantial: increasing your deductible from $500 to $1,000 can cut your premium by up to 25%. Just be sure to choose an amount you can comfortably cover from an emergency fund.
Paying your annual premium upfront is a simple way to save. Many insurers offer a “paid-in-full” discount of 5% to 10% for paying the full year at once. This also helps you avoid the small processing fees that come with monthly payment plans. If your budget allows, this one-time payment is a smart move.
Understanding how your property is valued is key. Actual Cash Value (ACV) coverage pays for an item’s original cost minus depreciation. This means a lower premium, but if your 10-year-old roof is destroyed, you’ll only get its depreciated value, leaving you with significant out-of-pocket costs for a new one. Replacement Cost (RC) coverage pays to replace damaged property with new items of similar kind and quality, with no deduction for depreciation. While RC coverage has a higher premium, it provides greater financial protection and peace of mind. We recommend it to most homeowners. For a deeper look at these coverage options and how they fit into your overall policy, visit our page on Home Insurance Coverage Types.
Here’s how they compare side by side:
| Feature | Actual Cash Value (ACV) | Replacement Cost (RC) |
|---|---|---|
| Premium Cost | Generally lower | Generally higher |
| Payout Basis | Original cost minus depreciation | Cost to replace with new item (no depreciation) |
| Out-of-Pocket | More likely to pay more out-of-pocket for new items | Less likely to pay more out-of-pocket for new items |
| Coverage Level | Less comprehensive, covers depreciated value | More comprehensive, covers full replacement value |
| Peace of Mind | Lower, as you might not get enough to fully replace | Higher, as you can replace items without depreciation hit |
Proactive Ways to Save on Home Insurance Through Home Upgrades
Certain home improvements don’t just make your house safer—they can dramatically reduce your insurance costs by lowering your risk profile.
Installing security and safety systems is an easy way to earn discounts. Basic devices like dead-bolt locks and smoke detectors can save you 5% or more. A professionally monitored burglar alarm can increase that discount to 15-20%. Advanced fire safety systems, including carbon monoxide sensors or sprinklers that alert a monitoring station, can also earn discounts in the 15-20% range. Don’t forget water leak detectors, especially those with automatic shut-offs; they can save you 2-6% and prevent catastrophic water damage. Before installing a system, check with your agent to see which upgrades qualify for discounts with your carrier.
Making your home disaster-resistant protects your property and can open up significant premium reductions. Meeting specific construction standards, like the Insurance Institute for Business and Home Safety’s FORTIFIED designations, strengthens your home against hazards and can earn substantial discounts. Your roof is critical. A new roof can prevent surcharges, while upgrading to an impact-resistant roof can qualify you for discounts up to 35%, especially in areas prone to hail or high winds. Using hail-resistant or Class 4 shingles can earn further credits. In hurricane-prone areas, storm shutters or hurricane-resistant windows reduce your risk and premiums. In wildfire zones, creating defensible space by clearing brush can save around 5%. Modernizing your plumbing and electrical systems is also crucial. Updating older systems reduces the risk of fire and water damage, making your home safer and more attractive to insurers. For a comprehensive look at specific discounts tied to home upgrades, check out our Homeowners Insurance Discounts page.
Leverage Personal and Policy-Specific Discounts
Beyond home upgrades, many discounts are based on your personal profile and policy management.
Bundling your home and auto insurance is one of the most straightforward ways to save on home insurance. Combining policies with the same insurer typically earns a multi-policy discount of up to 30% overall.
Your claims history matters. A claim-free record for three to five years can qualify you for a discount. It often makes sense to handle minor repairs yourself to avoid filing small claims that could raise your rates.
Loyalty can pay off. Some insurers offer discounts of 5% after three years and 10% after six. However, always compare rates to ensure your loyalty isn’t costing you more in the long run.
Age brings benefits. Many insurers offer senior discounts for homeowners over 50, with some targeting retirees 55 and older with discounts up to 10%. Always ask if you’re in these age brackets.
Your credit score has more influence than you might expect. In most states, insurers use a credit-based insurance score to help determine your premium. Maintaining good credit by paying bills on time and keeping debt low can significantly reduce your insurance costs, while poor credit can have the opposite effect. Regularly check your credit report for errors that could be costing you money.
Many other discounts are available. Ask your agent about savings for new homes, going paperless, being a non-smoker, or living in a secured community. You might also qualify for discounts related to green home certifications (LEED), accredited builder discounts, or getting an advance quote. The key is to ask your agent about every possible discount—they add up quickly, and many homeowners leave money on the table by not inquiring.
Partner with an Expert to Maximize Your Savings
You’ve learned about deductibles, discounts, and disaster-resistant roofing. You understand the value of bundling and the impact of your credit score. But here’s the truth: navigating home insurance can still feel like trying to solve a Rubik’s Cube blindfolded. That’s exactly where partnering with an experienced, independent insurance agent becomes your secret weapon.

The Importance of Annual Policy Reviews
Think about your home insurance policy. When was the last time you actually looked at it? If you’re like most homeowners, it’s probably been sitting in a drawer (or lost in your email) since the day you signed it.
Here’s the thing: your life changes constantly. You renovate the kitchen. You finally finish that basement. Your kids move out, or maybe they move back in (it happens!). Your home’s value increases. Yet your insurance policy? It stays frozen in time unless you actively review it.
This is why we’re passionate about periodic reviews of your home insurance policy. We recommend sitting down at least once a year to give your coverage a thorough checkup. It’s like going to the dentist, but less painful and potentially more rewarding.
During these annual reviews, we help you spot coverage gaps that might have developed. Maybe those home improvements increased your property value beyond what your current policy covers. Perhaps you’ve acquired some valuable jewelry or art that needs special protection. We make sure your coverage actually matches your current reality, not your reality from three years ago.
We also hunt for new discounts you might now qualify for. Insurance companies update their offerings regularly, and you might be eligible for savings you didn’t qualify for before. Did you just turn 55? That senior discount is waiting for you. Finally installed that security system you’ve been putting off? Let’s get you that discount!
And of course, life changes matter. Getting married, retiring, or even improving your credit score can all impact both your insurance needs and the discounts available to you. An annual review ensures you’re not leaving money on the table.
The Benefits of Shopping Around
Here’s a fact that might surprise you: the same home insurance coverage can vary by hundreds of dollars between different companies. Yes, hundreds! It’s like shopping for the same TV at different stores and finding wildly different price tags.
Every insurance company uses different formulas to calculate risk. What one insurer considers a high-risk factor, another might barely notice. One company might offer aggressive discounts for security systems, while another focuses more heavily on bundling discounts. This variety is actually your advantage.
Getting quotes from at least three different companies is one of the most effective ways to save on home insurance. But here’s where it gets tricky: comparing insurance policies isn’t like comparing apples to apples. The coverage details, deductibles, limits, and exclusions can vary significantly. Unless you know exactly what to look for, you might end up comparing apples to oranges to… pineapples.
This is precisely where an independent agent becomes invaluable.
Why Choose an Independent Agent Like Mitchell-Joseph Insurance Agency?
At Mitchell-Joseph Insurance Agency, we’ve been serving homeowners throughout the Finger Lakes region since 1999. We’re an independent, family-owned business based in Honeoye Falls, proudly serving communities including Pittsford, Naples, Rushville, and the greater Rochester area—from Avon to Wayland, Canandaigua to Victor, and everywhere in between.
What makes us different? We’re not tied to a single insurance company. Instead, we partner with 24 different insurance carriers. Think of us as your personal insurance shopping service, but with over 200 years of combined experience backing every recommendation.
Here’s how this benefits you: when you work with us, we compare quotes from multiple providers on your behalf. You don’t need to spend your evenings calling different companies or filling out endless online forms. We do the legwork, presenting you with the best options custom to your specific needs and budget.
Because we’re independent, our loyalty is to you, not to any particular insurance company. We’re not trying to squeeze you into a one-size-fits-all policy. Instead, we focus on finding coverage that actually fits your home, your lifestyle, and your financial goals.
We also know how to identify every discount you qualify for. Each of our 24 partner companies has its own unique discount structure, and we understand the nuances of each one. That new roof you installed? We know which carriers offer the best discounts for it. Bundling your home and auto? We’ll find the company that gives you the most savings for that combination.
Our expertise in Homeowners Insurance NY means we understand the specific challenges and opportunities facing New York homeowners. We know which carriers offer the best rates in our region, which ones have the smoothest claims processes, and which ones truly stand behind their customers when disaster strikes.
The bottom line is this: save on home insurance doesn’t have to mean sacrificing quality coverage or spending hours doing research. It means partnering with someone who knows the landscape, understands your needs, and has the resources to find you the best possible value.
Your home is probably your largest investment. Protecting it shouldn’t feel like a chore, and it definitely shouldn’t cost more than necessary. We’re here to make sure you have the right coverage at the right price, with the personal service and expert guidance you deserve.

