

Why Toy Manufacturers Need Specialized Insurance Protection
Toy manufacturer insurance is specialized business coverage designed to protect companies that design, produce, or distribute toys from the unique risks they face—including product liability claims, regulatory compliance issues, and potential recalls. Unlike standard business insurance, it addresses the specific dangers inherent in creating products for children.
Key coverages toy manufacturers need:
- Product Liability Insurance – Protects against claims from defective toys causing injury or property damage
- Product Recall Insurance – Covers costs of pulling unsafe products from market, including notification and replacement
- General Liability Insurance – Covers third-party injuries and property damage at your facility or trade shows
- Workers’ Compensation – Legally required coverage for employee injuries on production floors
- Commercial Property Insurance – Protects buildings, equipment, inventory, and prototypes from damage or theft
- Cyber Liability – Essential for manufacturers of smart toys or those selling online
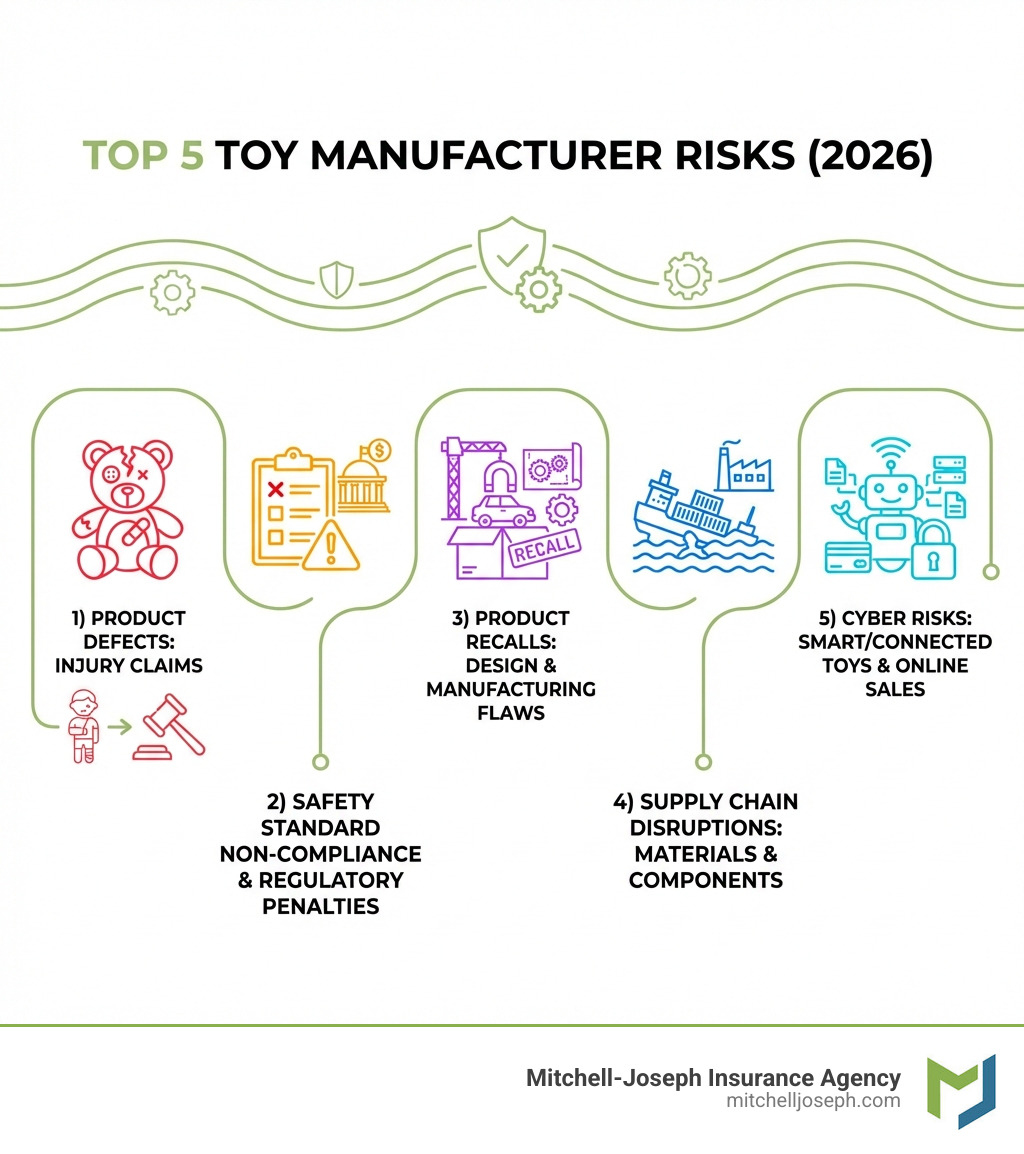
The toy manufacturing industry carries extraordinary responsibility. Every product you create will be handled by children—often the most vulnerable consumers. A single design flaw, manufacturing defect, or labeling error can result in devastating injuries, costly recalls, and lawsuits that threaten your business’s survival. The Consumer Product Safety Improvement Act (CPSIA) and ASTM toy safety standards set strict requirements, and retailers typically require proof of substantial liability coverage before they’ll stock your products. Most toy manufacturers carry between $1-10 million in product liability coverage, with costs averaging about 25 cents per $100 of retail sales. But the right insurance does more than satisfy retailer requirements—it protects the business you’ve built and the joy your products bring to families.
I’m Jeffrey Joseph, and I’ve spent over two decades helping manufacturers across the Finger Lakes region steer complex insurance needs at Mitchell-Joseph Insurance Agency. Understanding the specific risks of Toy manufacturer insurance—from choking hazards to smart toy cyber vulnerabilities—allows me to connect clients with coverage that truly fits their operations, whether they’re crafting wooden puzzles in a small workshop or running a large-scale plush toy production facility.
Common Toy manufacturer insurance vocab:
Decoding Your Toy Manufacturer Insurance Policy: Essential Coverages

When you’re building a business that brings smiles to children’s faces, it’s easy to overlook the serious business of risk management. But a comprehensive toy manufacturer insurance policy isn’t just a safety net; it’s a strategic asset that protects your hard work, your reputation, and your peace of mind. We understand that navigating insurance can seem complex, but we’re here to simplify it for you, ensuring you have the right coverage details for liability protection, asset security, employee safety, and business continuity.
Product Liability: Your Shield Against Defects and Injuries
Imagine a child injured by a toy you manufactured—a small part breaks off, a material causes an allergic reaction, or a design flaw leads to an unexpected mishap. These scenarios, though unfortunate, are a real possibility in the toy industry. That’s where product liability insurance becomes your indispensable shield.
Product liability insurance is a specialized coverage that protects your business from claims alleging that your products caused bodily injury, property damage, or other harm to a third party. For toy manufacturers, this protection is paramount. It addresses claims arising from:
- Design Defects: An inherent flaw in the toy’s design itself, making it unsafe even if manufactured perfectly. For instance, a toy designed with sharp edges that can cause cuts, or a ride-on toy with an unstable center of gravity.
- Manufacturing Flaws: Errors that occur during the production process, leading to a specific batch of toys being unsafe. This could be anything from a faulty electronic component in a smart toy to a batch of plush toys with insecurely attached eyes that pose a choking hazard.
- Inadequate Warnings or Instructions: When a toy lacks clear, sufficient warnings about potential risks, or its instructions for safe use are unclear or missing. This is especially critical for toys with small parts that could be choking hazards or those that require adult supervision.
When a claim arises, product liability insurance covers a range of critical expenses:
- Bodily Injury Claims: Medical bills, rehabilitation costs, and pain and suffering for injuries caused by your product.
- Property Damage: Costs to repair or replace property damaged by your product (e.g., a faulty electronic toy causing a fire).
- Legal Defense Costs: The significant expenses associated with defending your business in court, regardless of whether the claim has merit.
- Settlements and Judgments: Financial payouts if your business is found liable or chooses to settle a claim out of court.
For toy manufacturers, coverage limits typically range from $1 million to $10 million, depending on the type of toys you produce, your annual sales volume, and the perceived risk. While costs vary widely, a general industry average suggests you might pay around 25 cents per $100 of retail sales. For example, if you sell $500,000 worth of goods annually, you could expect to pay about $1,250 for product liability coverage each year. However, if your products are considered “more dangerous,” such as those for very young children or with complex electronic components, your premiums could be higher.
It’s important to understand how product liability differs from general liability insurance, though they often work hand-in-hand.
| Feature | General Liability Insurance | Product Liability Insurance “`
Introduction: The Unique Risks and Rewards of Toy Manufacturing
Toy manufacturer insurance is specialized business coverage designed to protect companies that design, produce, or distribute toys from the unique risks they face—including product liability claims, regulatory compliance issues, and potential recalls. Unlike standard business insurance, it addresses the specific dangers inherent in creating products for children.
Key coverages toy manufacturers need:
- Product Liability Insurance – Protects against claims from defective toys causing injury or property damage
- Product Recall Insurance – Covers costs of pulling unsafe products from market, including notification and replacement
- General Liability Insurance – Covers third-party injuries and property damage at your facility or trade shows
- Workers’ Compensation – Legally required coverage for employee injuries on production floors
- Commercial Property Insurance – Protects buildings, equipment, inventory, and prototypes from damage or theft
- Cyber Liability – Essential for manufacturers of smart toys or those selling online
The toy manufacturing industry carries extraordinary responsibility. Every product you create will be handled by children—often the most vulnerable consumers. A single design flaw, manufacturing defect, or labeling error can result in devastating injuries, costly recalls, and lawsuits that threaten your business’s survival. The Consumer Product Safety Improvement Act (CPSIA) and ASTM toy safety standards set strict requirements, and retailers typically require proof of substantial liability coverage before they’ll stock your products. Most toy manufacturers carry between $1-10 million in product liability coverage, with costs averaging about 25 cents per $100 of retail sales. But the right insurance does more than satisfy retailer requirements—it protects the business you’ve built and the joy your products bring to families.
I’m Jeffrey Joseph, and I’ve spent over two decades helping manufacturers across the Finger Lakes region steer complex insurance needs at Mitchell-Joseph Insurance Agency. Understanding the specific risks of Toy manufacturer insurance—from choking hazards to smart toy cyber vulnerabilities—allows me to connect clients with coverage that truly fits their operations, whether they’re crafting wooden puzzles in a small workshop or running a large-scale plush toy production facility.
Common Toy manufacturer insurance vocab:
Decoding Your Toy Manufacturer Insurance Policy: Essential Coverages
When you’re building a business that brings smiles to children’s faces, it’s easy to overlook the serious business of risk management. But a comprehensive toy manufacturer insurance policy isn’t just a safety net; it’s a strategic asset that protects your hard work, your reputation, and your peace of mind. We understand that navigating insurance can seem complex, but we’re here to simplify it for you, ensuring you have the right coverage details for liability protection, asset security, employee safety, and business continuity.
Product Liability: Your Shield Against Defects and Injuries
Imagine a child injured by a toy you manufactured—a small part breaks off, a material causes an allergic reaction, or a design flaw leads to an unexpected mishap. These scenarios, though unfortunate, are a real possibility in the toy industry. That’s where product liability insurance becomes your indispensable shield.
Product liability insurance is a specialized coverage that protects your business from claims alleging that your products caused bodily injury, property damage, or other harm to a third party. For toy manufacturers, this protection is paramount. It addresses claims arising from:
- Design Defects: An inherent flaw in the toy’s design itself, making it unsafe even if manufactured perfectly. For instance, a toy designed with sharp edges that can cause cuts, or a ride-on toy with an unstable center of gravity.
- Manufacturing Flaws: Errors that occur during the production process, leading to a specific batch of toys being unsafe. This could be anything from a faulty electronic component in a smart toy to a batch of plush toys with insecurely attached eyes that pose a choking hazard.
- Inadequate Warnings or Instructions: When a toy lacks clear, sufficient warnings about potential risks, or its instructions for safe use are unclear or missing. This is especially critical for toys with small parts that could be choking hazards or those that require adult supervision.
When a claim arises, product liability insurance covers a range of critical expenses:
- Bodily Injury Claims: Medical bills, rehabilitation costs, and pain and suffering for injuries caused by your product.
- Property Damage: Costs to repair or replace property damaged by your product (e.g., a faulty electronic toy causing a fire).
- Legal Defense Costs: The significant expenses associated with defending your business in court, regardless of whether the claim has merit.
- Settlements and Judgments: Financial payouts if your business is found liable or chooses to settle a claim out of court.
For toy manufacturers, coverage limits typically range from $1 million to $10 million, depending on the type of toys you produce, your annual sales volume, and the perceived risk. While costs vary widely, a general industry average suggests you might pay around 25 cents per $100 of retail sales. For example, if you sell $500,000 worth of goods annually, you could expect to pay about $1,250 for product liability coverage each year. However, if your products are considered “more dangerous,” such as those for very young children or with complex electronic components, your premiums could be higher.
It’s important to understand how product liability differs from general liability insurance, though they often work hand-in-hand.
| Feature | General Liability Insurance “`

