

Why Restaurant Liability Coverage is Essential for Your Business
Restaurant liability coverage protects your establishment from financial losses due to third-party claims, including customer injuries, property damage, and lawsuits. With millions of daily restaurant visits across Canada, the exposure to liability risks is significant.
Essential restaurant liability coverage includes:
- General Liability Insurance – Covers slip-and-falls, customer injuries, and property damage claims
- Product Liability Insurance – Protects against food poisoning, allergic reactions, and contaminated food claims
- Liquor Liability Insurance – Required for establishments serving alcohol to cover intoxicated patron incidents
- Cyber Liability Insurance – Covers data breaches and stolen customer payment information
- Commercial Auto Insurance – Necessary for delivery operations and employee vehicle use
Running a restaurant means creating spaces for communities to come together. However, the food service industry faces unique risks that can devastate an unprepared business.
A single incident, like food poisoning or a slip-and-fall, can lead to medical bills, legal fees, and settlements large enough to force a restaurant to close permanently.
The good news is that proper insurance coverage can protect your investment and allow you to focus on what you do best: serving great food and creating exceptional dining experiences.
I’m Jeffrey Joseph from Mitchell-Joseph Insurance Agency. Since 1999, I’ve helped hundreds of restaurant owners in the Finger Lakes region find the right insurance. I’ve seen how proper protection can mean the difference between a minor setback and a business-ending disaster.
Understanding Your Restaurant Liability Coverage Needs
Imagine a busy Friday night at your restaurant. A customer slips on a bit of spilled water. Suddenly, you’re facing an injured patron, medical bills, and a potential lawsuit.
This is exactly why restaurant liability coverage exists. It’s your financial safety net for third-party claims—situations where someone gets hurt on your property or claims your business caused them harm.
Without proper coverage, you’d be paying for medical expenses, legal fees, and potential settlements out of your own pocket. For many restaurants, one serious incident could mean closing forever.
The good news is that your insurance should be as unique as your restaurant. Whether you run a busy bistro, a cozy diner, or a food truck, we work with you to understand your specific risks and customize a policy that fits your operations perfectly.
What is General & Product Liability Insurance?
Let’s start with your foundational protection: Commercial General Liability (CGL) and Product Liability insurance. These two coverages handle the most common and costly risks your restaurant faces.
Commercial General Liability (CGL) covers you when someone gets hurt on your property or you damage their belongings. Common CGL claims include:
- Slip-and-fall accidents: A customer slips on a wet floor or trips over a rug.
- Customer injuries: A server accidentally spills hot coffee, or a wobbly chair collapses.
- Property damage: A server spills wine on a customer’s laptop, or a kitchen fire damages the space you rent.
Because you serve food and drinks, Product Liability insurance is also crucial. It protects you from claims related to the products you serve, such as:
- Food poisoning: A customer gets sick after eating at your restaurant.
- Allergic reactions: Cross-contamination or a mislabeled ingredient causes a severe reaction.
- Contaminated food: A customer finds a foreign object in their meal.
For a small restaurant that doesn’t serve alcohol, general liability coverage might cost around $2,000 annually, with premiums typically ranging from $500 to $6,000 per year. Considering a single slip-and-fall claim can easily cost $50,000 or more, this investment is essential.
More info about General Liability Insurance
Specialized Liability: When You Need More Than the Basics
While general and product liability are the backbone of your protection, many restaurants need specialized coverage.
Liquor Liability insurance is often required by law if you serve alcoholic beverages. “Dram shop laws” can hold your establishment accountable for over-serving customers. This policy protects you if an intoxicated patron causes a car accident, gets into a fight, or damages property after leaving your restaurant. Premiums typically range from $400 to $3,000 annually, a small price compared to the millions in damages a single drunk driving incident could cause.
Cyber Liability insurance has become essential. If you take online orders, process credit card payments, or store customer information, you’re at risk for cyber attacks. This coverage helps with the expensive aftermath of a data breach, such as notifying customers, managing your reputation, and handling lawsuits. If you handle customer payment information, this protection is no longer a luxury.
Learn about Cyber Liability Insurance
Common Claims and Why Restaurant Liability Coverage is Crucial
Accidents are part of the business. Understanding what typically goes wrong helps you see why comprehensive restaurant liability coverage is so important.

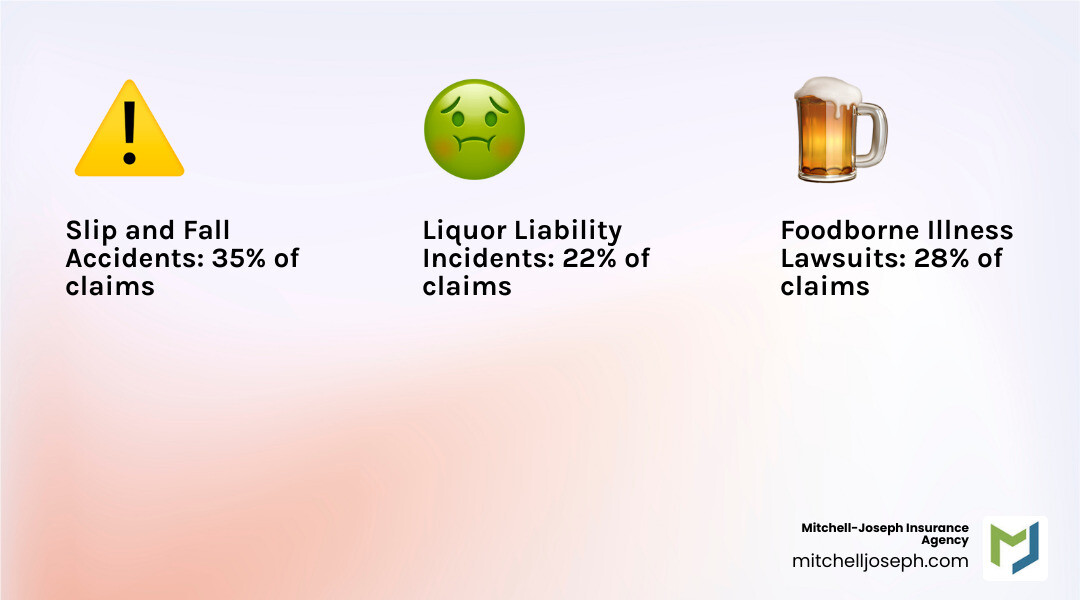
After working with restaurant owners for over two decades, I’ve seen just about everything. These are the most common claims we handle:
- Food poisoning
- Scalding from hot liquids
- Broken teeth
- Choking
- Allergic reactions
- Puncture wounds from broken glass
- Slip and fall incidents
- Alcohol-related incidents (fights, property damage)
These aren’t just theoretical risks—they’re daily realities. Each incident can lead to significant costs, including legal fees, medical expenses, and settlement payouts. This is why robust restaurant liability coverage is essential for your survival.
Preventing slips and falls in your establishment
How Much Does Restaurant Insurance Cost?
I know what you’re thinking: “What’s it going to cost me?” The cost of restaurant liability coverage varies, but it’s influenced by clear factors:
- Location: A busy downtown area with heavy foot traffic will cost more than a quiet suburban spot.
- Annual revenue: Higher sales mean more customers and greater exposure to claims.
- Alcohol sales: Serving alcohol, especially late at night, increases liability and costs.
- Number of employees: More staff can mean a higher potential for accidents.
- Claims history: A clean record helps keep costs down, while previous claims will increase them.
- Policy limits and deductibles: Higher coverage limits increase your premium, while a higher deductible can lower it.
Here’s what you can expect to pay annually for core coverage types:
| Coverage Type | Average Annual Premium Range |
|---|---|
| General Liability | $500 – $6,000 |
| Liquor Liability | $400 – $3,000 |
| Food Contamination | $1,800 |
At Mitchell-Joseph Insurance Agency, we work with 24 different insurance companies to find you the most competitive rates. Our goal is to get you the right coverage at the best price.
Dine-In vs. Delivery: Tailoring Your Liability Coverage
The rise of delivery and takeout has changed the restaurant world and the type of restaurant liability coverage you need.
Traditional dine-in restaurants primarily face premises liability risks like slip-and-falls and customer injuries. Your standard Commercial General Liability policy handles most of these situations well.
Take-out and delivery operations create liability that extends beyond your four walls. Hired and Non-Owned Auto Liability is critical if your employees use their personal vehicles for deliveries, as it fills a gap your standard policy won’t cover. If you use company vehicles, you’ll need a full commercial auto policy.
Even if you use third-party delivery services like Uber Eats, don’t assume you’re completely protected. Gaps in their coverage can exist, and you could still face claims if the food causes illness. We help you steer these complexities to ensure your coverage matches how you actually do business.
Ensuring Adequate Protection for Your Restaurant
You’ve built a special place where people gather and make memories. Now it’s time to protect that investment with the right restaurant liability coverage.
Understanding what’s legally required is your starting point. In Canada, liability coverage is mandatory, but you need a policy that fits your unique situation, not just the bare minimum.
Every restaurant faces different risks. A cozy family diner in Honeoye Falls has different exposure than a busy Rochester establishment. We conduct a thorough assessment of your menu, alcohol service, delivery operations, and location to understand your real-world risks.
Choosing the right coverage limits is crucial. A standard $1 million general liability policy may not be enough. Depending on your business, you might need an umbrella policy that adds another $1 million to $4 million in coverage, providing a bigger safety net.
Your business evolves, and your insurance should too. Regular policy reviews are essential. If you’ve expanded your patio or started catering, your risk profile has changed. We recommend an annual check-in to ensure your coverage still fits.
Insurance can be overwhelming, which is why a trusted partner is so important. At Mitchell-Joseph Insurance Agency, we’re an independent, family-owned business with over 200 years of combined experience. We don’t just sell policies—we become your insurance partner.
We work with 24 different insurance companies, which means we shop around to find you the best coverage at competitive rates. As a local agency, we understand the unique challenges facing restaurants in the Finger Lakes region, from Pittsford to Canandaigua and throughout our area.
Don’t let one unfortunate incident threaten everything you’ve worked to build. The right insurance coverage provides priceless peace of mind, allowing you to focus on creating amazing dining experiences, confident that your business is protected.

