

Why Condo Renters Need Specialized Insurance Protection
Renters insurance for condos is different from a standard policy. Condo living creates unique coverage gaps, and many renters mistakenly believe their landlord’s insurance or the HOA’s master policy protects them. This is a major misconception.
Quick Answer: What You Need to Know
- Personal Property: Your belongings aren’t covered by anyone else’s policy.
- Interior Damage: You may be responsible for damage to walls, floors, and fixtures inside your unit.
- Liability Protection: Get coverage if someone is hurt in your rented condo.
- Loss Assessment: Protect yourself from HOA special assessments for building repairs.
- Loss of Use: Covers temporary living expenses if your unit becomes uninhabitable.
The reality is simple: you don’t own the building, but you need protection for everything inside your unit. Your policy picks up where the homeowners association’s (HOA) insurance leaves off. Condo renters face unique risks, like being responsible for interior walls, built-in appliances, or improvements. You could also face unexpected costs if the HOA levies special assessments for major building repairs.
I’m Jeffrey Joseph, and I’ve been helping Finger Lakes region residents steer complex insurance decisions since 1999 at Mitchell-Joseph Insurance Agency. Through decades of experience, I’ve seen how proper renters insurance for condos protects both your belongings and your financial future when unexpected events occur.
Renters insurance for condos terms you need:
Understanding Your Needs for Renters Insurance for Condos
Living in a condo means you’re part of a unique insurance puzzle. Renters insurance for condos isn’t just about covering your belongings—it’s about understanding how your personal coverage fits with your building’s insurance.
Think of it this way: your homeowners association (HOA) has its policy, and you have yours. Together, they create a complete shield. But the HOA’s policy doesn’t cover everything you might think, which is where your personal policy becomes essential.
This section breaks down the key components of condo insurance, explaining how it works with your HOA’s policy to protect you financially.
The Two-Policy System: Your Policy vs. The HOA’s Master Policy
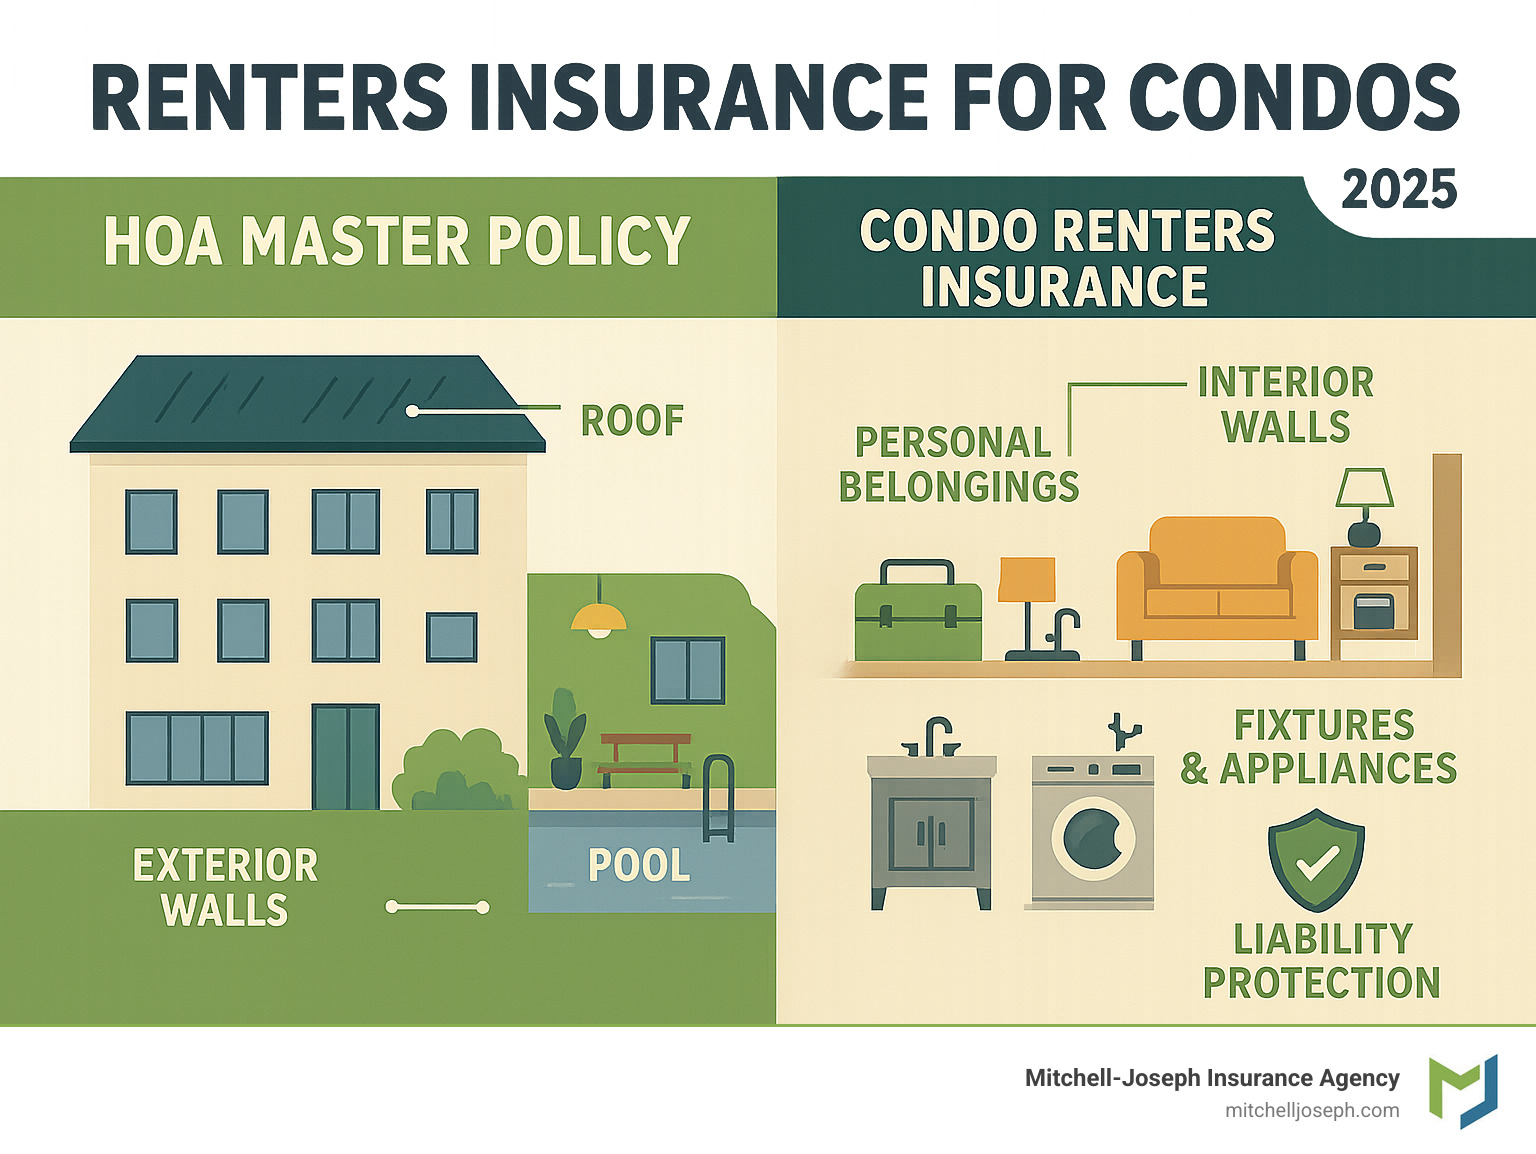
Many condo renters are surprised to learn their building’s insurance doesn’t cover what’s inside their unit. The HOA master policy acts like an umbrella over the building, protecting shared spaces and structural elements.
Your HOA’s master policy typically covers shared spaces like lobbies and fitness centers, the exterior walls, the roofs, and common areas like landscaping and parking lots.
Your renters insurance for condos steps in to cover the interior elements that make it home. Your personal policy covers the interior walls, the floors, and the fixtures like cabinets, countertops, and built-in appliances.
The key is knowing where one policy ends and the other begins. Your HOA’s bylaws spell out these details—it’s worth reading them to see what the association covers and what falls to you as a renter.
For a deeper dive into how this works in New York, check out our guide on Condominium Insurance in NY.
What Does Standard Renters Insurance for Condos Cover?
Now let’s talk about what your renters insurance for condos actually protects. It’s more comprehensive than you might expect.
Personal property coverage is what most people think of first. This protects your belongings—furniture, electronics, clothes—from events like fire, theft, and certain types of water damage. Pro tip: Ask for replacement cost coverage. It pays to replace lost items with new ones, unlike actual cash value coverage, which only pays their depreciated worth. For more details, visit our Personal Property Condo Insurance page.
Dwelling coverage is crucial even though you don’t own the unit. It covers the interior structure of your rented space—walls, floors, and ceilings. If a fire damages the inside of your unit, this coverage helps pay for repairs.
Personal liability protection is your safety net. If a guest is hurt in your unit or you accidentally damage a neighbor’s property (like from an overflowing tub), this coverage helps handle the medical bills or repair costs.
Loss of use coverage is a lifeline if your unit becomes uninhabitable. If a covered event like a fire forces you out, this coverage pays for temporary housing, meals, and other additional living expenses.
Medical payments to others is a smaller, “goodwill” coverage that pays for minor medical expenses if a guest is injured in your unit, regardless of fault.
Crucial Add-Ons: Loss Assessment and Customization
While standard renters insurance for condos is solid, customization allows us to tailor your policy to fit your specific situation.
Loss Assessment coverage is essential for condo renters. Sometimes, a major disaster exceeds the HOA’s insurance limits or involves a huge deductible. When this happens, the HOA can levy a special assessment on all unit owners to cover the shortfall. These assessments can be thousands of dollars per unit. Loss Assessment coverage helps pay your share of these unexpected expenses. Learn more at Condominium Loss Assessment Coverage.
Other valuable add-ons include water backup coverage for sewer or drain issues and identity theft protection. If you have pets, animal liability coverage protects you if your pet causes injury or damage. For high-value items like jewelry or art, special personal property coverage lets you insure them for their full appraised value.
Decoding Costs: Premiums, Deductibles, and Discounts
Understanding your insurance cost involves balancing your monthly premium with your deductible—the amount you pay out-of-pocket on a claim. The relationship is simple: a higher deductible usually means a lower premium, and vice versa.
High deductibles mean lower monthly payments but more out-of-pocket costs for a claim. This works well if you have a healthy emergency fund. Low deductibles mean higher premiums but less financial surprise if something goes wrong.
Several factors influence your premium, including your location, chosen coverage limits and add-ons, your building’s characteristics, and your personal claims history.
The good news is that many discounts can help. You may qualify for a claim-free discount, a discount for automatic sprinklers, or savings for bundling your condo renters and auto policies.
We work with you to find the right balance of coverage, deductibles, and discounts. For more insights, check out our guide How Much Is Renters Insurance?.
Securing Your Condo and Getting the Right Coverage
Finding the right renters insurance for condos doesn’t have to be a puzzle. With some planning and the right guidance, you can build a policy that fits your life perfectly, offering peace of mind and robust protection.
How to Determine Your Coverage Needs for Renters Insurance for Condos
Every condo renter’s situation is unique, so we craft your protection plan accordingly. Your lifestyle, belongings, and unit’s quirks all matter.
Start with your HOA bylaws. These documents are your roadmap, showing what’s already covered and what gaps you need to fill. This simple step prevents you from paying for duplicate coverage or, worse, finding a gap when it’s too late.
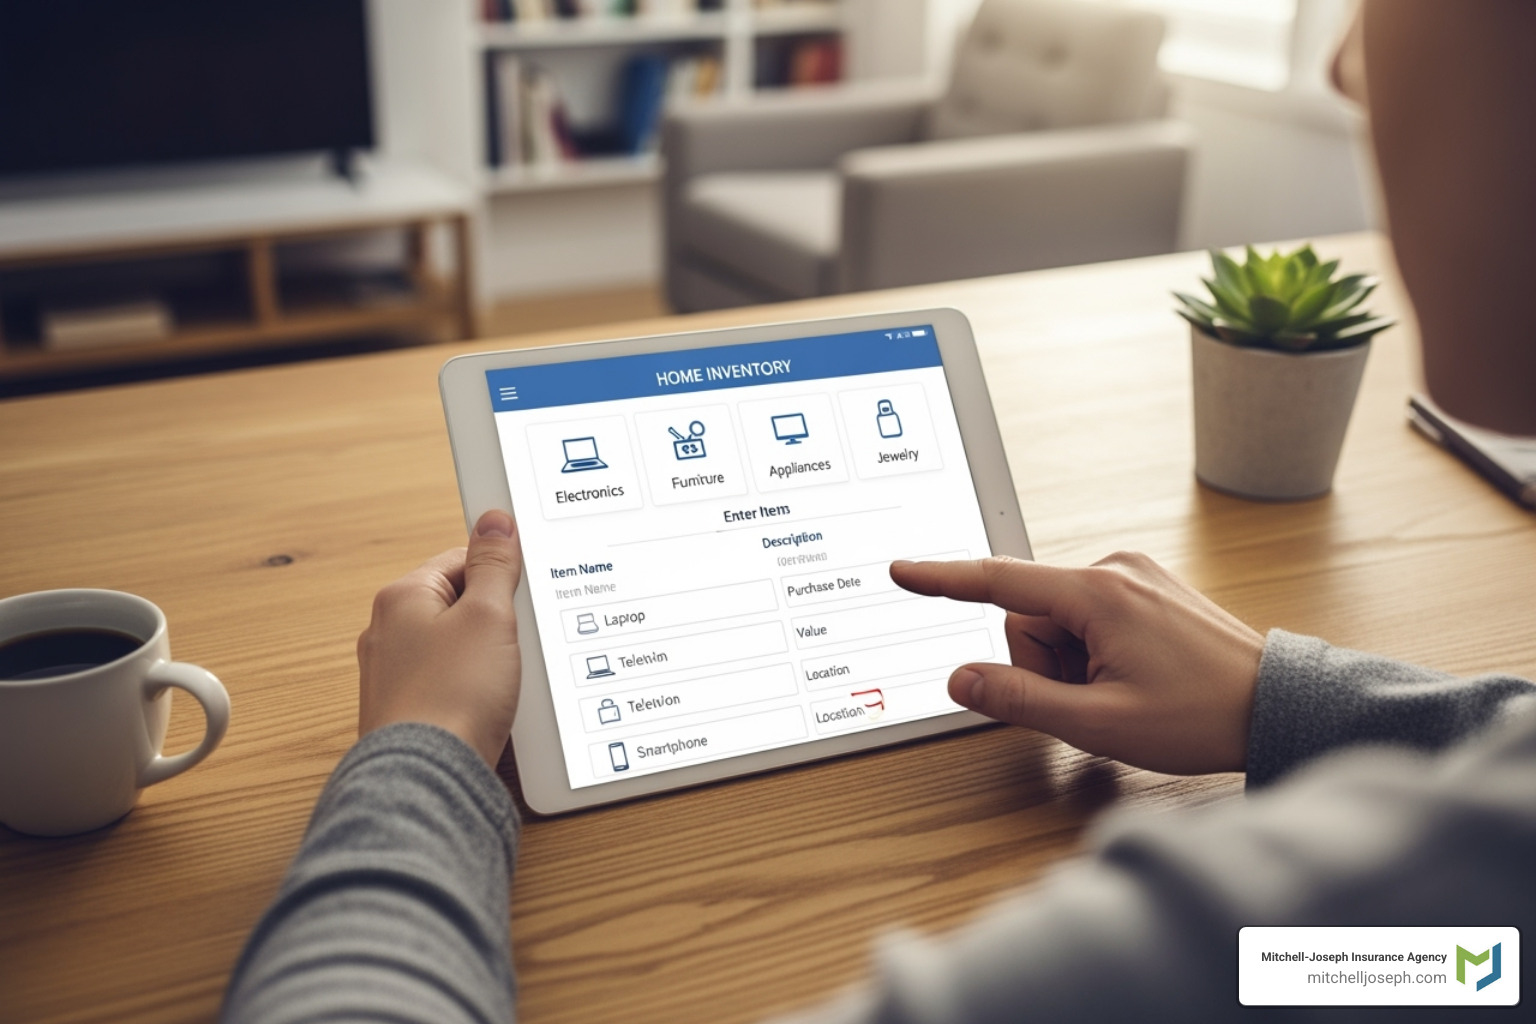
Creating a home inventory is one of the smartest things you can do. Walk through your condo, taking photos or videos of everything you own. Most people are shocked to find their belongings are worth tens of thousands of dollars. For help getting started, you can use a checklist like the one provided by the Insurance Information Institute.
Think about your liability risks. Do you host parties? Own a dog? Live on an upper floor? These scenarios help us determine the right amount of liability coverage for you.
Consider your temporary living needs. If a fire made your condo unlivable, your loss of use coverage becomes crucial for hotel or rental costs. We’ll help you think through realistic scenarios so you’re prepared.
Evaluate important add-ons like loss assessment or water backup coverage based on your specific situation. We’ll walk through each option and explain how it applies to you. For more answers, see our Renters Insurance FAQs.
Protect Your Investment and Get a Quote Today
Your condo is your sanctuary. The convenience of condo living shouldn’t come with financial anxiety. Comprehensive renters insurance for condos provides the security blanket that lets you truly enjoy your home.
At Mitchell-Joseph Insurance Agency, we’re a family-owned business with deep roots in the Finger Lakes community. We’ve helped neighbors from Honeoye Falls to Pittsford, Naples, and across Ontario, Monroe, Livingston, and Steuben Counties protect what matters most.
As an independent agency, we work for you, not the insurance companies. With access to 24 different insurers and over 200 years of combined experience, we shop around to find the best coverage at a competitive price—one that fits your needs perfectly.
We make the insurance process straightforward and stress-free with honest advice from local experts. Don’t wait until it’s too late. Protecting your belongings and financial future starts with a simple conversation.
Ready to get started? We make it easy.

