

Why Renters Insurance is an Essential Safety Net
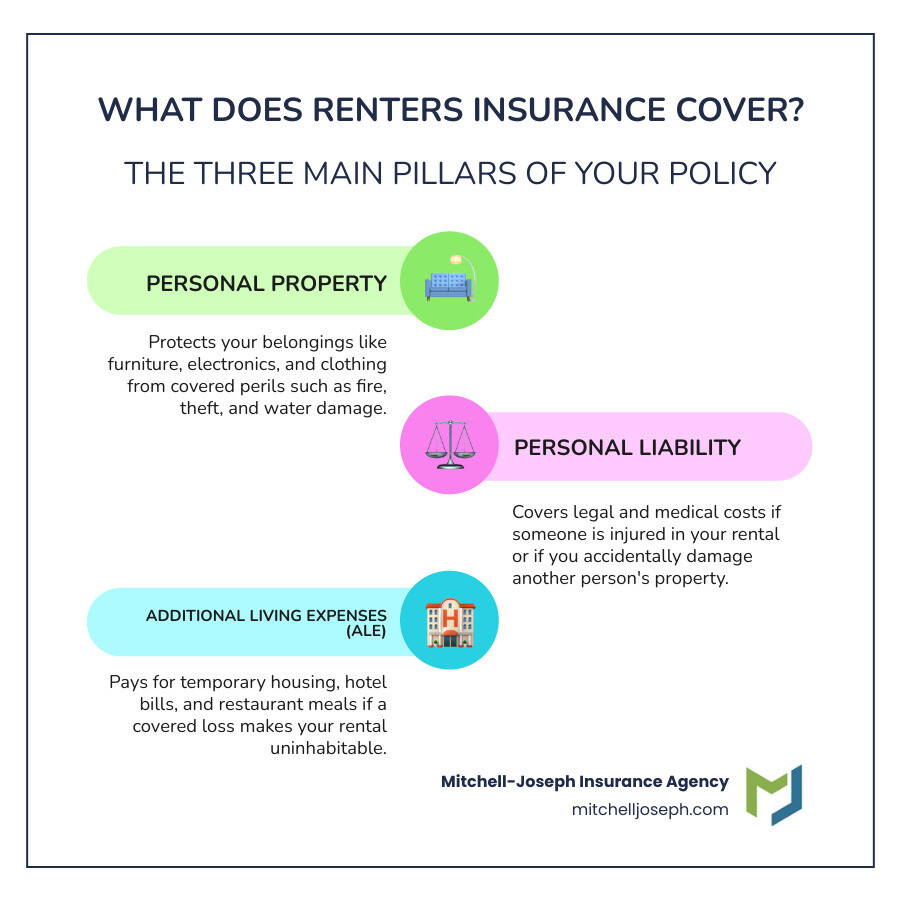
What does renters insurance cover? Renters insurance, also known as an HO-4 policy, provides a crucial financial safety net by typically covering three main areas:
- Personal Property: Protects your belongings (furniture, electronics, clothes) from events like fire, theft, and vandalism.
- Personal Liability: Covers legal and medical costs if someone is injured in your rental or you accidentally damage their property.
- Additional Living Expenses: Pays for temporary housing if a covered event makes your rental uninhabitable.
It’s a common misconception that a landlord’s insurance protects your belongings—it only covers the building itself. Without renters insurance, you are financially responsible for replacing your items after a fire or theft.
Fortunately, this protection is affordable. The average policy costs just $15 to $30 per month, a small price for peace of mind. This investment safeguards your possessions and protects you from potentially devastating liability costs.
I’m Jeffrey Joseph of Mitchell-Joseph Insurance Agency. Since 1999, our team has helped renters across the Finger Lakes region find the right coverage to protect their financial security at competitive rates.
Quick look at what does renters insurance cover:
What Does Renters Insurance Cover? A Breakdown of Your Policy
Understanding the different components of a renters insurance policy is key to ensuring you have the right protection. A standard policy is designed to shield you from financial loss due to various unforeseen events by covering personal property, liability, and additional living expenses. At Mitchell-Joseph Insurance Agency, we believe in empowering our clients with clear information so they can make informed decisions.
Personal Property: What does renters insurance cover for your belongings?
Personal property coverage protects the items you own within your rented space, from your couch and TV to your clothes and kitchenware. To ensure you’re properly covered, start by creating a home inventory—a list with photos or videos of your belongings. This makes filing a claim much easier.
Your items are protected against specific events listed in your policy, known as “named perils.” Common perils include:
- Fire or lightning
- Theft, vandalism, or riots
- Windstorm or hail
- Explosions
- Accidental water damage from plumbing or appliances
Coverage isn’t limited to your home. If your laptop is stolen from your car in Rochester, renters insurance can cover the loss (though off-premises coverage may have lower limits). However, be aware of “special limits” on high-value items like jewelry, firearms, and collectibles. A standard policy might only cover jewelry up to $1,500. To fully protect these valuables, you can add an “endorsement” or “floater” for their appraised value. You can find More info about collectibles insurance to see if this is right for you.
When you file a claim, you’ll be reimbursed based on one of two methods:
| Feature | Actual Cash Value (ACV) | Replacement Cost Value (RCV) |
|---|---|---|
| Definition | Pays for an item’s current value, including depreciation. | Pays the cost to buy a new, similar item without depreciation. |
| Payout Example | A 5-year-old TV might get you $300. | You’d get enough to buy a new, similar TV, perhaps $800. |
| Cost | Lower premiums. | Slightly higher premiums. |
We generally recommend Replacement Cost Value (RCV) coverage. While it costs a bit more, it ensures you can fully replace your belongings with new ones.
Liability and Medical Payments: Financial Protection from Accidents
Personal liability coverage is a critical part of what does renters insurance cover. It protects you financially if you’re found legally responsible for injuring someone or damaging their property. For example, if a guest trips and falls in your Pittsford apartment, or your overflowing tub damages a neighbor’s ceiling, this coverage can pay for:
- Bodily Injury: Medical bills, lost wages, and other costs for someone you injure.
- Property Damage: Repair or replacement costs for property you damage.
- Legal Defense: Costs to defend you in a lawsuit, even if the claim is baseless.
This protection often extends outside your home, like if your dog nips someone at the park. Most policies cover pet-related incidents, but some insurers exclude certain breeds. It’s important to discuss your pets with us to ensure you’re covered. Renters insurance does not cover your own pet’s vet bills; that requires a separate pet insurance policy.
Your policy also includes Medical Payments to Others. This is a no-fault coverage that pays for minor medical expenses (typically $1,000 to $5,000) for a guest injured on your property, regardless of who is at fault. It’s a goodwill feature that can prevent small accidents from becoming large lawsuits.
Liability limits often start at $100,000, but we recommend choosing a limit that protects your assets. Your policy can also cover damage you accidentally cause to the rental property itself, such as from a fire or explosion.
Additional Living Expenses (ALE): Covering Costs When You’re Displaced
If a covered event like a fire or burst pipe makes your rental in Honeoye uninhabitable, Additional Living Expenses (ALE) coverage comes to the rescue. Also known as “Loss of Use,” this part of what does renters insurance cover pays for the increase in your living expenses while your home is being repaired.
ALE helps cover necessary additional costs such as:
- Temporary housing (hotel or another rental)
- Restaurant meals if you can’t cook
- Laundry services and storage costs
This coverage is subject to policy limits, which can be a set time period (e.g., 12 months) or a dollar amount (e.g., 20% of your personal property coverage). It provides invaluable peace of mind, ensuring you have a place to stay and can maintain your standard of living during a stressful time. In some cases, it may even apply if a civil authority prevents you from accessing your home due to damage to a neighboring property.
Key Exclusions, Costs, and How to Get the Right Coverage
While renters insurance is comprehensive, it’s important to know what it doesn’t cover. At Mitchell-Joseph Insurance Agency, we’ll help you understand policy exclusions, cost factors, and how to customize your coverage in communities like Victor or Avon. We’ll also guide you through the claims process.
Exclusions: What does renters insurance not cover?
Understanding what your policy excludes is as important as knowing what it covers. A standard policy is for your personal belongings and liability, not the building structure itself—that’s your landlord’s responsibility.
Common exclusions include:
- Flood Damage: Damage from overflowing rivers or heavy rainfall is not covered. Separate flood insurance is required, available through the National Flood Insurance Program.
- Earthquake Damage: Like floods, this requires a separate policy or endorsement.
- Pest Infestations: Damage from bedbugs, rodents, or termites is considered a maintenance issue and is not covered.
- Mold: Mold is typically excluded, unless it’s the direct result of a covered peril, like a sudden pipe burst.
- Roommate’s Property: Your policy only covers your belongings. Each roommate needs their own policy.
- Intentional Damage: Insurance does not cover damage you cause on purpose.
- Vehicle Damage: While items stolen from your car are covered, damage to or theft of the car itself falls under your auto insurance.
- Wear and Tear/Neglect: Gradual deterioration or damage from poor maintenance is not covered.
Understanding the Cost and Customizing Your Coverage
Renters insurance is highly affordable, with average premiums between $15 and $30 per month. Your specific cost depends on several factors:
- Coverage Amount: Higher limits for personal property and liability increase the premium.
- Deductible: A higher deductible (the amount you pay out-of-pocket on a claim) lowers your premium.
- Location: Local factors like theft rates in your area can affect cost.
- Claims History: A history of claims can lead to higher rates.
- Security Features: Discounts may be available for smoke alarms, deadbolts, or security systems.
Customizing Your Coverage with Endorsements:
You can improve what does renters insurance cover by adding optional “endorsements” or “riders” for extra protection. Common options include:
- Scheduled Personal Property: Provides specific, appraised-value coverage for high-value items like jewelry, art, or collectibles.
- Water Backup Coverage: Covers damage from backed-up sewers or drains, which is often excluded from standard policies.
- Identity Theft Protection: Helps cover costs associated with recovering from identity theft.
- Business Property Coverage: Increases coverage for equipment if you run a home-based business.
At Mitchell-Joseph Insurance Agency, we’ll help you steer these options and find discounts, like bundling your renters and auto insurance. We work with 24 insurance companies to find a policy custom to your life in Mendon, Rushville, or any of our neighboring communities.
Next Steps: Filing a Claim and Getting Covered
If you need to file a claim, our team at Mitchell-Joseph Insurance Agency is here to help. Follow these general steps:
- Ensure Safety: Address any immediate hazards and evacuate if necessary.
- Notify Your Landlord: Inform your landlord of any damage to the property.
- File a Police Report: For theft or vandalism, get a police report number for your claim.
- Document the Damage: Take photos and videos of all damaged items before cleaning up.
- Contact Us: Notify your insurance agent as soon as possible to start the claim process.
- Keep Receipts: Save all receipts for additional living expenses if you have to relocate temporarily.
What about property in storage units? Yes, your policy typically covers items in storage, but coverage is often limited to a percentage of your total personal property limit (e.g., 10%). Check your policy for specifics.
Can a dependent be covered under their parents’ homeowners policy? Sometimes. A student living in a dorm may have limited coverage under their parents’ policy. However, if you live in an off-campus apartment, you will likely need your own renters insurance policy. It’s always best to confirm with the insurer.
At Mitchell-Joseph Insurance Agency, we’re your neighbors. With over 200 years of combined experience, our independent, family-owned business understands the needs of clients across Honeoye Falls, Pittsford, and the wider Finger Lakes region. We offer personalized service and competitive quotes to ensure you get the right coverage.
Don’t wait for the unexpected. Protect your belongings and financial future today.
Get a renters insurance quote from Mitchell-Joseph Insurance Agency today!

