

Why Every Renter Needs to Understand Insurance Costs
The rental insurance coverage cost averages about $14 per month (or $166 per year) across the United States, making it one of the most affordable types of insurance you can buy. If you’re renting in upstate New York, it’s a small price for crucial financial protection.
Many renters mistakenly believe their landlord’s insurance covers their personal items. It doesn’t. The landlord’s policy protects the building itself, leaving your belongings and personal liability unprotected. A fire, theft, or accident could cost you thousands out of pocket without your own policy.
I’m Jeffrey Joseph, and since 1999, I’ve helped renters across the Finger Lakes region secure affordable, effective coverage. At Mitchell-Joseph Insurance Agency, we’ve seen how a small monthly premium can prevent devastating financial loss.
What Does Standard Renters Insurance Cover?
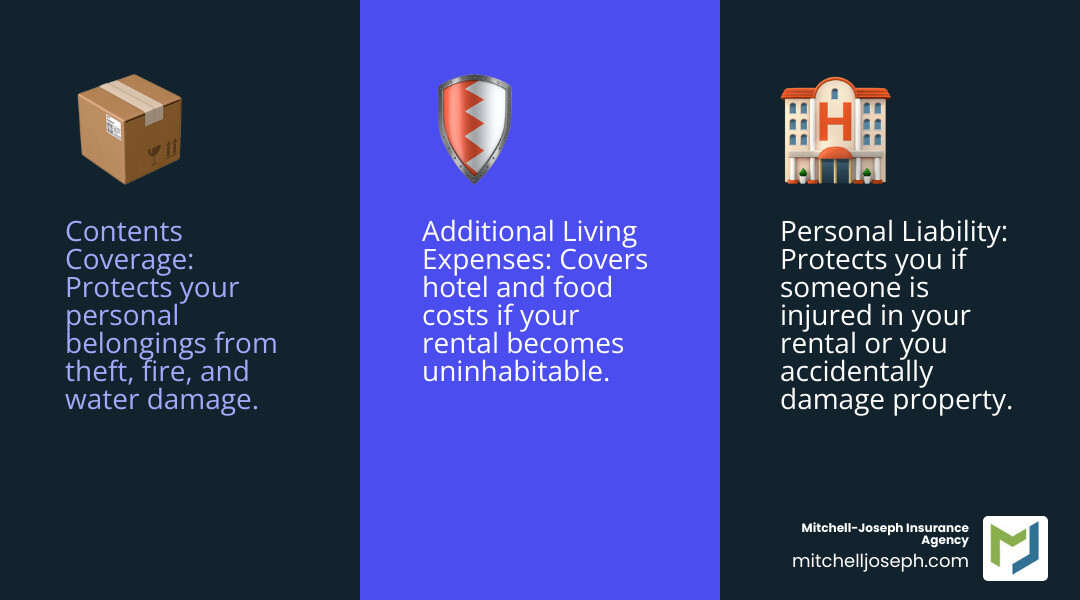
A standard policy, also known as tenant insurance, is built on three pillars of protection:
- Contents Coverage: Protects your personal belongings—furniture, electronics, clothes—from events like fire, theft, and certain types of water damage. This coverage can even apply to items temporarily outside your home, like luggage stolen during travel.
- Personal Liability Coverage: Shields you financially if you’re found responsible for injuring someone or damaging their property. This could cover medical bills if a guest falls in your apartment or repair costs if you accidentally cause a fire that damages a neighbor’s unit.
- Additional Living Expenses (ALE): Covers extra costs like hotel stays and meals if your rental becomes uninhabitable due to a covered event, such as a fire or major water damage.
While renters insurance isn’t legally required in New York, many landlords mandate it in the lease. Regardless, it’s a wise investment for your financial security. For more details on what a policy includes, you can explore our resources on Apartment Insurance.
What Isn’t Covered?
It’s also important to know what a standard policy typically excludes:
- The Building Structure: This is covered by your landlord’s insurance.
- Flooding & Earthquakes: Damage from natural floods (like overflowing rivers) and earthquakes usually requires separate coverage or a special endorsement.
- Pest Infestations: Damage from rodents or insects is generally not covered.
- Roommates’ Property: Your policy only covers your belongings unless your roommate is specifically named on it. It’s best for each roommate to have their own policy.
- High-Value Items: Expensive jewelry, art, or collectibles often have limited coverage. You may need a special endorsement, or “rider,” to insure them for their full value.
For a deeper dive into what renters insurance entails, the National Association of Insurance Commissioners (NAIC) Consumer Resources offers valuable resources for consumers. You can also learn more about specific coverage for condos on our Renters Insurance for Condos page.
The Core of Rental Insurance Coverage Cost
Your rental insurance coverage cost is based on a few key choices you make. The national average is around $14 per month, but your final price depends on factors like your location, coverage limits, and deductible. Understanding these elements allows you to build a policy that balances strong protection with a budget-friendly price.
The two biggest decisions you’ll make are choosing your coverage limits and your deductible. Another crucial choice is between replacement cost and actual cash value coverage. Replacement cost pays to buy a new item, while actual cash value pays what your item was worth after depreciation. The premium difference is small, but the payout difference can be huge, which is why we almost always recommend replacement cost coverage. Learn more in our guide on How Much Is Renters Insurance?.
Key Factors Influencing Your Rental Insurance Coverage Cost
Insurers assess several risk factors to determine your premium. Key influences include:
- Location: Your ZIP code matters. Rates are affected by local factors like theft statistics and proximity to a fire station.
- Coverage Limits: Higher limits for your personal property or liability mean a higher premium.
- Deductible: A higher deductible lowers your premium because you agree to pay more out-of-pocket for a claim.
- Credit-Based Insurance Score: In many states, including New York, a better credit history can lead to lower rates.
- Claims History: A history of frequent claims can increase your premium.
- Building Characteristics: The age and construction of your building can impact risk and, therefore, your cost.
- Pets: Certain dog breeds may increase your liability premium.
We help clients in Honeoye Falls, Avon, and Naples steer these factors to find the best rates. For more on typical costs, visit our Average Cost of Renters Insurance page.
Understanding Your Coverage Choices
When building your policy, you’ll make these key decisions:
- Contents Coverage Limit: Estimate the value of your belongings to choose a limit (e.g., $25,000, $50,000). A home inventory can help you get an accurate number.
- Liability Limit: This protects your assets if you’re sued. We strongly recommend a limit of at least $1 million, as the cost to increase it from a basic $100,000 limit is typically just a few dollars a month.
- Deductible: Choose an amount you can comfortably pay in an emergency, typically $500 or $1,000. A higher deductible means a lower monthly bill.
- Optional Endorsements: You can add extra protection for specific risks, such as sewer backup, identity theft, or scheduled personal property for high-value items like engagement rings.
How to Get a Quote and Manage Your Policy
Getting a quote is simple. Start by gathering basic information: your rental address, an estimate of your property’s value, and your desired liability limit and deductible.
You can get quotes online, but working with an independent agency like ours allows you to compare options from multiple carriers at once to find the best value. After you purchase a policy, you can usually manage it through an online portal to update information or make changes. If you move or get a roommate, be sure to contact us to update your policy and ensure you remain properly covered. For answers to common questions, see our Renters Insurance FAQs.
Smart Strategies to Save and Secure Your Coverage

Even though the rental insurance coverage cost is affordable, you still want the best value. There are plenty of straightforward ways to reduce your premium without sacrificing protection. At Mitchell-Joseph Insurance Agency, we help renters in Honeoye Falls, Rochester, and across the Finger Lakes find coverage that fits their budget.
Proven Ways to Lower Your Insurance Bill
Here are some effective strategies to lower your premium:
- Bundle Your Policies: Combining your renters and auto insurance with the same company is one of the easiest ways to get a significant discount.
- Choose a Higher Deductible: Opting for a $1,000 deductible instead of $500 will lower your monthly cost. Just be sure you can afford to pay that amount if you file a claim.
- Install Safety Devices: Discounts are often available for smoke detectors, deadbolt locks, and monitored security systems.
- Maintain a Good Claims History: Insurers may reward you with lower rates for being claims-free over several years.
- Shop Around: As an independent agency, we compare rates from 24 different insurance companies to find you the best deal, saving you time and money.
- Pay Annually: If your budget allows, paying your premium in one annual lump sum can often earn you a small discount compared to paying monthly.
- Improve Your Credit Score: A strong credit history can positively impact your insurance score, leading to a lower rental insurance coverage cost.
Navigating the Claims Process
If you need to file a claim, being prepared can make the process smoother.
- Ensure Safety First: In an emergency like a fire, evacuate immediately and call 911. Your safety is the top priority.
- Contact Your Insurer Promptly: Report the incident to your insurance provider as soon as possible. Most have 24/7 claims hotlines.
- Document Everything: Before cleaning up, take extensive photos and videos of the damage. Make a list of all lost or damaged items.
- Prevent Further Damage: Take reasonable steps to secure your property, like covering a broken window. Keep receipts for any temporary repairs.
- Work with the Adjuster: An adjuster will be assigned to your claim. Cooperate with them and provide any requested information.
- Understand Your Settlement: Your settlement will be for the covered damages minus your deductible. Review the offer carefully and ask questions if anything is unclear.
For more details, visit our Payments & Claims page.
Find the Right Protection for Your NY Rental
At Mitchell-Joseph Insurance Agency, we believe in providing personalized service. As a family-owned independent agency in Honeoye Falls, we’re dedicated to serving our neighbors throughout the Finger Lakes region. Because we work with 24 different insurance companies, we shop the market on your behalf to find the right coverage at a competitive price.
We’ll take the time to explain your options in plain English, ensuring you get a policy that provides real peace of mind. Ready to protect your rental and your belongings? Get Your Personalized Renters Insurance Quote today.
Smart Strategies to Save and Secure Your Coverage
While the rental insurance coverage cost is already one of the most affordable insurance investments you can make, we know every dollar matters. The good news? There are several practical ways to reduce your premium even further without giving up the protection you need. At Mitchell-Joseph Insurance Agency, we’ve helped hundreds of renters across Honeoye Falls, Rochester, and the surrounding areas find smart savings on their policies.
Proven Ways to Lower Your Insurance Bill
Keep your rental insurance coverage cost as low as possible with these strategies:
- Bundle Policies: Combine your auto and renters insurance for significant savings.
- Adjust Your Deductible: A higher deductible (e.g., $1,000) lowers your monthly premium.
- Use Safety Discounts: Get credit for smoke detectors, security alarms, and deadbolt locks.
- Stay Claims-Free: A clean record can earn you loyalty discounts over time.
- Shop Around: As an independent agency working with 24 carriers, we find the best rates for you.
- Pay Annually: Paying your premium in one lump sum can reduce the total cost.
- Maintain Good Credit: A strong credit history can lead to lower insurance rates in New York.
- Review Your Policy Yearly: Ensure your coverage matches your current needs to avoid overpaying.
Navigating the Claims Process
If you need to file a claim, follow these steps for a smoother experience:
- Prioritize Safety: In an emergency, get to safety and call 911.
- Report the Claim: Contact your insurer as soon as possible via their 24/7 claim line or app.
- Document the Loss: Take detailed photos and videos of all damage before cleaning up. Create an inventory of lost or stolen items.
- Mitigate Further Damage: Make temporary repairs to prevent the situation from worsening and keep receipts.
- Work with the Adjuster: Cooperate with the insurance adjuster assigned to your case.
- Review Your Settlement: Understand your settlement offer, which will be for covered losses minus your deductible.
For more details about the claims process, visit our Payments & Claims page.
Find the Right Protection for Your NY Rental
Finding the right insurance doesn’t have to be complicated. At Mitchell-Joseph Insurance Agency, we are an independent, family-owned business with deep roots in upstate New York. We work for you, not one single insurance company. By partnering with 24 different insurance companies, we shop the market to find the best combination of coverage and price for your unique situation.
We serve renters across the Finger Lakes region, from Rochester to Honeoye Falls and beyond. Let us help you find affordable, comprehensive renters insurance that gives you real peace of mind.
Ready to see your options? Get Your Personalized Renters Insurance Quote today.

