

Protecting Your Investment: Understanding Propertty Damange Insurance Condominium NY
Owning a condominium in New York offers a unique lifestyle. But it also comes with specific insurance needs. Understanding propertty damange insurance condominium ny is crucial to protect your home and finances.
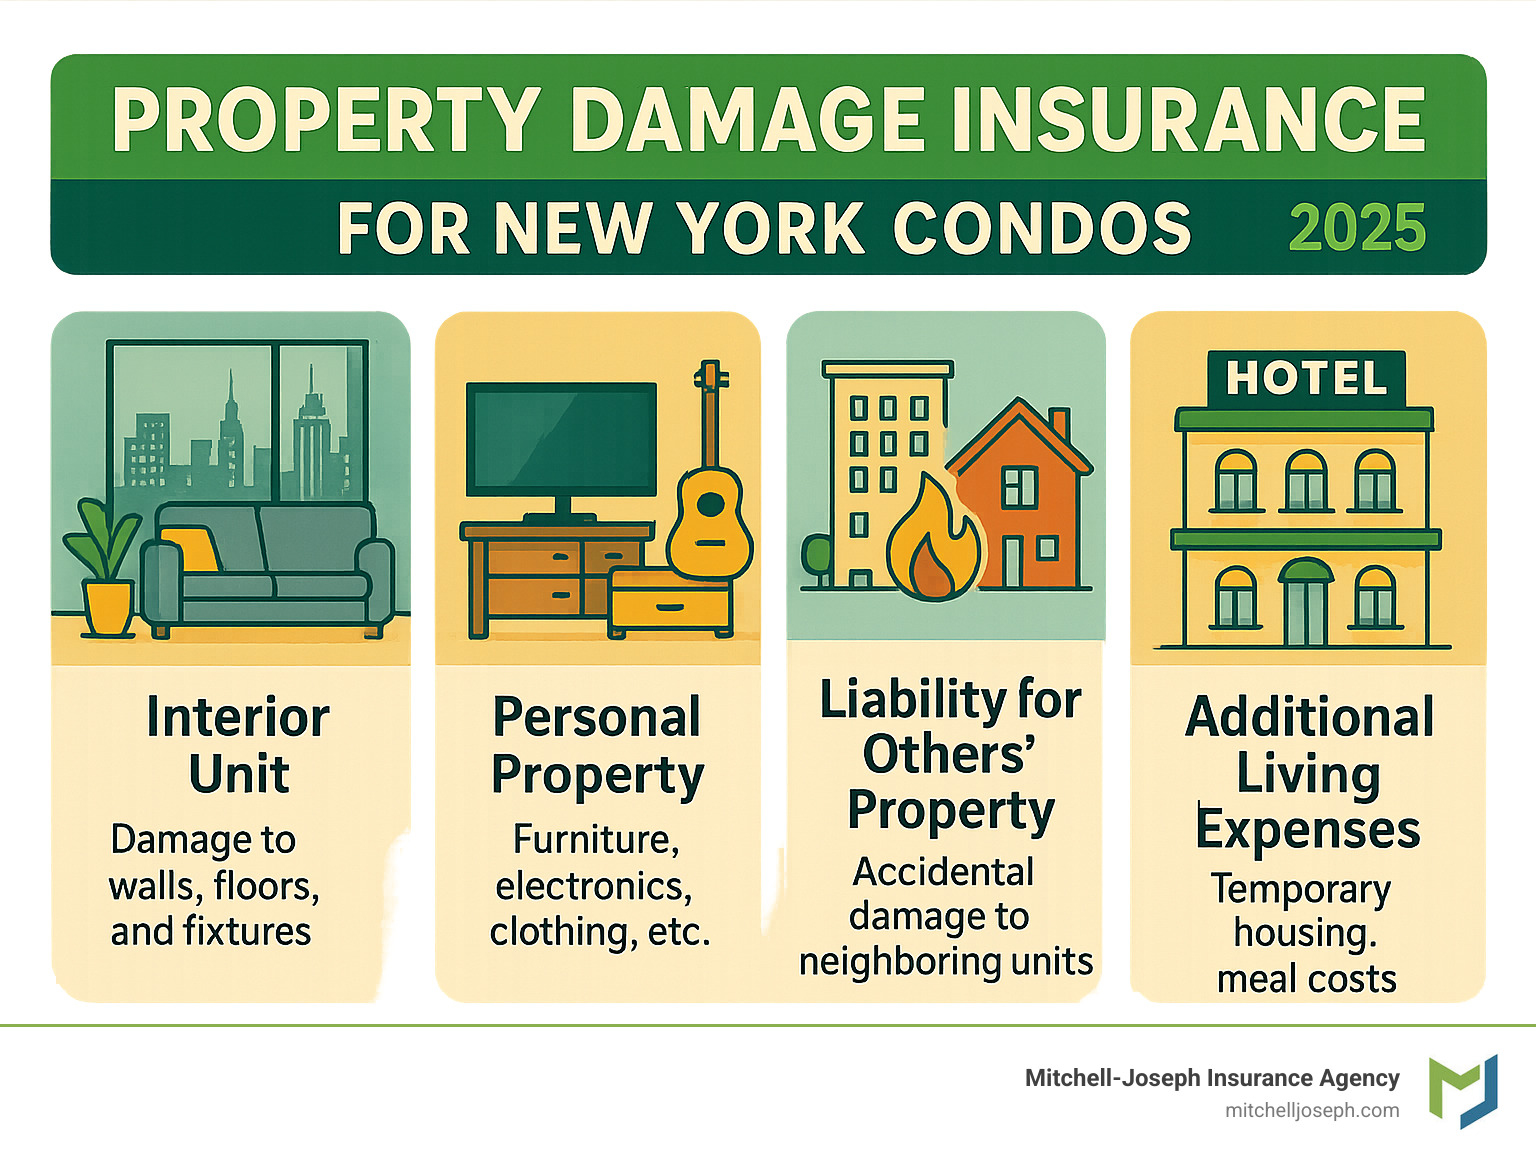
Here’s a quick look at what property damage insurance for your New York condo typically covers:
- Your Unit’s Interior: This includes damage to internal structures like walls, floors, ceilings, and built-in appliances from covered incidents.
- Your Personal Belongings: Your furniture, electronics, clothes, and other personal items are protected against perils like fire, theft, or vandalism.
- Liability for Damage to Others: If you accidentally cause damage to a neighbor’s unit or a common area, your policy can help cover the repair costs.
- Additional Living Expenses: Should your condo become unlivable due to covered damage, your insurance can assist with temporary housing and meal costs.
As Jeffrey Joseph, I’ve dedicated over two decades to helping New York condo owners steer the complexities of propertty damange insurance condominium ny. My goal at Mitchell-Joseph Insurance Agency is to ensure you have the precise protection you need, offering clear answers and custom solutions. Let’s explore the details.
What is Condo Insurance (HO-6) and How Does It Work in New York?
When you own a condo in New York, your insurance needs differ from those of a traditional homeowner. An HO-6 policy is insurance designed specifically for condo and co-op owners. While your condo association’s master policy covers the building’s exterior and common areas, your HO-6 policy provides “walls-in” coverage.
This policy protects your personal property, provides personal liability coverage, and safeguards the structural parts within your unit, from the drywall and flooring to your custom finishes. It fills the crucial gap left by the master policy, ensuring your personal living space and investment are protected. For this reason, most mortgage lenders require you to have an HO-6 policy.
For even more details on how we can help protect your condominium, explore our page on Insurance for Condominium Owners.
Your Unit’s Interior Structure (Dwelling Coverage)

Any improvements you’ve made to your New York condo, from renovated kitchens and hardwood floors to custom cabinets and upgraded fixtures, represent your personal investment. Your HO-6 policy’s dwelling coverage is designed to protect these elements.
This coverage includes the interior surfaces of your walls, ceilings, and floors, as well as built-in items like appliances and cabinetry. Since a condo association’s master policy often doesn’t cover upgrades beyond the original builder-grade finishes, your HO-6 dwelling coverage is essential. If a burst pipe damages your custom kitchen, this policy helps with repair or replacement costs, protecting the space that is uniquely yours.
We can help you understand the details of this coverage. For a broader look at how we can cover your home, visit our Home Insurance Coverage page.
Your Personal Belongings
Your condo is filled with personal belongings: furniture, electronics, clothing, and artwork. An HO-6 policy provides coverage for these items against perils like fire, theft, or vandalism.
Creating a detailed inventory of your possessions, perhaps with photos or video, is a smart way to ensure you have enough coverage. This can help you realize the total value of your belongings. Your personal property coverage may even extend to items temporarily stored outside your unit, such as in a storage locker or while you travel. We can help you determine the value of your possessions and select the right amount of coverage to protect them.
Find out more about protecting your valuables on our Personal Property Condo Insurance page.
Your Personal Liability
Accidents happen, and your personal liability coverage is a crucial safety net. It protects you financially if you’re found responsible for causing bodily injury to someone or damage to their property. For instance, if a guest slips and falls in your condo, or an overflowing bathtub causes water damage to the unit below, your liability coverage can help with medical bills, repair costs, and legal fees.
Interestingly, New York has the highest average cost per dog bite claim. If your pet accidentally injures a visitor, your liability coverage can step in to help, protecting you from significant financial burdens. For even greater protection, consider an umbrella policy. Learn more about comprehensive liability protection on our Umbrella Insurance Coverage page.
What Propertty Damange Insurance Condominium NY Actually Covers
Let’s clarify what your propertty damange insurance condominium ny is designed to cover. An HO-6 policy is typically a “named-peril” policy, meaning it protects you from a specific list of events, or “perils.” If a peril isn’t listed, it generally isn’t covered.

Typical covered perils include:
- Fire and Lightning: Foundational coverage for damage from fire or lightning strikes.
- Windstorm and Hail: Protects your condo’s interior from damage caused by strong winds or hail.
- Theft and Vandalism: Covers the cost to repair or replace belongings if your unit is burglarized or vandalized.
- Accidental Water Discharge: Crucial for condo living, this covers sudden and accidental damage from internal sources like a burst pipe or overflowing appliance. This is for water from your unit’s systems, not from outside flooding.
Common Exclusions from propertty damange insurance condominium ny
It’s equally important to understand what your HO-6 policy doesn’t cover. Knowing these common exclusions helps identify and address potential gaps in your protection.
- Flood Damage: Standard condo policies do not cover damage from external water sources like heavy rains or storm surges. A separate flood insurance policy is needed for this. For more information, visit our Flood Insurance Coverage page.
- Earthquake Damage: Damage from earthquakes requires a separate policy or endorsement.
- Sewer and Water Backup: Damage from water backing up through sewers or drains is typically excluded without a specific endorsement.
- Wear and Tear: Insurance is for sudden and accidental events, not for gradual deterioration or items breaking down over time.
- Lack of Maintenance: Damage resulting from a failure to perform necessary maintenance (e.g., ignoring a known leak) may not be covered.
Optional Coverages for Improved Protection
Understanding exclusions allows us to build a stronger policy for your propertty damange insurance condominium ny. Optional coverages, or endorsements, can fill these gaps for greater peace of mind.
One of the most critical endorsements is Water Backup Coverage. Since standard policies exclude this, and plumbing systems in condo buildings are interconnected, this coverage is invaluable. It protects your property if water backs up from a sewer or drain. You can learn more on our What is Water Backup Coverage on Homeowners Insurance? page.
Other smart additions include Service Line Coverage for utility lines running to your unit and Loss Assessment Coverage, which we’ll discuss next. For high-value items like fine jewelry or art that exceed standard policy limits, High-Value Item Riders (Scheduled Personal Property) provide coverage for their full appraised value.
Your Policy vs. The Association’s Master Policy
Understanding the interplay between your HO-6 policy and your condo association’s master policy is key. The two policies work together, each with a specific role. The master policy covers the building’s “bones” and shared spaces, while your HO-6 policy covers your “personal bubble” inside.
This partnership ensures complete protection, but you must know where one policy’s coverage ends and the other’s begins.
| Feature | Your HO-6 Policy | Association’s Master Policy |
|---|---|---|
| Coverage Focus | Interior of your unit, personal belongings, liability within your unit | Building structure, common areas, exterior walls, roof, shared systems |
| Examples Covered | Your kitchen cabinets, flooring, personal furniture, guest’s injury in your unit | Lobby, hallways, gym, pool, elevators, exterior siding, building’s plumbing system |
| Deductible | Your individual deductible for your claims | Association’s deductible for common area claims |
If a storm damages the building’s roof, the master policy handles repairs. But if that damage causes a leak that ruins your interior walls and furniture, your HO-6 policy steps in. The best way to clarify these responsibilities is by reviewing your condo bylaws and declarations. At Mitchell-Joseph Insurance Agency, we help New York clients decipher these documents to ensure their individual policy aligns perfectly with the master policy.
Understanding the Master Policy: “Bare Walls” vs. “All-In”
The type of master policy your association holds directly impacts your personal coverage needs.
- “Bare Walls” Coverage: This is the most basic type, covering only the building’s structure and common areas. It does not cover anything inside your unit, including drywall or fixtures. With this policy, your HO-6 dwelling coverage must be robust enough to cover everything from the studs inward.
- “Single Entity” Coverage: This covers the building, common areas, and the original fixtures in your unit (e.g., builder-grade cabinets and flooring). It does not cover any upgrades or renovations you’ve made.
- “All-In” Coverage: This is the most comprehensive master policy, covering the structure, common areas, and all fixtures and improvements within your unit, even those made by previous owners. Your HO-6 dwelling coverage needs are significantly lower with an all-in policy.
We can help you determine your association’s policy type to ensure your personal coverage fills any gaps. For associations seeking coverage, we offer specialized solutions on our Insurance for Condo Associations page.
What is Loss Assessment Coverage?
Loss assessment coverage is one of the most vital yet misunderstood parts of propertty damange insurance condominium ny. Imagine a storm causes $500,000 in damage to common areas, but the association’s master policy has a $400,000 limit. The association would levy a “special assessment” on all unit owners to cover the $100,000 shortfall.
Without loss assessment coverage, you would have to pay your share out of pocket. This coverage reimburses you for these assessments, up to your policy limit, protecting you from the unexpected shared costs of community living.
This coverage typically applies to assessments for property damage to common areas or liability claims against the association. It generally does not cover assessments for routine maintenance or improvements not related to a covered loss. We can help you determine the right amount of loss assessment coverage for your needs. For more information, visit our Home Insurance Coverage page.
Calculating Costs and Coverage Amounts in New York
Fortunately, propertty damange insurance condominium ny is generally more affordable than standard homeowners insurance because you aren’t insuring the entire building. In New York, condo insurance averages around $656 per year (about $55 a month), with some rates as low as $289 per year.
However, your exact premium depends on several factors. Your location is a major one; a condo in a high-density NYC ZIP code like 10021 will likely have different rates than one in East Rochester (14445). Other key factors include your chosen coverage limits, your deductible (the amount you pay before insurance kicks in), your claims history, and any safety features like smoke detectors or burglar alarms.
How much propertty damange insurance condominium ny do you need?
Determining the right amount of coverage is a personalized process. Here’s what to consider:
- Personal Property Valuation: A home inventory will help you calculate the value of your belongings. We can help you decide between Replacement Cost coverage (pays to buy new items) and Actual Cash Value (pays based on depreciated value). Most owners prefer Replacement Cost.
- Estimating Rebuilding Costs: This depends on your association’s master policy. If it’s “bare walls,” you’ll need enough dwelling coverage to rebuild your unit’s interior from the studs inward. We’ll help you account for materials, labor, and custom finishes.
- Liability Protection: A minimum of $100,000 is standard, but in New York, we often recommend $300,000 to $1 million. Increasing liability coverage is typically very affordable.
- Loss Assessment Coverage: We’ll help you review your association’s bylaws to determine the potential assessment they could levy, ensuring you have adequate protection.
Consulting an expert is the best way to assess your needs. At Mitchell-Joseph Insurance Agency, we ensure you have the right coverage without overpaying. For more details, especially for those in the Rochester area, see our Property Insurance Rochester NY page.
Available Discounts to Lower Your Premium
We can help you find several discounts to lower your propertty damange insurance condominium ny premium without sacrificing protection.
- Multi-policy bundles: Combining your condo and auto insurance is often the biggest saver.
- Home safety devices: Discounts are available for smoke detectors, fire extinguishers, and security systems.
- Claims-free history: A clean record for 3-5 years can earn you a discount.
- Building features: A doorman, secured access, or an on-site manager can lead to savings.
- Other discounts: Being a non-smoker or paying your premium on time can also help.
Bundling your auto policy is a great way to save, and taking a NY Defensive Driving Course for potential auto discounts can further reduce your overall insurance costs.
Frequently Asked Questions about NY Condo Property Damage Insurance
Insurance can be complex, so it’s natural to have questions. Here are some common queries we receive about propertty damange insurance condominium ny, with straightforward answers.
What are the first steps to take after my NY condo sustains property damage?
When damage occurs, acting quickly can streamline your claim. Follow these steps:
- Prioritize Safety: Ensure everyone is safe. If there are electrical or structural hazards, evacuate immediately and call for emergency services if necessary.
- Prevent Further Damage: Take reasonable steps to mitigate the damage, like turning off a water main or covering a broken window. Keep receipts for any temporary repairs.
- Document Everything: Before cleaning up, take extensive photos and videos of all damaged property and areas.
- Contact Your Condo Association: Notify them immediately, as the master policy may be involved, especially if common areas are affected.
- Call Us: Contact Mitchell-Joseph Insurance Agency as soon as possible. We will guide you through the claims process and act as your advocate.
- Keep Damaged Property: Do not dispose of damaged items until your claims adjuster has inspected them.
- Maintain Records: Keep a log of all communications, including dates, names, and discussion details, along with copies of all estimates and receipts.
Is condo insurance required by law in New York?
While New York State does not legally mandate that every condo owner carry an HO-6 policy, it is almost always a practical requirement. Most mortgage lenders will require it to protect their investment. Furthermore, nearly all condominium association bylaws obligate unit owners to maintain individual insurance to protect the financial stability of the entire community.
How does the claims process work for condo damage?
We’re here to make the claims process as smooth as possible. Here is a general overview:
- Report the Claim: You’ll report the damage to us at Mitchell-Joseph Insurance Agency, and we’ll help you submit the claim to your carrier.
- Adjuster Assignment: The insurance company assigns a claims adjuster to your case, who will schedule an inspection.
- Damage Assessment: The adjuster inspects the damage, reviews your documentation (photos, receipts), and may request contractor estimates.
- Policy Review: The adjuster reviews your HO-6 policy and coordinates with the condo association’s master policy to determine what each policy covers.
- Settlement Offer: Based on the assessment and your policy, the insurer makes a settlement offer, minus your deductible.
- Repairs: Once you accept the offer, you can proceed with repairs. Our role is to be your advocate throughout this process, ensuring you receive a fair settlement.
Get the Right Condo Protection for Your New York Home
Owning a New York condo is an exciting venture, and the right insurance brings peace of mind. A well-crafted propertty damange insurance condominium ny policy is more than a requirement—it’s a safety net for your investment, your belongings, and your financial future.
Your HO-6 policy must protect your interior structure and personal belongings while shielding you from shared ownership risks like special assessments and liability claims. The key is tailoring your policy to work seamlessly with your association’s master policy, whether it’s “bare walls” or “all-in” coverage.
At Mitchell-Joseph Insurance Agency, we specialize in navigating these complexities. As a family-owned, independent agency with over 200 years of combined experience, we leverage our relationships with 24 insurance companies to find you the perfect coverage at a competitive price.
We’re not just here to sell a policy; we’re your advocate. When damage occurs, we guide you through the claims process, work with adjusters, and fight for the settlement you deserve. That’s the value of having a local agent who knows you.
Don’t risk gaps in your coverage or pay for protection you don’t need. Let us create a custom insurance solution that fits your condo, your association’s rules, and your budget.
Get a personalized quote for your home insurance needs today. We’ll review your needs and find the right protection, because you deserve an insurance partner who has your back.

