

Why Every Business That Sells Products Needs Protection
Product Liability Insurance protects your business from financial ruin if a product you make, sell, or distribute causes injury or property damage. It’s essential coverage for manufacturers, retailers, online sellers, food businesses, and home-based makers.
This insurance typically covers:
- Legal defense costs for product-related lawsuits
- Medical expenses for injuries
- Property damage claims
- Claims arising from design flaws, manufacturing defects, and inadequate warnings
Modern product liability laws were shaped by cases like a 1944 incident where a Coca-Cola bottle exploded, injuring a restaurant worker. Today, even one defective product can bankrupt a small business. A furniture maker whose chair collapses or a bakery whose food causes illness could face devastating lawsuits. Without insurance, you’d pay legal fees, medical costs, and damages out of pocket, with compensation amounts often reaching tens or hundreds of thousands of dollars.
The good news is that product liability insurance is more affordable than most owners think, with average costs ranging from $42 to $99 per month. It provides critical protection whether you manufacture in a factory or make candles in your kitchen.
I’m Jeffrey Joseph, and at Mitchell-Joseph Insurance Agency, I’ve been helping businesses in the Finger Lakes Region protect their assets since 1999. I’ve seen how the right Product Liability Insurance can be the difference between a business surviving a claim and closing its doors for good.
Understanding Product Liability Insurance: A Complete Guide
What Is Product Liability and Why Is It Crucial?
Product liability is the legal responsibility you carry when something you manufacture, distribute, or sell causes harm—such as bodily injury or property damage—to a third party. For example, if a kitchen appliance you sell overheats and starts a fire, or a cosmetic product causes a severe allergic reaction, your business could be held responsible.
The legal side can be complex. It covers defects, malfunctions, design flaws, and even inadequate warnings. Under the principle of “strict liability,” your business can be held responsible even if you weren’t negligent. The fact that the product caused harm can be enough.
For any small business, Product Liability Insurance is essential for survival. Without it, a single incident could lead to legal defense costs, settlements, and medical expenses that can easily climb into the tens or hundreds of thousands of dollars. This financial burden can be impossible to overcome, forcing a business to close. That’s why we at Mitchell-Joseph Insurance Agency emphasize being prepared with comprehensive coverage. For a deeper dive, you can find more information on the legal definition of product liability, and remember that the importance of business insurance can’t be overstated.
Who Needs Product Liability Insurance?
If your business makes, sells, or distributes a physical product, you need Product Liability Insurance. This applies to a wide range of businesses, not just large factories.
This coverage is crucial for:
- Manufacturers: You are on the front lines of risk if you design, produce, or assemble any item.
- Retailers & Online Sellers: You can be held liable for the products you sell, especially if the original manufacturer cannot be identified. Many platforms like Amazon or Etsy require sellers to have coverage.
- Wholesalers & Distributors: As a link in the supply chain, you can be named in a lawsuit if a product you handle causes harm.
- Home-Based Businesses: Whether you’re crafting candles or baking goods, your small-scale operation still carries real liability risk.
- Food Businesses: Restaurants, bakeries, and food producers are especially susceptible to claims from foodborne illnesses or contamination.
- Importers: When you bring products into the U.S., you are often legally treated as the manufacturer, bearing full responsibility for product safety.
- Repair Services & Contractors: If your repair work or a completed installation (like a sink or fixture) later causes harm, you could be liable.
- Beauty & Cosmetology Businesses: Selling skincare, hair dyes, or other beauty items opens you to claims from adverse customer reactions.
Essentially, if your business puts a physical item into the marketplace, Product Liability Insurance is a foundational part of any solid plan, from business insurance for startups to established enterprises.
Decoding Your Coverage: What’s Included and What’s Not
Understanding your Product Liability Insurance policy is key. This coverage is designed to protect your business from the financial fallout when a product harms a third party.
What’s Typically Covered:
- Legal Fees and Defense Costs: Covers lawyers, court fees, and other legal expenses if you’re sued, regardless of whether you’re found liable.
- Medical Expenses: Pays for medical treatment if your product causes bodily injury.
- Property Damage: Covers the cost to repair or replace a third party’s property damaged by your product.
- Compensatory Damages: Includes funds paid to the injured party for pain and suffering, lost wages, and other financial impacts.
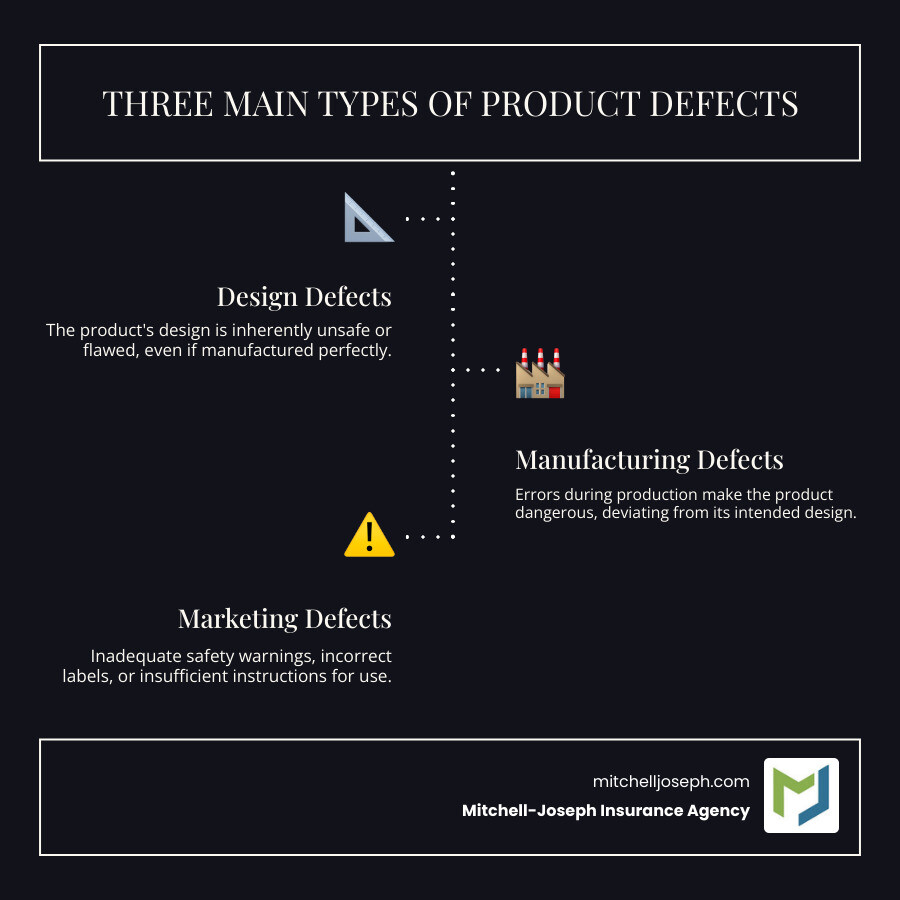
Claims typically arise from three types of defects: design defects (the product is inherently unsafe), manufacturing defects (errors during production), and marketing defects (inadequate warnings or instructions).
What’s Typically Not Covered:
- Employee Injuries: This is covered by Workers’ Compensation Insurance.
- Damage to Your Own Products: This falls under Commercial Property Insurance.
- Product Recall Costs: The direct costs of a recall (notifying customers, shipping, etc.) require a separate Product Recall Insurance policy.
- Bad Workmanship: If a product is simply inferior but doesn’t cause harm, it’s not a liability claim.
- Professional Services Errors: Financial losses caused by your advice or services are covered by Professional Liability (E&O) Insurance.
Understanding these distinctions is key. We can help you explore more info about business insurance policies to ensure you have all necessary protections.
Product Liability vs. General Liability: Key Differences
Business owners often confuse Product Liability Insurance with General Liability Insurance. While related, they cover different risks.
| Feature | Product Liability Insurance | General Liability Insurance |
|---|---|---|
| Primary Focus | Harm caused by your products or completed work. | Harm caused by your business operations or on your premises. |
| What it Covers | Bodily injury and property damage from a defective product. | Bodily injury and property damage on-premises, plus reputational harm. |
| Examples | A customer gets food poisoning; a defective toy injures a child. | A customer slips and falls in your store; an employee damages a client’s property. |
Think of General Liability as “slip-and-fall” coverage for your premises and operations. Product Liability Insurance kicks in when the harm comes directly from an item you’ve sold.
Many General Liability policies, especially in a Business Owner’s Policy (BOP), include “products-completed operations” coverage. This bundles a form of product liability with your general liability. However, the extent of this coverage varies. High-risk businesses (e.g., those dealing with food, machinery, or children’s products) may need a standalone Product Liability Insurance policy for adequate protection.
At Mitchell-Joseph Insurance Agency, we’ll review your operations to determine if your general liability policy is sufficient or if you need additional coverage. Learn more about General Liability Insurance and how it fits into your protection plan.
The Cost and Coverage Limits of Product Liability Insurance
“How much will this cost?” The price of Product Liability Insurance depends on your specific business.

Key factors that influence your premium include:
- Product Risk: Higher-risk items like food, chemicals, or children’s toys cost more to insure than lower-risk items like books or clothing.
- Sales Volume: Higher revenue means greater exposure and a higher premium.
- Industry Type: Some industries, like food service or construction, are statistically more prone to claims.
- Claims History: A history of prior claims will increase your costs.
- Quality Control: Strong safety measures can sometimes lead to lower premiums.
What can you expect to pay?
- The average cost is around $42 to $99 per month ($500 to $1,192 per year).
- Nearly one-third of businesses pay less than $30 per month.
This means that for many small businesses, Product Liability Insurance is surprisingly affordable.
Regarding coverage limits, most businesses choose a $1 million per-occurrence limit (the max paid for a single claim) and a $2 million aggregate limit (the total max paid per policy year). Businesses with higher risk exposure might consider higher limits. We’ll work with you to assess your risks and recommend limits that make sense for your business.
How to Secure Your Policy and Handle Claims
Getting the right Product Liability Insurance is a straightforward process.
If a customer claims your product caused harm, you first notify us, your insurance agent. Your provider will then investigate. If a lawsuit follows, your policy covers legal defense costs. If a settlement is reached or a court rules against you, the policy pays the covered damages up to your limit. This protection shields your business from the financial burden, allowing you to continue operating.
Here’s how to get your policy:
- Assess Your Needs: We’ll start by thoroughly understanding your business, your products, and your unique risks.
- Contact an Independent Agent: As an independent agency, Mitchell-Joseph works with 24 different insurance companies. We shop around to find you the best coverage at the most competitive rate.
- Compare Quotes: We’ll present you with customized options, detailing limits, deductibles, and premiums so you can make an informed choice.
- Bundle and Save: Often, Product Liability Insurance can be bundled into a Business Owner’s Policy (BOP) with General Liability and Commercial Property insurance for a cost-effective solution.
Once you choose a policy, we’ll help you finalize the paperwork and get your Certificate of Insurance (COI) as proof of protection. Whether you’re a local artisan or a regional distributor, we’re here to simplify the process. Don’t hesitate to reach out for business insurance quotes in NY.
Protecting Your Business: Next Steps

You’ve invested your time, money, and heart into your business. You deserve the peace of mind that one unexpected claim won’t undo all your hard work. That’s what Product Liability Insurance provides.
It ensures business continuity, allowing you to weather a potential lawsuit that might force an uninsured competitor to close. It means your legal defense is covered, medical bills are handled, and property damage claims won’t drain your savings. You can confidently serve your customers knowing you’re protected.
At Mitchell-Joseph Insurance Agency, we’re an independent, family-owned agency right here in your community. We don’t work for one insurance company; we work for you, comparing options from 24 different carriers to find the best fit for your business in Honeoye Falls, Rochester, or anywhere in the Finger Lakes Region.
We provide straightforward, personalized service to protect your livelihood. Securing your business’s future doesn’t have to be complicated.
Ready to protect everything you’ve built? Contact us for a comprehensive General Liability Insurance quote today. Let’s have a conversation about how we can help you move forward with confidence.

