

Why Every Photographer Needs Protection in Today’s Market
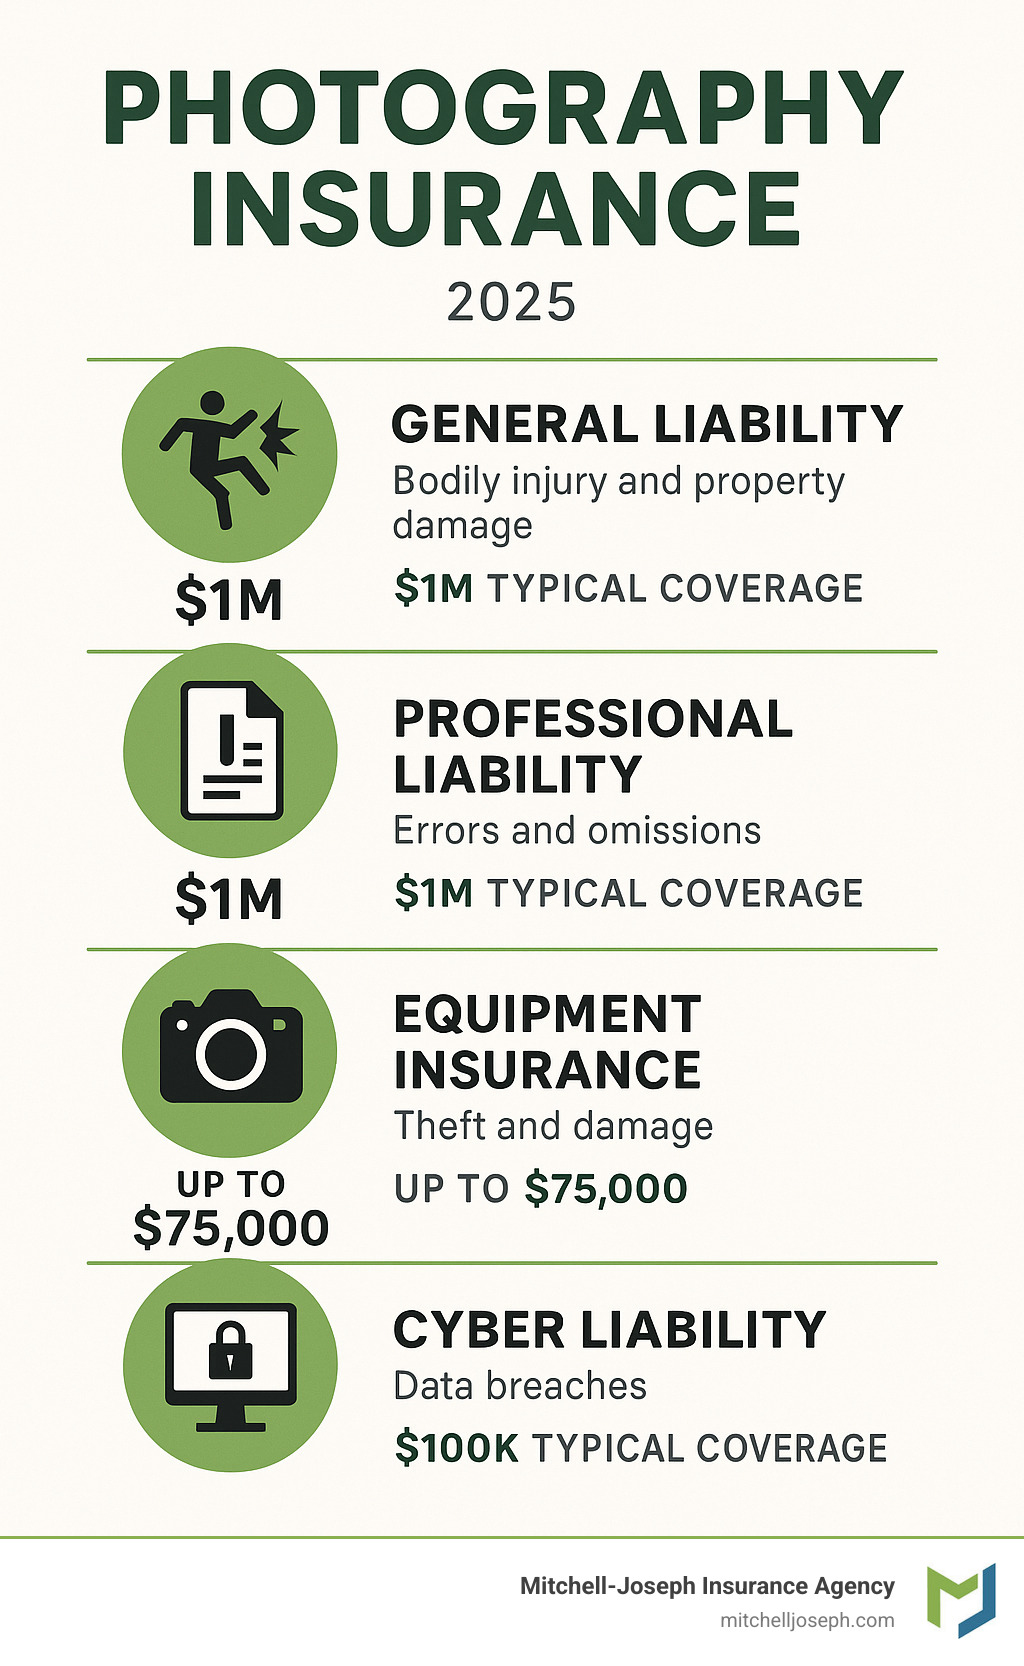
Photography insurance protects professional and amateur photographers from financial losses due to equipment damage, client lawsuits, and business interruptions. Whether you’re shooting weddings, portraits, or commercial projects, the right coverage shields your gear, reputation, and livelihood from unexpected risks.
Key Photography Insurance Types:
- General Liability – Covers client injuries and property damage at shoots
- Professional Liability (E&O) – Protects against claims of negligence or failure to deliver
- Equipment Coverage – Replaces stolen, damaged, or lost cameras and gear
- Cyber Liability – Covers data breaches and client information theft
The photography industry faces unique risks that standard homeowner’s or business policies often don’t cover. If you earn money from photography, your equipment becomes “commercial equipment” – and your personal insurance may not protect it. A single lawsuit from a client injury or lost wedding photos can cost thousands in legal fees alone.
Consider this real scenario from our research: A customer entering a photographer’s studio tripped and fell, injuring themselves and suing the photographer for $200,000. General liability insurance covered over $80,000 to resolve the lawsuit and $8,000 for legal defense expenses.
Without proper coverage, photographers risk losing their business, equipment, and financial security from one unfortunate incident.
I’m Jeffrey Joseph, owner of Mitchell-Joseph Insurance Agency, and I’ve been helping photographers and small business owners across the Finger Lakes region protect their assets since 1999. Through decades of experience with photography insurance claims and coverage, I’ve seen how the right policy can save a photographer’s career – and how the wrong coverage can leave them financially devastated.
Core Coverages: Protecting Your Gear, Business, and Reputation
A solid foundation of insurance is essential for any successful photographer. Let’s walk through the core policies that keep your business safe.
General Liability vs. Professional Liability: What’s the Difference?
People often mix up two key types of photography insurance: General Liability and Professional Liability. Let’s break down the difference.
General Liability Insurance is your protection against physical accidents. For example, if a client trips over your light stand and gets injured, or you accidentally knock over an expensive lamp at their home, General Liability covers these incidents.
This coverage handles bodily injury claims when someone gets hurt around your equipment or workspace. It also covers property damage and dreaded slip-and-fall claims that can turn into expensive lawsuits. Your General Liability Insurance policy will pay for medical bills, legal fees, and settlements if you are sued.
Professional Liability Insurance is completely different. This coverage, also called Errors & Omissions (E&O), is about your professional services. It protects you when clients claim you made mistakes or failed to deliver what you promised.
Maybe a memory card fails and you lose half the wedding photos. Perhaps a client says you were negligent because the lighting wasn’t what they expected. Or you get sick and can’t show up for a shoot, and the client claims your failure to deliver services cost them money. Professional Liability steps in when clients blame you for lost photos or other service problems.
Both types of coverage are essential parts of a complete Business Liability Insurance Policy. Think of General Liability as protecting you from physical accidents, while Professional Liability protects your reputation and work quality.
Equipment Insurance: Safeguarding Your Most Valuable Assets
Your gear—camera bodies, lenses, lighting equipment, and laptops—can easily be worth over $10,000. Losing it to theft or damage would be devastating.
Equipment insurance protects your gear from theft, accidental damage, and fire. I’ve seen photographers lose everything when their car gets broken into after a wedding. Others have watched expensive lenses shatter when a light stand gets knocked over. These aren’t rare events; they’re part of the business.
Here’s something that surprises many photographers: your homeowner’s policy probably won’t cover your professional gear. Once you start earning money from photography, your equipment becomes “commercial property.” Your personal insurance policy is designed to cover personal belongings, not business assets.
This is where Inland Marine coverage comes in. Don’t let the name confuse you—it has nothing to do with boats! Inland Marine is the insurance term for covering valuable items that move around. It’s often part of a broader Commercial Property Insurance policy.
The good news is that equipment coverage follows your gear wherever you go. Whether it’s stolen from your studio, damaged at a client’s location, or lost in transit, you’re covered. Just make sure you understand any homeowner’s policy exclusions before assuming you’re protected.
Specialized Coverage for Modern Photographers
Not all photographers face the same risks. A wedding photographer deals with different challenges than a studio owner, and event photographers have unique needs compared to those doing drone photography. Let’s look at what each specialty requires.
Wedding and event photographers often work in crowded, chaotic environments where accidents are more likely. You’re also traveling frequently with expensive equipment, making theft a bigger concern. Many venues will require you to show proof of insurance before you can even set foot on their property.
Studio owners need extra protection for their physical space. You’re responsible not just for your equipment, but for anyone who walks through your door. Commercial property coverage becomes crucial here, protecting both your building improvements and your business income if you have to close temporarily.
If you’re flying drones for aerial photography, standard policies won’t cut it. Drones create unique liability risks—they can malfunction, crash into property, or even injure people. You need specialized drone coverage that most photographers never think about.
Cyber Liability Insurance is becoming essential for all photographers. You store client information, process payments, and share files digitally. A data breach could expose sensitive client information and leave you facing expensive lawsuits and notification requirements. Client information protection isn’t just good business—it’s often legally required.
Don’t forget about Commercial Auto Insurance if you use your vehicle for business. Your personal auto policy won’t cover accidents that happen while you’re driving to shoots or transporting equipment. Business-use vehicles need business coverage—it’s that simple.
The key is matching your coverage to your actual risks. While professional organizations like the Professional Photographers of America (PPA) offer valuable business resources, insurance provides the essential financial backstop. A photographer just starting out has different needs than someone running a full-time studio, which is why working with an experienced agent makes all the difference in building the right protection plan.
The Financial Frame: Costs, Claims, and Getting Your Photography Insurance
Understanding the financial aspects of insurance is crucial. This section breaks down the typical costs, factors that influence your premium, and real-world examples of how insurance can save your business from financial disaster.
Understanding the Cost of Photography Insurance
A common question is, “What will this cost?” Considering the investment in gear, it’s a fair question. The good news is that photography insurance is surprisingly affordable for the protection it offers.
Based on industry data, a combined General Liability and Professional Liability policy with $1.5 million in coverage starts around $650 per year. For those just starting out, basic event policies can be as low as $59 per event or $129 annually.
Here’s what you can expect to pay for different types of coverage:
| Type of Coverage | Typical Annual Cost Range | What it Covers |
|---|---|---|
| General Liability | $300 – $700+ | Third-party bodily injury and property damage (e.g., client slips in studio) |
| Professional Liability | $350 – $800+ | Claims of negligence or errors in service (e.g., lost photos, missed deadlines) |
| Equipment Insurance | $100 – $500+ | Theft, accidental damage, fire for cameras, lenses, etc. (cost varies based on equipment value) |
| Cyber Liability | $250 – $750+ | Data breaches, cyberattacks, protecting client information |
| Combined CGL & PLI | $650 – $1,500+ | Comprehensive protection against common liability claims (often bundled) |
These are estimated ranges – your actual costs may vary based on your specific situation.
Several factors influence your photography insurance premium. Wedding and event photographers typically pay more than studio portrait photographers because they work in dynamic, unpredictable environments. Your coverage limits and deductibles also make a big difference—higher limits or lower deductibles will increase your premium.
Your business revenue plays a role, as higher earnings can mean more is at stake in a lawsuit. The value of your equipment directly impacts equipment insurance costs. Other factors include your number of employees, your location, and your experience level. Seasoned photographers with clean claims histories often qualify for better rates.
For photographers just starting out, considering insurance as part of your overall Business Insurance for Startups strategy makes smart financial sense from day one.
Common Claim Scenarios and Why Insurance Matters
It’s easy to think, “That won’t happen to me,” but the reality of photography involves risks with equipment, people, and irreplaceable memories. These real scenarios show why photography insurance is essential.

The wedding reception disaster: An enthusiastic guest trips over your light stand during the first dance, leading to an injury and a lawsuit. Your General Liability Insurance handles the legal defense and settlement. We’ve seen this coverage pay over $80,000 to resolve a lawsuit, plus $8,000 in legal defense costs.
Property damage claims: A tripod scrapes an antique table, or a backdrop stand chips a client’s car paint. These mishaps are covered by General Liability, with claims ranging from $75 for a dropped ornament to over $11,000 for car paint damage.
Lost or corrupted photos: A memory card fails, and you lose a client’s wedding photos. This can result in devastating lawsuits. Your Professional Liability Insurance protects you from claims of failing to deliver services, covering legal defense and settlements.
Equipment theft: You return to your vehicle to find a smashed window and your gear gone. Equipment Insurance replaces stolen or damaged items. For example, one policy paid over $2,000 to replace a camera knocked over at a wedding.
Cyber attacks: A phishing scam leads to ransomware that locks your files, or a data breach exposes sensitive client information. Cyber Liability Insurance covers data recovery, client notification, legal fees, and reputation management. Our Cyber Insurance Claims Examples show how crucial this protection has become.
These scenarios aren’t rare occurrences—they’re everyday risks that can derail a photography business. Photography insurance acts as your financial safety net, letting you focus on creating beautiful images instead of worrying about what could go wrong.
How to Get the Right Photography Insurance Policy
Getting the right photography insurance doesn’t have to be overwhelming. With the right preparation and guidance, the process is smooth.
Start by assessing your unique risks. What type of photography do you specialize in? What’s the total value of your equipment? Do you have employees? Do you handle sensitive client data? Understanding your specific situation helps us tailor coverage that fits your needs.
Next, we’ll determine your coverage needs together. Based on your risk assessment, we’ll identify the most important types of insurance for your business, such as General Liability, Professional Liability, Equipment Coverage, and potentially Cyber Liability or Commercial Auto Insurance. We’ll discuss appropriate coverage limits and deductibles that balance protection with your budget.
As an independent agency, we compare quotes from multiple sources. We don’t work for one insurance company; we work for you. We partner with 24 different insurance companies, allowing us to find the best coverage at competitive prices. You can start the process with our convenient Business Insurance Online Quote.
We’ll review every policy detail with you before you make a decision. No confusing jargon or hidden surprises. You’ll understand exactly what you’re covered for.
Finally, we’ll help you obtain your Certificate of Insurance (COI) when venues or clients require proof of coverage. We can generate these documents quickly, so you’re always ready for your next gig.
At Mitchell-Joseph Insurance Agency, we serve photographers and small business owners throughout the Finger Lakes region, including Honeoye Falls, Pittsford, Naples, Rushville, Avon, Bloomfield, Bristol, Canadice, Canandaigua, Cohocton, Fishers, Gorham, Honeoye, Ionia, Lima, Mendon, Middlesex, Potter, Rochester, Rush, South Bristol, Stanley, Victor, Wayland, and West Bloomfield, NY.
We’re not just selling policies—we’re protecting the passion and livelihood of fellow creatives. Ready to ensure your photography business is covered from every angle?

