Why Every Shot Needs a Safety Net
Best insurance for photographers protects your business from the unique risks of capturing life’s most precious moments. Whether you’re shooting weddings, corporate events, or running a portrait studio, your expensive equipment and client relationships face constant threats.
Top 3 Insurance Types Every Photographer Needs:
- General Liability Insurance – Covers third-party injuries and property damage (starting around $650/year for $1.5M coverage)
- Equipment Insurance – Protects cameras, lenses, and gear from theft or damage (homeowner’s policies typically exclude commercial equipment)
- Professional Liability Insurance – Covers client claims for missed shots, lost files, or service failures
The stakes are high in photography. One Reddit photographer shared how they had to decline a lucrative gig because the venue required insurance—a wake-up call that insurance isn’t optional for serious photographers.
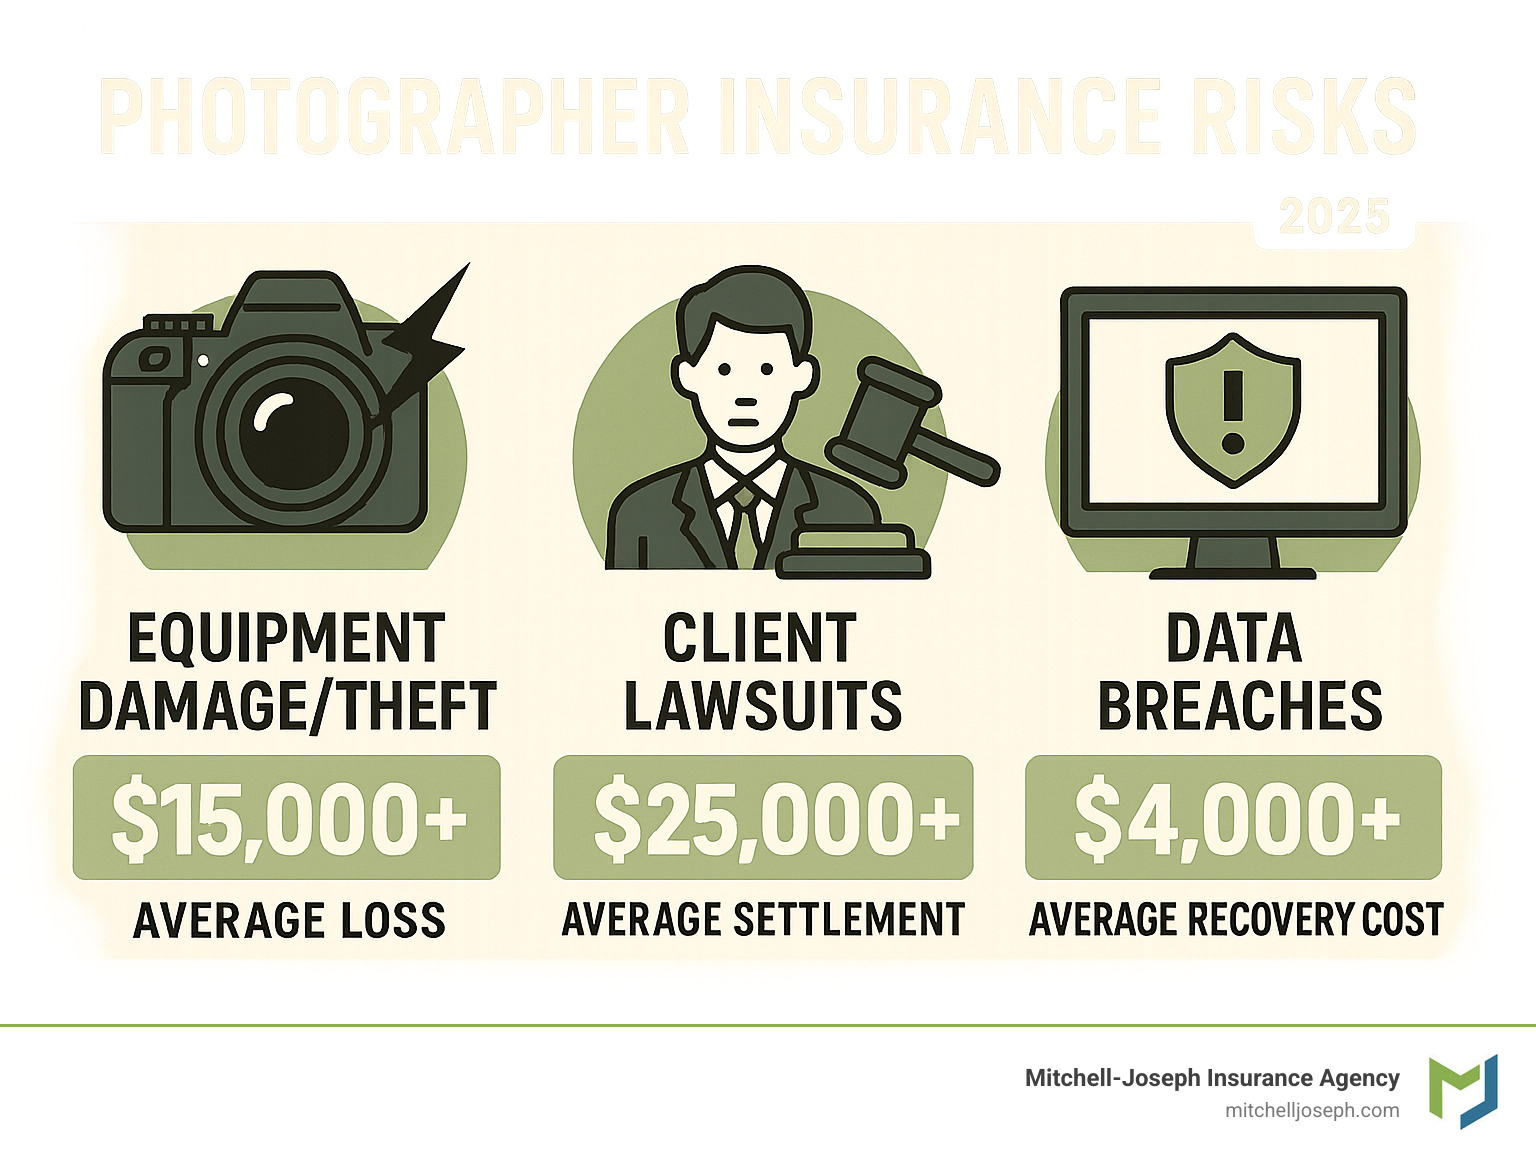
Your camera gear becomes “commercial equipment” the moment you accept payment for photography work. This means your homeowner’s insurance likely won’t cover theft, damage, or loss of your professional gear. Professional photographers face lawsuits averaging thousands of dollars when wedding photos are lost, clients trip over equipment, or memory cards fail at crucial moments.
From stolen equipment worth tens of thousands to liability claims from injured clients, photographers need specialized protection. The average cost starts around $650 per year for combined general and professional liability coverage—a small price compared to potential losses.
I’m Jeffrey Joseph of Mitchell-Joseph Insurance Agency. Since 1999, I’ve helped photographers in the Finger Lakes region secure comprehensive coverage. Finding the best insurance for photographers means understanding your unique risks and the options available in New York. Let’s explore the essential policies that will protect your business.
Understanding Your Coverage: A Guide to the Best Insurance for Photographers
Imagine a guest tripping over your lighting cable at a wedding or your camera bag being stolen from your car. Without proper coverage, these scenarios could cost thousands and potentially end your photography career.
The best insurance for photographers isn’t just one policy—it’s a collection of coverages that protect every aspect of your business. Just as you need different lenses for different shots, you need different insurance policies for different risks.
Core Coverage: The Must-Have Policies
These three policies form the foundation of photographer insurance. Without them, you’re essentially shooting without a safety net.
General Liability Insurance acts as your first line of defense against everyday accidents. This coverage protects you when someone gets hurt or property gets damaged because of your business operations.
Many venues won’t let you through the door without proof of General Liability coverage, typically requiring at least $1 million in protection. The good news? Combined General Liability and Professional Liability coverage often starts around $650 per year for $1.5 million in protection.
Your policy covers medical bills, repair costs, and legal fees if a client trips over your tripod, you knock over an heirloom, or your lighting damages a venue’s wall. Without it, you’d pay these costs out of your own pocket. For detailed information, check out our General Liability Insurance page.
Professional Liability Insurance covers the mistakes that keep photographers awake at night. This coverage, also called Errors and Omissions insurance, protects you when clients claim you made professional mistakes.
When a memory card fails or files become corrupted, you’re not just dealing with disappointed clients—you’re facing potential lawsuits for thousands of dollars. Professional Liability coverage helps pay for legal defense and settlements when clients sue over alleged professional errors.
It also covers claims that you missed important shots, delivered work late, or failed to meet expectations, protecting you even if a client’s claim is unfounded. For a general overview of this coverage, see Professional liability insurance.
Equipment Insurance protects your most valuable business assets—your cameras, lenses, lighting, and computers. Professional photography gear represents a massive investment. Here’s the catch: your homeowner’s insurance probably won’t cover it.
The moment you start earning money from photography, your gear becomes “commercial equipment.” Your homeowner’s policy may not cover your gear if you have sold prints in the past, leaving you completely vulnerable to theft, damage, or loss.
Equipment Insurance covers repair or replacement costs when your gear gets stolen, damaged in a fall, or destroyed in a fire. Many policies even provide worldwide coverage, protecting your equipment whether you’re shooting locally in Rochester or on a destination wedding.

Specialized Protection for Modern Photographers
Today’s photographers face new digital threats and mobile business risks that require specialized protection.
Cyber Liability Insurance protects your digital life and your clients’ private information. Photographers store thousands of client photos, contact information, and payment details, making them a target for hackers and data breaches.
Imagine ransomware encrypting your client files or a data breach exposing their payment details. Cyber Liability coverage helps pay for data recovery, client notification costs, and legal fees when digital disasters strike. Learn more about protecting your digital assets with our Cyber Liability Insurance options.
Commercial Auto Insurance covers you when personal auto insurance falls short. If you use your car to drive to shoots or transport equipment, you’re using it for business. Your personal auto policy might deny coverage if an accident happens during business activities.
Commercial Auto Insurance specifically covers business use of vehicles, protecting you from damages and liability claims that occur while you’re working. For comprehensive protection on the road, explore our Commercial Auto Insurance solutions.

Business Operations Insurance
These policies protect the broader health of your photography business, ensuring you can weather major disruptions.
Business Interruption Insurance replaces lost income when disasters shut down your business. If a fire damages your studio, this coverage helps cover ongoing expenses and replaces lost earnings while you’re temporarily closed. This is vital for photographers with dedicated studios, as a disaster could shut you down for months. For New York businesses, understanding your options for Business Interruption Insurance NY is crucial.
Workers’ Compensation Insurance is legally required once you hire employees, even part-time assistants. This coverage provides medical benefits and wage replacement for employees who suffer work-related injuries. For example, if an assistant breaks an ankle on a shoot, Workers’ Comp covers their medical bills and lost wages. Our Workers Comp Insurance guide explains your obligations.
Business Owner’s Policy (BOP) bundles essential coverages into one convenient, cost-effective package, typically combining General Liability, Commercial Property, and Business Interruption insurance. A BOP is ideal for studio photographers, protecting your liability, physical property, and covering lost income if the studio becomes unusable.
Decoding the Cost: What to Expect for the Best Insurance for Photographers
Insurance pricing reflects your unique business needs and risk factors.
- Location: Rates vary by state and region. A photographer in Rochester may have different rates than one in Honeoye Falls due to local risk factors.
- Revenue: Higher earnings often mean more business activity and greater risk, which can influence your premium.
- Employees: Hiring employees requires Workers’ Compensation, which will affect your total cost.
- Experience: Years of experience and a clean claims history can lead to lower premiums.
- Services Offered: Your specialty matters. Wedding or drone photography often carries higher risks and premiums than portrait work.
- Policy Limits & Deductibles: You can adjust your premium by choosing different coverage limits and deductibles. Finding the right balance is key.
We work with 24 different insurance companies to find competitive rates for your specific situation. For general guidance, visit our Business Insurance FAQ page.
Securing Your Policy: The Smart Way to Get Insured
You’ve learned about the different types of coverage, but how do you choose and secure the best insurance for photographers? It’s about making smart decisions that will truly protect your livelihood.
How to Choose the Right Photographer Insurance Policy
Choosing insurance is like selecting the right lens for a shoot; it requires considering your specific situation and goals.
Coverage limits deserve careful attention. Base your coverage limits on the potential financial impact of a worst-case lawsuit or equipment disaster.
Deductibles work like a balancing act. A higher deductible lowers your annual premium, but ensure it’s an amount you can afford to pay out-of-pocket. For expensive gear, a low deductible (as little as $350) can be a smart choice.
It’s also important to understand the difference between claims-made and occurrence policies. An occurrence policy covers incidents that happen during the policy period, regardless of when a claim is filed, offering superior long-term protection. A claims-made policy only covers claims filed while the policy is active. They may be cheaper initially but require expensive “tail coverage” if you cancel the policy.
Your insurance company’s financial strength matters. A great policy from a company that can’t pay claims is worthless. We only work with financially strong, reputable carriers.
If you’re part of a professional photography association, check for member discounts or special programs. The goal isn’t to find the cheapest policy—it’s to find the right balance of comprehensive protection and affordability. For more guidance, check our page on Business Insurance Policy.
Getting Your Quote and Finalizing the Best Insurance for Photographers
Getting a quote is a straightforward process. We’ll ask for some basic information about your business to find the right coverage for you.
We’ll need to understand your photography specialty (weddings, portraits, commercial), your business setup (studio, home-based, on-location), and your business location. Whether you’re based in Honeoye Falls, Pittsford, Naples, Rochester, or our other service areas, local factors can influence your needs.
We’ll also ask for revenue estimates, whether you have employees, what vehicles you use for business, and your claims history. The entire process typically takes about 10 minutes.
Here’s where working with an independent agent makes all the difference. As a family-owned business in Honeoye Falls, we’re not tied to a single insurance company.
With over 200 years of combined experience and access to 24 different insurance companies, we work for you, not an insurer. We compare options from multiple top-rated carriers to find competitive quotes and coverage that fits your specific needs and budget.
Being deeply rooted in the Finger Lakes region means we understand the local business landscape, which translates into better advice and more appropriate coverage for photographers working in New York.
We serve photographers throughout Honeoye Falls, Pittsford, Naples, Rushville, Avon, Bloomfield, Bristol, Canadice, Canandaigua, Cohocton, Fishers, Gorham, Honeoye, Ionia, Lima, Mendon, Middlesex, Potter, Rochester, Rush, South Bristol, Stanley, Victor, Wayland, and West Bloomfield, NY.
Don’t let insurance complexity keep you from protecting what you’ve built. We’re here to make it straightforward. Let us help you secure the best insurance for photographers so you can focus on capturing those irreplaceable moments. Ready to get started? Get a quote for Business Insurance for Photographers today.