

Why Pharmaceutical Liability Insurance Is Critical for Your Practice
Pharmaceutical liability insurance is essential for protecting companies, pharmacists, and medical device makers from the high cost of lawsuits, recalls, and fines. This specialized coverage shields you from claims involving dispensing errors, manufacturing defects, clinical trials, and inadequate warnings.
Quick Answer: What Does Pharmaceutical Liability Insurance Cover?
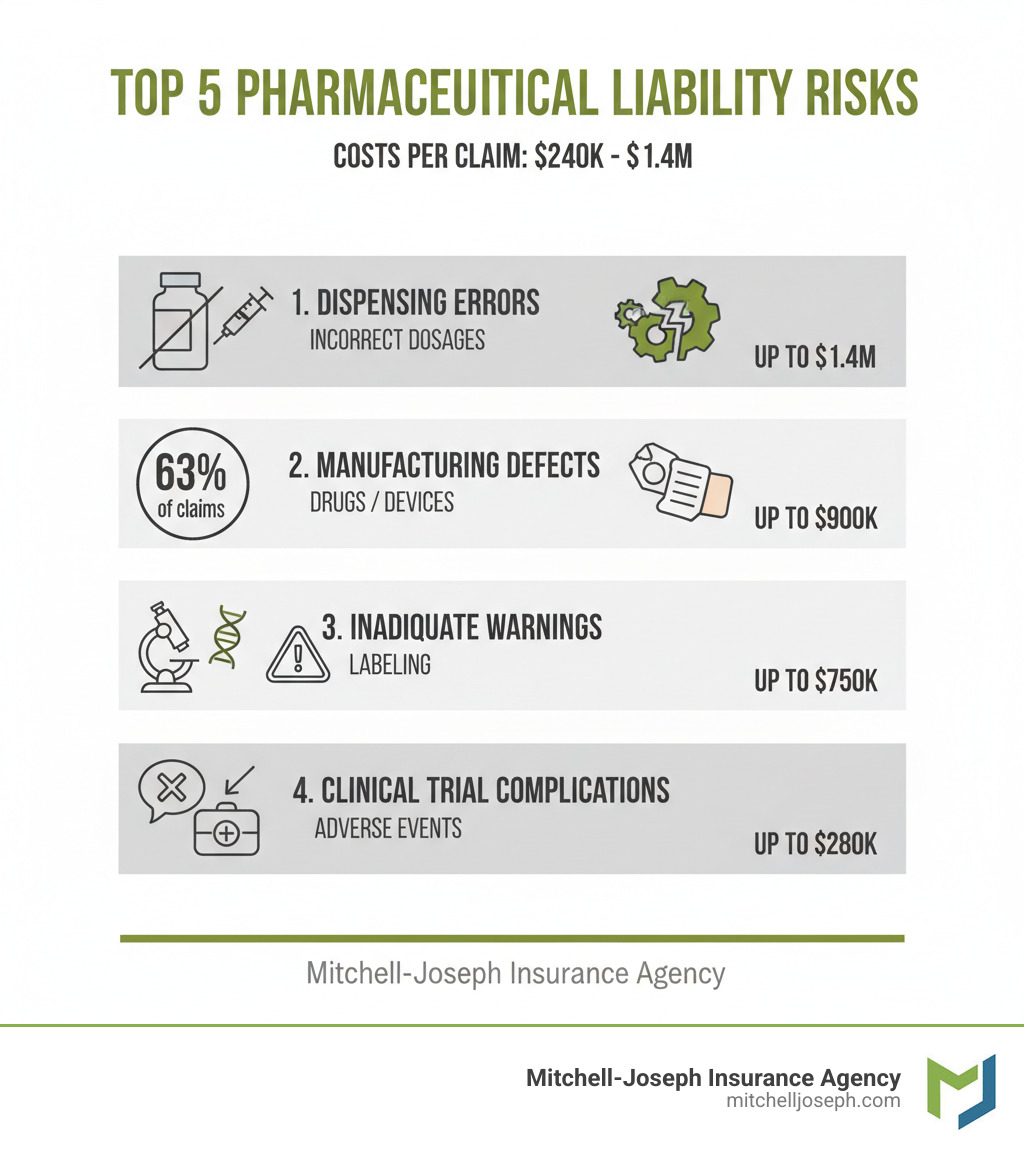
- Professional Liability: Dispensing errors, incorrect dosages, failure to counsel patients
- Product Liability: Manufacturing defects, design flaws, inadequate warnings
- Clinical Trials Coverage: Claims arising from research and testing
- Legal Defense: Court costs and tribunal defense ($50,000-$100,000)
- Regulatory Compliance: Meeting mandatory requirements (e.g., $2M per claim, $4M aggregate)
- License Protection: Defense against disciplinary charges from licensing boards
The stakes are exceptionally high. A single dispensing error can result in a $1.4 million verdict, while a failure to counsel claim can cost $280,000. Research shows 63% of lawsuits against pharmacists involve incorrect medication or dosage—errors leading to patient harm, license suspension, and financial ruin.
The landscape is also evolving. Pharmacists now administer vaccinations and prescribe medications, expanding their liability. Meanwhile, manufacturers face scrutiny over clinical trials and global distribution.
Many professionals mistakenly believe their employer’s insurance is enough. It isn’t. Employer policies protect the company first, often excluding coverage for regulatory hearings or license defense. An individual policy follows you throughout your career, ensuring you’re protected.
I’m Jeffrey Joseph, and I’ve been helping professionals in the Finger Lakes region secure comprehensive business insurance since 1999, including specialized pharmaceutical liability insurance. At Mitchell-Joseph Insurance Agency, we understand the unique risks you face and work with you to find coverage that protects both your practice and your peace of mind.
Understanding Your Pharmaceutical Liability Insurance Options
Protecting your company or career in the pharmaceutical industry requires the right insurance strategy. At Mitchell-Joseph Insurance Agency, we know that pharmaceutical liability insurance isn’t one-size-fits-all. Your needs depend on your role, whether you’re a pharmacist, a drug manufacturer, or conducting clinical trials. We specialize in professional-liability-insurance that addresses the unique challenges of your field, ensuring you meet regulatory requirements while safeguarding your reputation.
Corporate vs. Professional Liability: Who Needs What?
Understanding the difference between corporate and individual professional liability is key, as they protect against different risks.
Corporate liability insurance protects companies—manufacturers, developers, biotech startups, and research organizations (CROs/CMOs). It addresses large-scale risks like:
- Manufacturing defects leading to contaminated products.
- Design flaws that make a medical device unsafe.
- Inadequate warnings on labels causing patient harm.
- Clinical trial liabilities from unexpected side effects or flawed trial design.
For companies entering this space, securing comprehensive business-insurance-for-startups with these coverages is essential.
Individual professional liability insurance (or malpractice insurance) protects pharmacists and technicians from claims arising from their direct patient work. The most common claims involve dispensing the wrong medication or dosage. For example, a simple dispensing error could lead to a patient’s hospitalization and a $280,000 lawsuit. Other risks include compounding errors and failure to properly counsel patients on medication use and side effects. Regulatory bodies like the Ontario College of Pharmacists (OCP) mandate that all registrants maintain personal professional liability insurance.
Key Coverages Within a Pharmaceutical Liability Insurance Policy
A comprehensive policy bundles multiple coverages to create a strong safety net. Key components include:
- Product Liability: Protects manufacturers and distributors when a defect in a product causes bodily injury or property damage.
- Professional Liability (Errors & Omissions): Covers the services you provide, such as dispensing, counseling, or clinical trial design. This is where errors-omissions-coverage is critical.
- Clinical Trials Insurance: Dedicated coverage for claims from trial participants who suffer injuries.
- Legal Defense Costs: Covers attorney fees and court costs, whether you are found liable or not.
- Tribunal Defense Costs: Provides $50,000 to $100,000 for legal expenses if you’re called before a disciplinary committee.
- Criminal Action Extension: Reimburses legal defense costs for criminal charges related to your work, provided you’re found not guilty.
- Cyber and Data Breach Liability: Essential for protecting patient data (Protected Health Information). Cyber-liability-insurance helps cover fines and penalties for breaches under regulations like HIPAA.
Navigating Policy Details: Limits, Exclusions, and Types
Understanding your policy’s structure is as important as knowing what it covers.
- ‘Claims-Made’ vs. ‘Occurrence’ Policies: Most professional liability policies are claims-made, meaning they cover claims filed during the policy period. This makes continuous coverage vital. If you cancel your policy, you need an Extended Reporting Period (ERP), or “tail coverage,” to protect against future claims from past incidents. An occurrence policy covers incidents that happen during the policy period, regardless of when the claim is filed.
- Coverage Limits: A typical structure is $2 million per claim with a $4 million annual aggregate. The per-claim limit is the max paid for one claim, while the aggregate is the total for the policy year. Regulatory bodies often mandate these minimums.
- Exclusions and Deductibles: Policies commonly exclude intentional or criminal acts. Read the exclusions section carefully. Your deductible is the amount you pay out-of-pocket before insurance kicks in.
Why Employer-Provided Insurance Isn’t Enough
Relying solely on your employer’s insurance is a significant risk. Here’s why we recommend individual professional liability insurance:
- Employer’s Interests First: The policy is designed to protect the company, and its interests may conflict with yours in a lawsuit.
- No License Protection: Employer policies rarely cover your legal defense costs for disciplinary hearings that could threaten your license.
- Lack of Portability: Coverage ends when you leave the job, leaving you exposed to claims filed after your departure for incidents that happened while you were employed.
- Gaps in Scope: Employer policies may not cover expanded duties like administering vaccinations or prescribing medications.
- Peace of Mind: An individual policy ensures you have dedicated protection that follows you throughout your career.
For medical professionals, our team at Mitchell-Joseph Insurance Agency can help steer these complex needs. Learn more about how business-insurance-for-medical-professionals can protect your career.
Securing the Right Protection for Your Future
The pharmaceutical world moves fast, and your pharmaceutical liability insurance needs to keep pace. At Mitchell-Joseph Insurance Agency, we help professionals and companies stay protected as their risks evolve. We believe insurance is a living document, not a file-and-forget task. We work with you to ensure your coverage adapts to your changing needs, so you can focus on your critical work.
Meeting Regulatory and International Requirements
Regulatory compliance is non-negotiable. The Ontario College of Pharmacists (OCP), for example, mandates that every registrant carry at least $2 million per claim and $4 million in annual aggregate coverage. Similar requirements exist worldwide, including AHPRA requirements in Australia. We ensure your business-insurance-quotes-ny meet these standards.
For companies operating across borders, multinational insurance programs are essential. These programs comply with local laws in each jurisdiction—some insurers cover over 180 countries—while providing cohesive global protection. Managing cross-border claims requires specialized expertise, which we provide.
How to Ensure You Have Adequate Coverage
Having insurance and having the right insurance are two different things. Here’s how to make sure you’re truly protected:
- Review Your Policy Annually: Your practice changes. New services like vaccinations or new product lines introduce new liabilities. An annual review ensures your coverage still fits.
- Assess Expanded Services: As pharmacists take on more responsibilities like prescribing, ensure your policy explicitly covers these activities.
- Work with a Specialist: You need an insurance partner who understands your complex industry. As an independent agency with over 200 years of combined experience and access to 24 insurance companies, we find custom solutions. If you’re looking for knowledgeable business-insurance-agents-near-me in the Finger Lakes region—from Rochester to Victor—we’re here to help.
- Understand Your Policy: Ask questions about what is and isn’t covered. We believe in clear, straightforward communication without the jargon.
- Plan for the Future: If you plan to retire or change careers, consider an Extended Reporting Period (ERP) or “tail coverage.” For claims-made policies, this is critical for protecting you from claims filed after your policy ends.
At Mitchell-Joseph Insurance Agency, we’re committed to providing personalized service and competitive quotes. We understand the high stakes and take our role in protecting your practice and livelihood seriously.
Don’t leave your future to chance. Protect yourself and your business today.

