

Why New Yorkers Need an Extra Layer of Protection
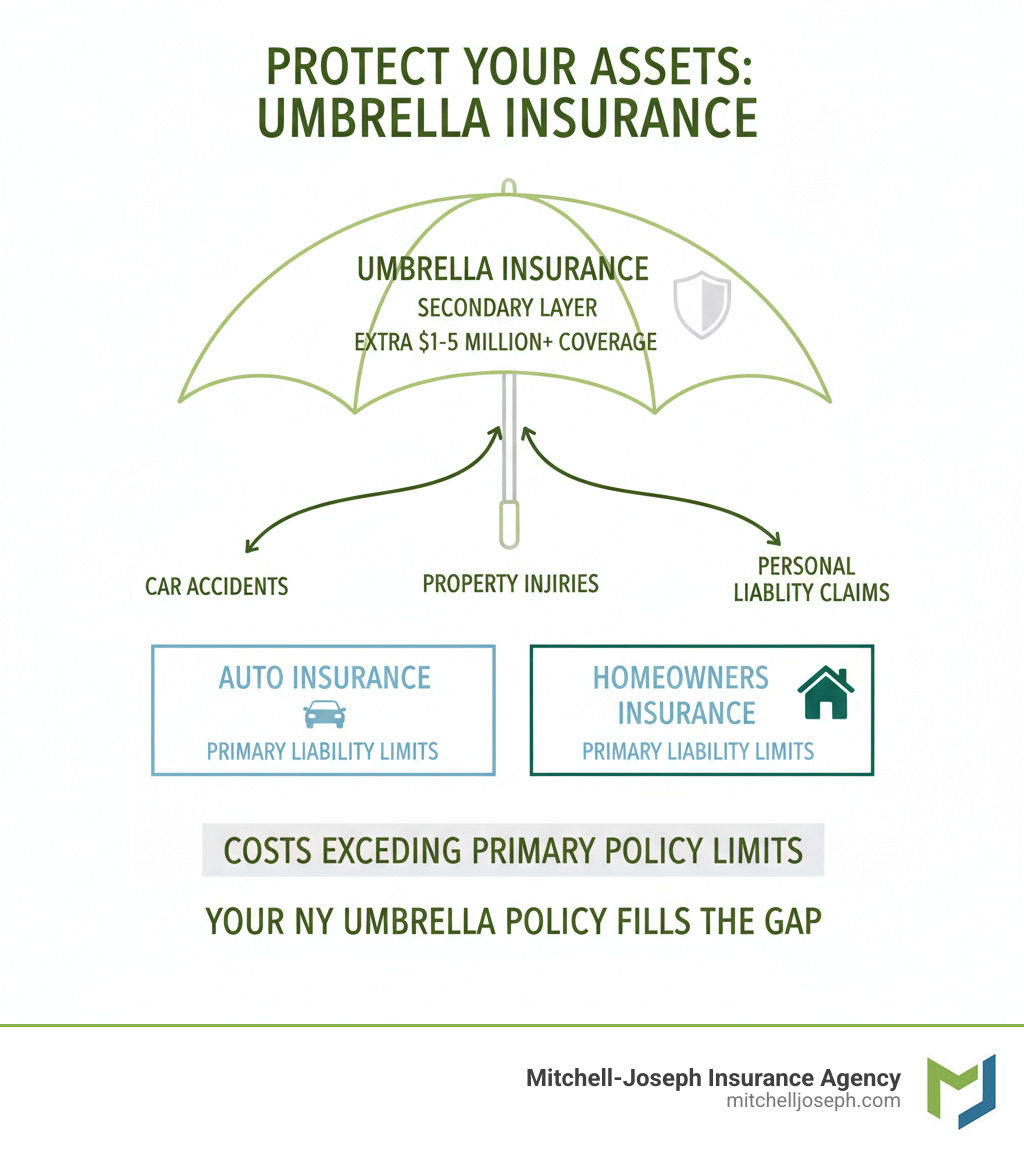
A ny umbrella insurance policy provides extra liability coverage that kicks in when your home or auto insurance limits are exhausted, protecting your assets from major lawsuits and claims. It typically adds $1 million or more in coverage for just $150-$300 per year, making it an affordable way to safeguard your savings, property, and future earnings from catastrophic financial loss.
Key Facts About NY Umbrella Insurance:
- What it is: Secondary insurance that supplements your existing auto, home, or rental policies
- Coverage amount: Usually starts at $1 million, with options up to $5 million or more
- Annual cost: $150-$300 for $1 million; each additional $1 million costs $50-$75
- Requirements: Minimum underlying limits (typically $250k/$500k for auto, $300k for home)
- What it covers: Bodily injury, property damage, legal defense, libel, slander, defamation
- What it doesn’t cover: Your own property damage, intentional acts, business liability
Everyone makes mistakes once in a while. Sometimes a mistake, error in judgment, or negligent act can result in someone else suffering significant loss or injuries. In New York, where the average cost of a collision-related death is around $1.4 million and legal costs run high, a single serious accident can wipe out everything you’ve worked for.
Why New York residents face unique risks:
New York’s dense population, high cost of living, and complex legal environment create a perfect storm for liability exposure. Whether you’re navigating busy Rochester streets, hosting guests at your Finger Lakes home, or dealing with the state’s plaintiff-friendly courts, the risk of a lawsuit exceeding your standard policy limits is very real.
The good news? Umbrella insurance is surprisingly affordable for the protection it provides. Most people can secure $1 million in additional coverage for less than the cost of a monthly streaming subscription.
I’m Jeffrey Joseph, and I’ve been helping families and business owners across the Finger Lakes region protect their assets since 1999 at Mitchell-Joseph Insurance Agency. Throughout my career, I’ve seen how a ny umbrella insurance policy can mean the difference between financial security and devastating loss when unexpected accidents happen.
Your Comprehensive Guide to a NY Umbrella Insurance Policy
Who Needs Umbrella Insurance and What Does It Cover?
At Mitchell-Joseph Insurance, we hear this question all the time: “Is umbrella insurance really for me?” Here’s the truth – if you’ve worked hard to build a life in New York, whether that’s a home, savings, investments, or simply your ability to earn a living, then a ny umbrella insurance policy deserves your attention. And no, it’s not just for millionaires with vacation homes and luxury cars. It’s for everyday families who want to protect what they’ve worked so hard to build.
Let’s talk about who really benefits from this coverage and what it actually protects you from.
If You Own or Rent a Home, You Need This
Your home is probably your biggest asset, but it’s also a source of liability you might not think about every day. Picture this: a delivery driver slips on your icy sidewalk in Pittsford during a February freeze. Your neighbor’s kid gets hurt on your trampoline. Your dog, usually the sweetest creature on earth, gets startled and bites a visitor. These things happen to good people all the time.
Your homeowners or renters insurance typically covers liability up to $300,000 or $500,000. That sounds like a lot until you’re facing a serious injury lawsuit. Medical bills, lost wages, pain and suffering – these numbers add up fast. A ny umbrella insurance policy steps in when those primary limits run out, protecting everything else you own. More info about Homeowners Insurance NY
If You Drive in New York, You’re Taking Risks Every Day
Let’s be honest – driving in New York isn’t always a peaceful experience. Whether you’re navigating rush hour in Rochester or dealing with winter weather in Canandaigua, accidents happen. And when they do, the financial consequences can be staggering.
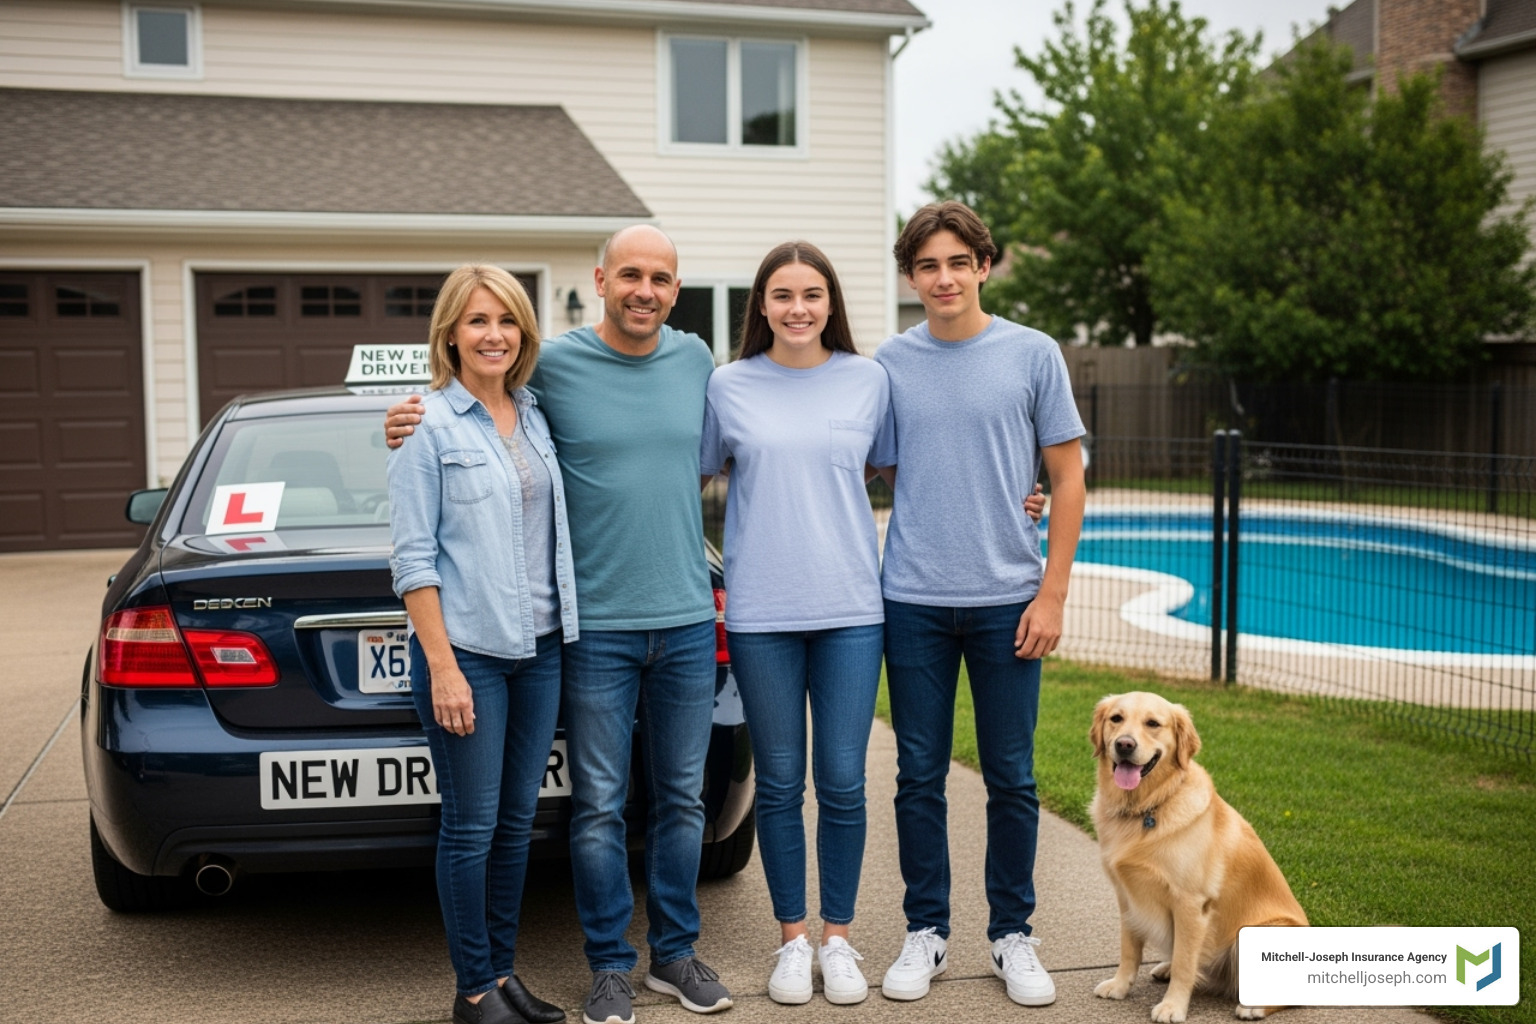
The average cost of a collision-related death in New York hovers around $1.4 million. That’s not just a statistic – it’s someone’s life, and if you’re found at fault, it could mean losing everything. Your auto insurance liability limits might be $250,000 per person and $500,000 per accident, but a serious multi-car accident can blow past those numbers in a heartbeat. This is especially true if you have a teen driver on your policy. We love our kids, but let’s face it – inexperience behind the wheel increases risk. More info about Auto Insurance in Rochester
Parents Face Unique Liability Risks
Kids are wonderful, but they’re also unpredictable. Maybe your teenager posts something online that crosses a line. Maybe there’s an accident during a playdate at your house. Maybe your new driver backs into someone’s luxury car at the mall. As a parent, you can be held responsible for your children’s actions, and those lawsuits can quickly exceed your standard policy limits.
The More You Have, The More You Need to Protect
This one’s pretty straightforward. If you’ve accumulated significant assets – retirement accounts, investment properties, savings – you have more to lose. A substantial judgment against you could mean selling your home, liquidating your retirement savings, or having your wages garnished for years to come. That’s a sobering thought, but it’s also completely preventable with the right coverage.
Special Risk Factors That Make Umbrella Insurance Essential
Some situations naturally carry higher liability risks. If you own a boat, you’re dealing with the same catastrophic injury potential as car accidents, just on water. Swimming pools are considered an “attractive nuisance” in legal terms, which means you have extra responsibility if neighborhood kids are drawn to it. Landlords face liability from tenants and their guests that goes beyond standard landlord insurance. And if you travel frequently, you’ll appreciate that umbrella policies often provide worldwide coverage for certain incidents.
What Your Umbrella Policy Actually Covers
A ny umbrella insurance policy casts a wide protective net over your life. It covers bodily injury liability when someone gets hurt and you’re responsible – covering their medical bills, lost income, and pain and suffering beyond what your primary insurance pays. It covers property damage liability when you accidentally damage someone else’s belongings.
But here’s where it gets really interesting. Umbrella insurance also covers personal injury claims that many people don’t even think about. If someone accuses you of libel or slander – making false statements that harm their reputation – your umbrella policy provides protection. The same goes for defamation of character, false arrest or imprisonment, and invasion of privacy. In today’s world of social media and instant communication, these risks are more real than ever.
And here’s something that surprises most people: your umbrella policy typically covers legal defense costs even when your primary policies won’t. Even if a lawsuit against you is completely baseless, defending yourself can cost tens of thousands of dollars. Your umbrella coverage helps with those costs, which can be a financial lifesaver.
Real Stories From Our Community
Let me paint you some pictures of situations we’ve seen right here in the Finger Lakes region.
You’re hosting a summer barbecue at your Honeoye home. The weather’s perfect, the grill is going, everyone’s having a great time. Then a guest trips over an uneven patio stone, falls hard, and suffers a serious head injury. The medical care and rehabilitation costs hit $1 million. Your homeowners policy covers $300,000. Without an umbrella policy, you’re personally responsible for the remaining $700,000. That could mean losing your home, your savings, everything.
Or imagine your son, fresh out of driver’s ed, is heading to school in Avon. He glances at his phone for just a second and causes a multi-car pileup. Multiple people are seriously injured. The total damages come to $800,000. Your auto policy maxes out at $500,000. That $300,000 difference? It comes from your pocket – unless you have umbrella coverage.
Here’s a modern one: you’re frustrated with a local business and post a critical comment on social media. It’s more harsh than you intended, and the business owner in Canandaigua claims your comments caused real financial harm to their reputation. They sue you for defamation. Your standard policies won’t touch this, but your ny umbrella insurance policy would cover your legal defense and any settlement.
These scenarios aren’t meant to scare you – they’re meant to show you that liability risks touch all of us, regardless of our income or lifestyle. The good news is that protecting yourself is more affordable than you might think.
Understanding Your NY Umbrella Insurance Policy: Costs & Exclusions
Let’s talk money. One of the best things about a ny umbrella insurance policy is how little it costs for the massive protection it provides. We’re talking about safeguarding everything you’ve worked for, often for less than you spend on coffee each month.
What You’ll Actually Pay
Most umbrella policies in New York start at $1 million in coverage, though you can purchase anywhere from $1 million up to $10 million or more, depending on your needs. The typical cost for that first $1 million? Just $150 to $300 per year. That’s roughly $12 to $25 per month for a million dollars in protection.
Want more coverage? Each additional $1 million typically costs between $50 and $75 annually. So for $200 to $375 per year, you could have $2 million in coverage. It’s remarkably affordable because umbrella policies only kick in after your primary insurance is exhausted, which means actual claims are relatively rare.
What Affects Your Premium
Your exact cost depends on several factors, and understanding them helps you see where you stand. The coverage amount you choose obviously matters – more protection costs more, though the incremental cost is quite reasonable. If you have multiple homes, several vehicles, or recreational items like boats or ATVs, your premium might be slightly higher simply because you have more exposure to potential incidents.
Your personal risk profile plays a role too. Insurance companies look at your driving record, claims history, and certain lifestyle factors. That swimming pool in your backyard? The trampoline the kids love? These can affect your rates because they increase risk. Your location matters as well – living in densely populated areas like Rochester or busy suburbs sometimes means slightly higher premiums compared to rural areas, simply because the potential for incidents and large settlements is greater.
The people in your household factor in too. Multiple drivers, especially young or inexperienced ones, can impact your premium. But don’t let this discourage you – the protection is still incredibly affordable for what you’re getting.
Smart Ways to Save Money
We love helping our clients save money, and umbrella insurance comes with some excellent opportunities to do just that. The biggest savings come from bundling your umbrella policy with your existing auto and homeowners insurance. Many insurers offer substantial multi-policy discounts – we’re talking 15-20% off your other policies when you bundle them together. This not only puts money back in your pocket but also simplifies your insurance management. One agent, one relationship, one phone number to call when you need help.
Maintaining a clean driving record and taking steps to reduce risk around your home can also help keep your overall insurance costs down, making that umbrella policy even more affordable.
What Your Umbrella Policy Won’t Cover
Now let’s talk about what umbrella insurance doesn’t do, because understanding the boundaries is just as important as knowing the coverage. A ny umbrella insurance policy is a liability policy, which means it protects you when you’re responsible for harm to others. It doesn’t cover your own injuries or damage to your own property. If you get hurt or your car gets damaged, you’ll rely on your health insurance, auto collision coverage, and homeowners property coverage for those situations.
If you intentionally cause harm or damage, or if something happens while you’re committing a crime, your umbrella policy won’t provide coverage. That’s a standard exclusion across all insurance policies. Similarly, if you run a business from home or provide professional services, your personal umbrella won’t cover those business-related liabilities. You’d need separate business insurance for that kind of protection.
Liability that you assume under a contract, damage from war, or nuclear events – these are also typically excluded. The specifics can vary between policies, which is why we always recommend sitting down with your agent to review exactly what your policy covers and what it doesn’t. That conversation ensures there are no surprises down the road.
For more detailed information about umbrella policies and how they work in New York, you can Learn more from the NY Department of Financial Services.
How to Qualify for and Purchase a Policy
Getting a ny umbrella insurance policy is actually pretty straightforward, but there are some specific requirements you need to meet first. Insurance companies want to make sure you have solid primary coverage in place before they add that extra layer of protection on top.

Making Sure Your Foundation Is Solid
Think of umbrella insurance like building a house – you need a strong foundation before you can add the roof. That foundation is your primary insurance coverage, and insurers require certain minimum liability limits on your auto, homeowners, renters, and other policies before they’ll sell you an umbrella policy.
For your auto insurance, most providers want you to carry at least $250,000 per person and $500,000 per accident in bodily injury liability, plus $100,000 for property damage. You’ll see this written as 250/500/100. While New York requires all drivers to carry at least $50,000 in personal injury protection, that’s not nearly enough to qualify for umbrella coverage. You’ll need those higher liability limits.
On the home front, insurers typically require at least $300,000 in liability coverage on your homeowners, renters, or condo policy. This ensures that smaller claims get handled by your primary policy before the umbrella ever needs to step in.
If you own a boat, recreational vehicle, or other assets, there are specific underlying limits for those too. Watercraft usually need $100,000 in coverage for smaller boats and $300,000 for larger vessels. Recreational vehicles typically need $300,000 in coverage.
Here’s something important to know: some insurance companies require that they also write your underlying policies to offer you an umbrella. Others are more flexible. This is where working with an independent agent really pays off.
Why Working With Us Makes This Easier
When you’re shopping for a ny umbrella insurance policy, working with an independent agent like Mitchell-Joseph Insurance Agency gives you some real advantages. We explain how umbrella insurance actually works and how it fits with your existing coverage. We answer all those questions you might feel silly asking (spoiler: they’re not silly questions, and we hear them all the time).
Because we don’t work for just one insurance company, we work for you. With over 200 years of combined experience and relationships with 24 different insurance companies, we can find policies that fit your specific situation perfectly. We know the New York insurance market inside and out, and we use that knowledge to your benefit.
Instead of spending your weekend calling different insurance companies and trying to compare quotes that all look different, we do that work for you. We gather customized quotes from multiple highly rated insurers, compare them side by side, and explain the differences in plain English. No insurance jargon, no confusing fine print – just clear explanations of what you’re getting and what it costs.
How We Help You Get Coverage
Here’s how the process typically works when you come to us for umbrella insurance. We start by looking at your current policies – your auto, home, and any other coverage you have. We check whether they meet the underlying requirements for an umbrella policy. If your current limits are too low, we can help you adjust them.
Then we talk about your life – your assets, your lifestyle, your potential risks. Do you have teenage drivers? Own rental property? Have a pool? These conversations help us figure out how much umbrella coverage makes sense for your situation. A good rule of thumb is to have enough coverage to protect your total assets, including savings, property, investments, and even your future earning potential. More info about if you need umbrella insurance
Once we understand your needs, we leverage our relationships with multiple insurers to get you competitive quotes. We present your options clearly, explain the differences between them, and help you choose the policy that gives you the best protection for your budget.
When you’re ready to move forward, we handle all the paperwork and make sure everything is properly coordinated between your various policies. Then you can relax knowing you have that extra layer of security in place.
The whole process is simpler than most people expect, and we’re with you every step of the way. That’s the benefit of working with a local, family-owned agency that’s been serving the Finger Lakes region for years. We’re not just selling you a policy – we’re building a relationship and protecting what matters most to you.
Securing Your Financial Future in New York
Living in New York means embracing a life where anything can happen. One moment you’re enjoying a peaceful afternoon in your Finger Lakes home, the next you’re dealing with an unexpected accident that changes everything. That’s why securing your financial future isn’t just about saving money or making smart investments—it’s about protecting what you’ve already built.
A ny umbrella insurance policy serves as your financial safety net, catching you when life throws something catastrophic your way. It’s the difference between recovering from a setback and losing everything you’ve worked so hard to achieve.
Debunking Common Umbrella Insurance Myths
Over my years at Mitchell-Joseph Insurance, I’ve heard just about every reason why people think they don’t need umbrella insurance. Let’s set the record straight on some of the most common misunderstandings.
“It’s only for rich people.” This is the biggest myth we encounter, and it couldn’t be further from the truth. Yes, wealthy individuals with multiple properties and significant investments absolutely need umbrella coverage. But here’s what many people miss: if you own a home in Avon, have a retirement account in Canandaigua, or even just a modest savings account, you have something worth protecting.
A lawsuit doesn’t care about your income bracket. A serious accident can happen to anyone—the stay-at-home parent, the teacher, the small business owner. If someone sues you for $800,000 and your homeowners policy only covers $300,000, where does the remaining $500,000 come from? Your savings. Your retirement. Your future wages. A ny umbrella insurance policy protects middle-class families just as much as it protects the wealthy.
“My regular insurance covers everything.” Your auto and homeowners policies are essential, but they weren’t designed to handle everything life can throw at you. Think of them as your first line of defense, not your only defense. Standard policies have limits—often $300,000 to $500,000 for liability coverage. In New York, where medical costs and legal fees run high, those limits can be exhausted quickly.
Beyond just higher coverage amounts, umbrella policies also cover situations your primary policies might exclude entirely. Remember those personal injury claims we talked about—libel, slander, defamation? Your homeowners policy won’t touch those. Your umbrella policy will.
“It costs too much.” Let’s talk numbers. For about $200 per year—less than you probably spend on coffee in a month—you can get $1 million in additional coverage. That’s roughly 55 cents a day to protect everything you own. Compare that to the alternative: paying hundreds of thousands of dollars out of pocket because someone got hurt on your property or your teenager caused a serious accident.
The question isn’t whether you can afford umbrella insurance. It’s whether you can afford not to have it.
Protecting Your Assets with the Right Partner
There’s something deeply comforting about knowing you’re prepared for whatever comes next. That’s what a ny umbrella insurance policy provides—not just financial protection, but genuine peace of mind. You can drive your kids to school, host friends at your home, and live your life without constantly worrying about the “what ifs.”
Here at Mitchell-Joseph Insurance Agency, we’ve been part of the Finger Lakes community for generations. Based right here in Honeoye Falls, we’re your neighbors. We see you at the grocery store in Pittsford, wave to you at community events in Naples, and understand the unique rhythm of life in our corner of New York.
What makes working with us different? We’re an independent, family-owned agency, which means we’re not tied to any single insurance company. We work with 24 different insurers, giving us the flexibility to find the right coverage at the right price for your specific situation. Our team brings over 200 years of combined experience to the table—we’ve seen just about every scenario you can imagine, and we know how to protect against them.
When you call us, you’ll talk to someone who takes the time to understand your life. We’ll ask about your home, your cars, your family, your future plans. We’ll review your current coverage, identify any gaps, and explain your options in plain English. No insurance jargon, no pressure, just honest guidance from people who genuinely care about protecting what matters most to you.
The process is straightforward. We’ll gather quotes from multiple companies, compare them side by side, and help you choose the policy that offers the best value and protection. Then we’ll make sure everything is properly coordinated with your existing coverage, so there are no surprises if you ever need to file a claim.
Your financial security deserves more than a one-size-fits-all approach. It deserves personalized attention from experienced professionals who understand both insurance and your community.
Get a personalized Umbrella Insurance quote today
Let’s have a conversation about protecting your future. Whether you’re in Honeoye Falls, Rushville, or anywhere in the Finger Lakes region, we’re here to help you weather any storm. Reach out to Mitchell-Joseph Insurance Agency today—we’re ready to answer your questions and find the coverage that’s right for you.

