

Why New York Apartment Building Owners Need Specialized Umbrella Coverage Now
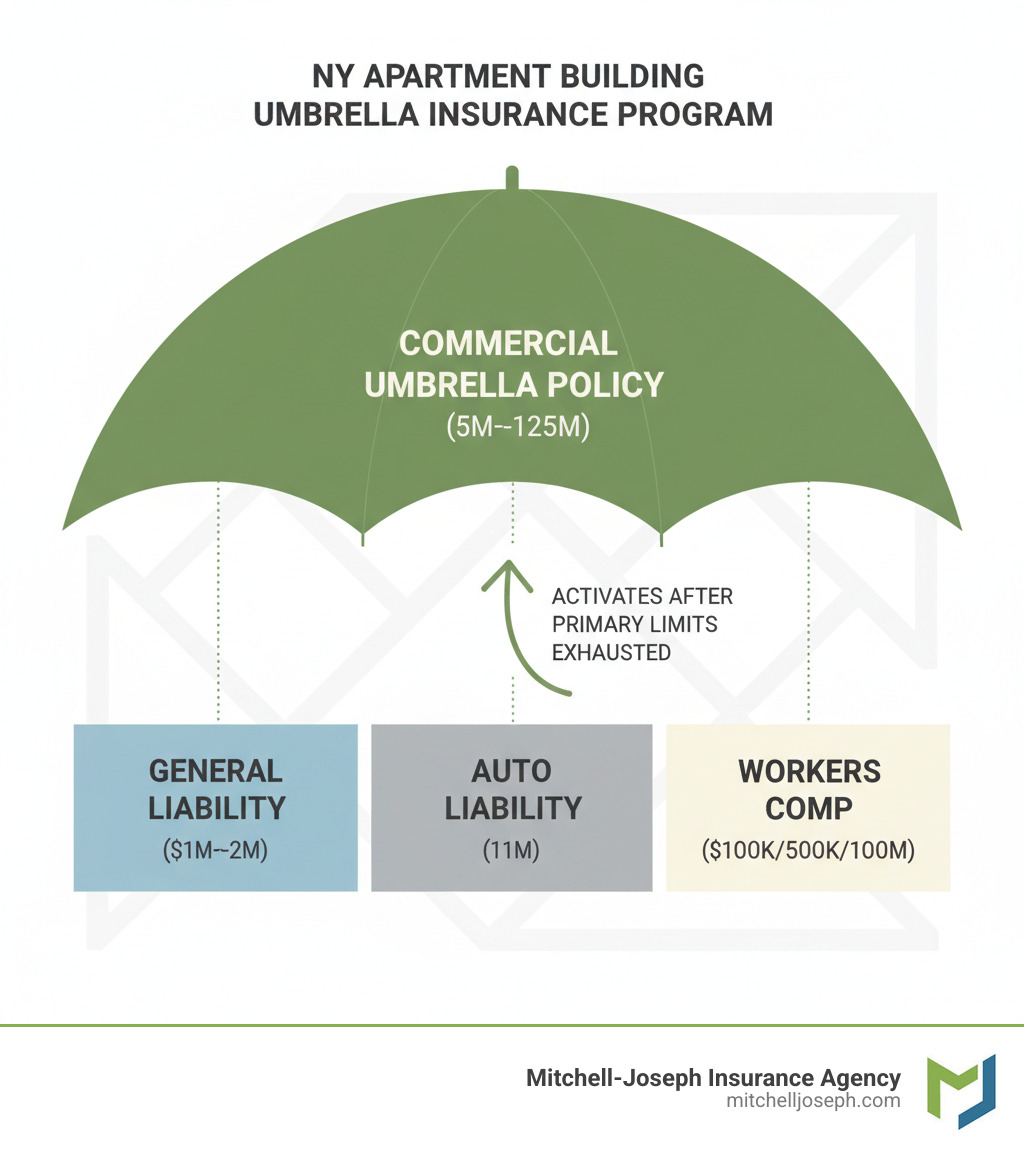
A ny apartment building umbrella insurance program provides liability coverage beyond your primary insurance, protecting your assets from catastrophic lawsuits. In New York’s litigious environment, where jury awards can exceed $9 million and labor laws favor injured parties, this coverage is a critical safety net. When a claim surpasses your general liability, auto, or D&O policy limits, an umbrella policy prevents financial ruin.
Key Features of NY Apartment Building Umbrella Programs:
- Coverage Limits: Typically $5 million to $125 million in additional liability protection.
- Cost: Rates have increased significantly, with a $5 million limit potentially costing $25,000 or more.
- Coverage Scope: Sits above General Liability ($1M/$2M min), Auto Liability ($1M min), and Employers Liability ($100K/$500K/$100K min).
- Property Types: Available for apartments, co-ops, condos, and mixed-use properties.
- Territory: Most national programs exclude New York, making specialized NY-focused programs essential.
The risks are real. A slip and fall on an icy step, a burn from a faulty hot water system, or an assault due to negligent security can lead to massive judgments. Real-world cases have seen awards of $9.5 million and $2.3 million, amounts that would easily exhaust standard policies and threaten your personal assets.
The insurance market has hardened dramatically. Many carriers have left New York, and the remaining ones scrutinize every detail of a property. Furthermore, New York’s labor laws often hold property owners liable for contractor injuries, regardless of negligence. This, combined with social inflation driving up jury awards, makes robust umbrella coverage more necessary than ever.
I’m Jeffrey Joseph, and since 1999, I’ve helped property owners across the Finger Lakes Region secure specialized ny apartment building umbrella insurance programs. At Mitchell-Joseph Insurance Agency, we steer this complex market to find coverage that truly protects your assets.
Understanding the Essentials of a NY Apartment Building Umbrella Insurance Program
In today’s “hard market,” securing adequate liability coverage for New York apartment buildings is more challenging than ever. Premiums are climbing, and many insurers have left the state, making a specialized ny apartment building umbrella insurance program essential. The remaining carriers scrutinize every detail of your co-op, condo, or rental building, from its age to its violation history.
Why Your Building Faces Unique Risks in New York’s Litigious Climate
New York’s reputation as a lawsuit-heavy state presents a genuine threat to apartment building owners. A combination of factors creates a high-risk environment where judgments can easily surpass primary liability limits.
Two major drivers are New York’s harsh labor laws and social inflation. The state’s labor laws can hold property owners responsible for injuries to contractors on their premises, even if the owner was not negligent. Social inflation refers to the trend of rising claim costs due to increased litigation and larger jury awards. We’ve seen a hot water burn case result in a $9.5 million award and a $3 billion class-action lawsuit filed after a tragic fire.
Common high-stakes claims against building owners include:
- Slip and fall incidents on wet floors or icy sidewalks.
- Negligent security lawsuits after a crime occurs on the property.
- Contractor injuries, amplified by the state’s labor laws.
- Tenant disputes over issues like wrongful eviction.
- Health hazards such as mold or lead paint.
A specialized Business Liability Insurance Policy layered with a robust umbrella program is non-negotiable for comprehensive protection.
Umbrella vs. Excess Liability: Choosing the Right Layer of Protection
Understanding the difference between “umbrella” and “excess liability” coverage is crucial. While both provide additional limits, they function differently.
A true umbrella policy is broad. It provides an extra layer of liability protection over multiple underlying policies, such as your General Liability Insurance for Businesses, Commercial Auto, and Employers Liability. Importantly, it can also “drop down” to cover claims that may be excluded by a primary policy, filling potential gaps.
Excess liability insurance is narrower. It typically sits over a single underlying policy, simply increasing its limit without broadening the scope of coverage or filling gaps.
| Feature | Commercial Umbrella Insurance | Excess Liability Insurance |
|---|---|---|
| Breadth of Coverage | Broad: Extends over multiple underlying policies (GL, Auto, EL, D&O) | Narrow: Typically extends over a single underlying policy (e.g., GL) |
| Drop-Down Coverage | Can “drop down” to cover certain claims excluded by primary policies or fill gaps (varies by policy) | Generally does not “drop down” or broaden coverage; simply increases limits |
| Follow Form | Often “follow form” but can also offer broader coverage terms | Primarily “follow form” of the underlying policy |
| Typical Use Cases | Comprehensive protection for diverse, multi-faceted risks of an apartment building | Boosting limits for a specific, high-exposure risk (e.g., general liability for tenant injuries) |
For a New York apartment building with its diverse risks—from tenant injuries to board member lawsuits—a comprehensive ny apartment building umbrella insurance program is the superior choice, offering a more holistic defense.
What Determines the Cost of a NY apartment building umbrella insurance program?
The cost of a ny apartment building umbrella insurance program is complex, with underwriters scrutinizing numerous factors. Key drivers of your premium include:
- Building Age and Condition: Older buildings with outdated systems (plumbing, electrical, roofing) pose a higher risk. Recent upgrades can lower costs.
- Location: Properties in highly litigious areas of New York face higher premiums due to increased liability exposure.
- Claim History: A history of frequent or severe claims will increase your rates. A clean record is a significant advantage.
- Number of Units: More units mean more tenants and visitors, which correlates to higher potential liability.
- DOB/HPD Violations: Unresolved building code violations are a major red flag for insurers and can lead to higher premiums or declination.
- Underlying & Desired Limits: The limits on your primary policies and the amount of umbrella coverage you seek directly impact the cost.
The market has shifted dramatically. A policy that once cost a few thousand dollars can now be $25,000 or more for just a $5 million limit. Rates that were once $500-$1,000 per million of coverage are climbing, making it vital to get competitive Business Insurance Quotes NY from an experienced independent agency.
Securing Your Policy: Requirements and Steps to Lower Premiums
With tighter underwriting standards, improving your building’s risk profile is key to securing a ny apartment building umbrella insurance program at a competitive rate.
Steps to Improve Insurability:
- Proactive Maintenance: Regularly service and upgrade critical systems like roofing, plumbing, and electrical. This demonstrates responsible ownership.
- Clear Violations: Promptly address any Department of Buildings (DOB) or Housing Preservation and Development (HPD) violations, as these are major red flags for underwriters.
- Improve Safety: Implement robust security measures, improve lighting, and maintain common areas to reduce slip-and-fall or negligent security claims.
- Review Underlying Limits: Work with your broker to ensure your primary liability limits are adequate, which can make your umbrella policy more attractive to insurers.
Required Documentation for Application:
To accurately assess your risk, underwriters will require a complete submission package, including:
- A completed commercial real estate umbrella application, like the Distinguished Real Estate Umbrella application (note: many programs exclude NY, so a specialized broker is key).
- A schedule of locations with COPE (Construction, Occupancy, Protection, Exposure) details.
- Five years of currently valued loss runs (claim history reports).
- Declaration pages for all underlying primary policies.
Taking these steps improves your chances of securing robust Landlord Insurance 101: Cover Your Assets and umbrella coverage in the challenging New York market.
Making the Right Choice for Your Property
Choosing the right ny apartment building umbrella insurance program is about more than finding the cheapest premium; it’s about ensuring your investment survives a major lawsuit. This decision directly impacts your long-term financial security.

The Critical Difference Between Commercial and Personal Policies for Landlords
A common and costly mistake is assuming a personal umbrella policy will protect a rental property. It won’t. Personal policies are for personal liability (like a car accident or an incident at your home) and almost always contain a “business venture exclusion.” Because your apartment building is an income-generating business, any claim related to it will be denied under a personal policy.
While forming an LLC is a smart step for asset separation, it is not a substitute for insurance. An LLC creates a legal wall between your business and personal assets. However, if a lawsuit exceeds your primary liability limits, it can bankrupt the LLC, causing you to lose your entire investment property.
The right strategy is to use both. The LLC provides legal separation, while a commercial ny apartment building umbrella insurance program provides the financial protection to defend against catastrophic claims without losing your business. For more on this, see our guides on Business Insurance for Landlords and our Ultimate Landlord Insurance Guide.
The Role of an Independent Broker in Navigating the NY apartment building umbrella insurance program Market
In a hard market where many carriers have withdrawn from New York, navigating the insurance landscape alone is a significant challenge. This is where an independent broker provides critical value.
Unlike captive agents who represent one company, we work for you. At Mitchell-Joseph Insurance Agency, we leverage relationships with 24 different carriers to find specialized programs that still write coverage in New York. Our market access allows us to compare quotes and find the best terms and pricing available. With over 200 years of combined experience, we know which carriers are best suited for your specific property type—be it a co-op, condo, or rental building.
Our process involves a thorough review of your property and risk profile. We then advocate on your behalf to multiple insurers, presenting your property in the best possible light. We don’t just give you numbers; we explain the differences in coverage to help you make an informed decision.
As a family-owned business in Honeoye Falls, we serve the entire Finger Lakes Region—including Pittsford, Naples, Rushville, Avon, Bloomfield, Bristol, Canadice, Canandaigua, Cohocton, Fishers, Gorham, Honeoye, Ionia, Lima, Mendon, Middlesex, Potter, Rochester, Rush, South Bristol, Stanley, Victor, Wayland, and West Bloomfield. We understand the local risks and know the carriers willing to write business here. Our goal is to ensure your investment is properly protected.
Don’t leave your property exposed to a catastrophic lawsuit. Explore our Umbrella Insurance options today and secure your peace of mind.

