

Local homeowners insurance agents are pivotal when it comes to ensuring that your home and personal belongings are adequately protected. If you’re trying to find the perfect balance between comprehensive coverage and personalized service, a local agent might be just what you need. Here’s a quick look at why choosing a local agent is a smart move:
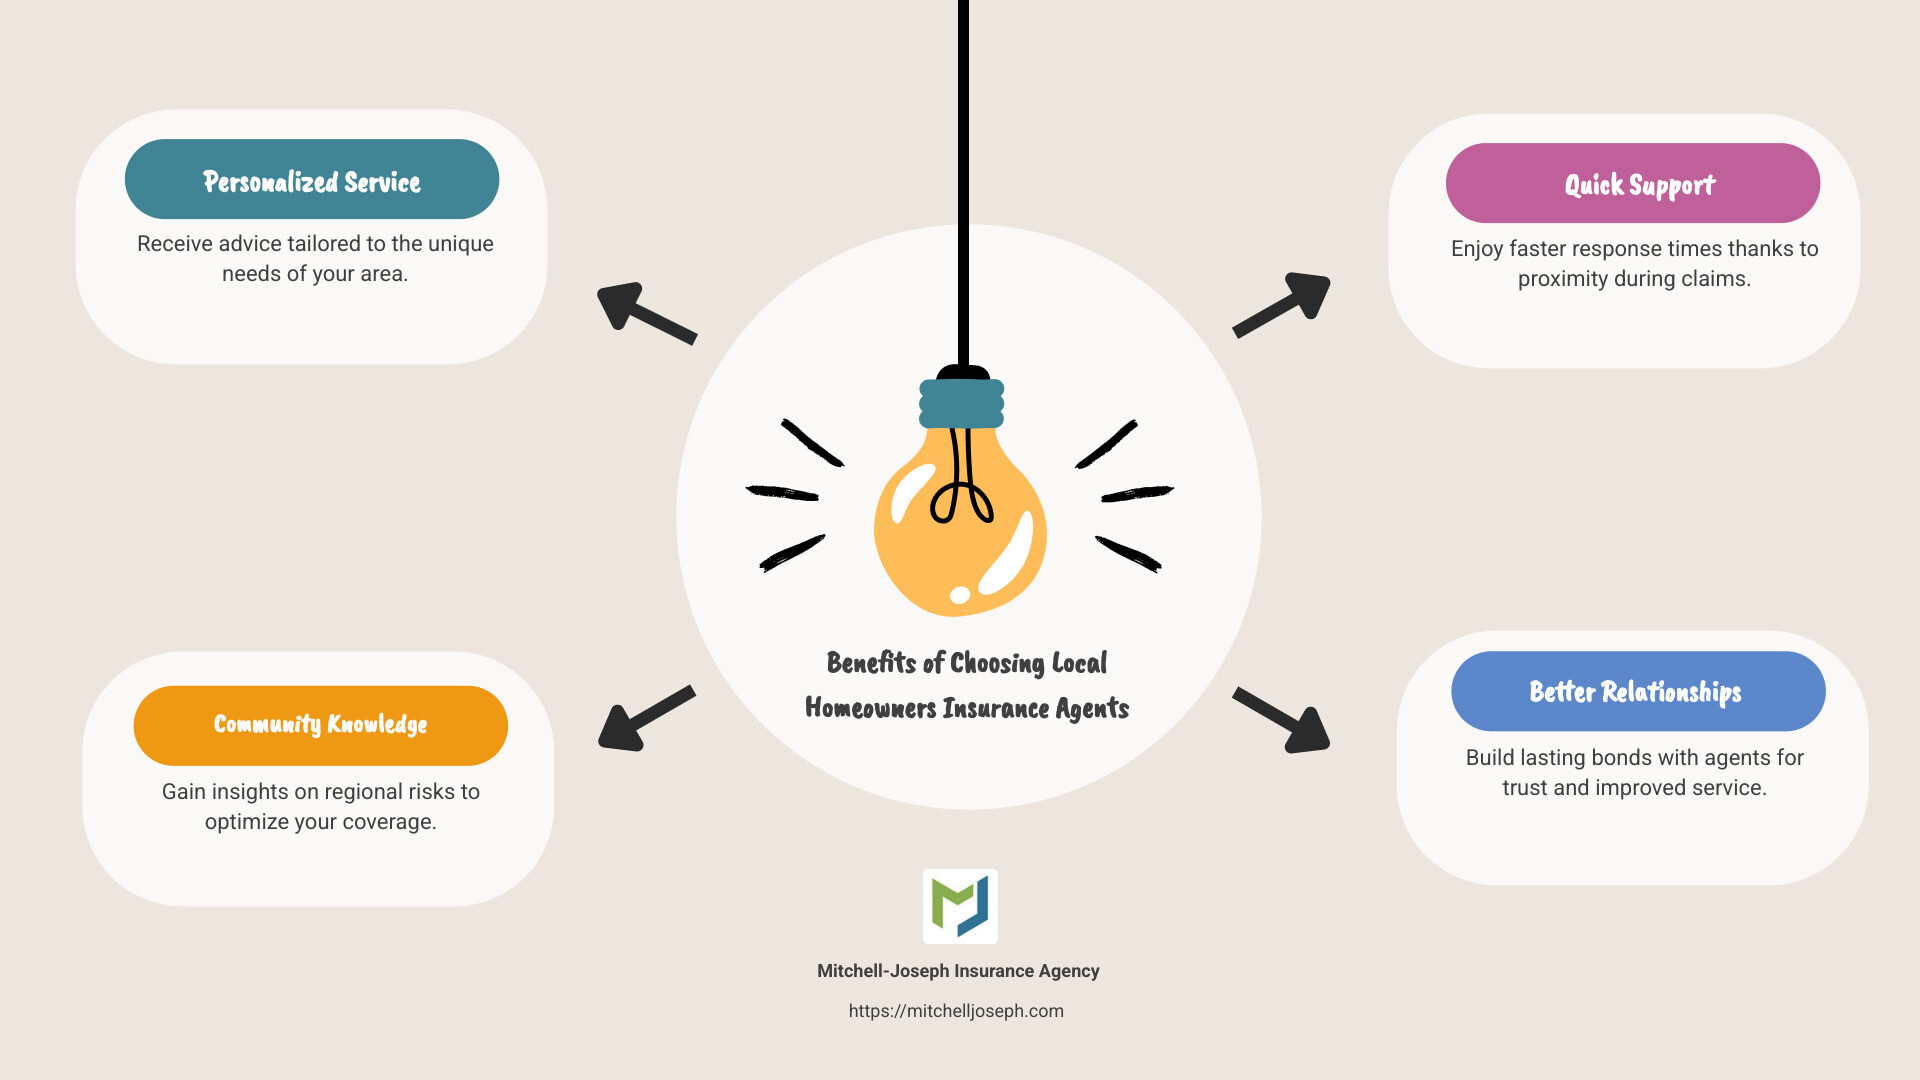
- Personalized Service: Local agents understand the unique needs of your area and offer custom advice.
- Community Knowledge: Their insights on regional risks can help optimize your coverage.
- Quick Support: Proximity ensures faster response times, crucial during claims.
- Better Relationships: Building a lasting bond with a nearby agent often leads to better service and trust.
Choosing the right insurance begins with understanding these benefits, ensuring your home is covered against the unexpected while supporting a neighbor who values your relationship.
My name is Jeffrey Joseph, and with my decades of experience in the insurance industry, I’ve seen how Local homeowners insurance agents play a crucial role in community protection. At Mitchell-Joseph Insurance, we pride ourselves on understanding and meeting the unique needs of our clients.
Related content about Local homeowners insurance agents:
– Home insurance coverage types
– Homeowners insurance discounts
– Insurance for new homeowners
Benefits of Choosing Local Homeowners Insurance Agents
When it comes to choosing a local homeowners insurance agent, there are several compelling benefits that go beyond just securing a policy. Let’s explore why this choice can be advantageous for you and your community.
Boosting the Local Economy
Selecting a local insurance agent means you’re supporting your community’s economy. These agents are small business owners who contribute to the economic health of your area. By choosing them, you help keep money within your community, supporting local jobs and services.
Personalized Service
Local agents provide a level of personalized service that is hard to match. They understand the specific needs and risks associated with your area. This means they can tailor insurance solutions that fit your unique situation. When you work with someone who knows your neighborhood, you get advice that’s relevant and timely.
Community Involvement
Many local insurance agents are deeply involved in their communities. They sponsor local events, participate in community service, and are often seen as trusted advisors. This involvement means they have a vested interest in the well-being of the community they serve. When you choose a local agent, you’re partnering with someone who cares about the same things you do.

Quick and Efficient Support
Proximity matters. A local agent can provide quick support when you need it most. Whether it’s a question about your policy or assistance during a claim, having someone nearby ensures faster response times. This can be particularly crucial during emergencies when every minute counts.
Building Strong Relationships
A local agent is not just a business contact; they can become a trusted partner. Over time, you’ll build a relationship based on trust and understanding. This can lead to better service, as your agent will have a deeper insight into your needs and preferences.
In conclusion, choosing a local homeowners insurance agent offers tangible benefits that go beyond just insurance coverage. It’s about community support, personalized service, and building lasting relationships. As you consider your options, remember these advantages and how they align with your values and needs.
Understanding Homeowners Insurance Coverage
Navigating homeowners insurance can feel overwhelming, but breaking it down into key components makes it manageable. Let’s explore the essentials: coverage needs, liability limits, and replacement value.
Coverage Needs
Homeowners insurance is not a one-size-fits-all solution. Your coverage needs depend on several factors, such as the value of your home, its contents, and your personal circumstances.
-
Dwelling Coverage: This covers the cost to rebuild your home if it’s destroyed by a covered peril, like fire or wind. The amount should reflect the cost to rebuild, not the market value of your home.
-
Personal Property Coverage: This protects your belongings, like furniture and electronics. Typically, it covers 50% to 70% of your dwelling coverage. For high-value items, consider adding riders for extra protection.
-
Additional Living Expenses (ALE): If your home becomes uninhabitable due to a covered event, ALE covers the cost of living elsewhere temporarily.
Liability Limits
Liability coverage is crucial. It protects you against lawsuits for injury or property damage that you or your family members cause to others.
-
Standard Liability Coverage: Most policies offer $100,000 in liability coverage, but experts recommend at least $300,000. This covers medical bills, legal fees, and settlements.
-
Umbrella Policies: For more extensive protection, consider an umbrella policy. It provides additional liability coverage beyond the limits of your homeowners policy.
Replacement Value
Understanding replacement value is key to ensuring you’re adequately covered.
-
Actual Cash Value (ACV): This option covers the cost to replace your home and belongings minus depreciation. It results in lower premiums but may leave you with out-of-pocket expenses.
-
Replacement Cost: This covers the cost to rebuild your home or replace belongings at current prices, without depreciation. It offers more comprehensive protection and peace of mind.
-
Extended Replacement Cost: This option provides additional coverage, typically 20% to 25% above your policy limits, to account for unexpected increases in construction costs.
Knowing these elements helps you make informed decisions about your homeowners insurance coverage. Tailor your policy to fit your needs, and ensure you’re protected against life’s uncertainties.
Next, we’ll discuss how to evaluate and select the right agent for your insurance needs.
How to Evaluate and Select the Right Agent
Choosing the right local homeowners insurance agent is crucial for getting the best coverage custom to your needs. Here are some key steps and questions to help you find the perfect fit.
Questions to Ask
When meeting with potential agents, asking the right questions can make all the difference. Here are some essential queries:
- What type of coverage do I need?
Ensure the agent understands your specific needs. They should be able to recommend the right mix of dwelling, personal property, and liability coverage based on your situation.
- How do deductibles affect my rate, and when do they apply?
Understanding deductibles is crucial. Higher deductibles usually mean lower premiums, but you’ll pay more out-of-pocket in the event of a claim. Ask your agent to explain the trade-offs.
- Am I eligible for any insurance discounts?
Discounts can significantly lower your premium. Common discounts include those for bundling multiple policies, installing safety features, or maintaining a claims-free history. Make sure your agent identifies all applicable discounts.
Evaluating Deductibles
Deductibles are the amount you pay out-of-pocket before your insurance kicks in. Here’s what to consider:
-
Standard Deductibles: Typically range from $500 to $2,500. Choosing a higher deductible can lower your premium but increases your financial responsibility in a claim.
-
Percentage Deductibles: Some policies, especially in areas prone to natural disasters, use percentage deductibles based on the home’s insured value. Understand how these work to avoid surprises.
Insurance Discounts
Maximize your savings by taking advantage of available discounts. Here are some common ones:
-
Multi-Policy Discounts: Save by bundling your homeowners and auto insurance with the same provider.
-
Safety and Security Discounts: Installing smoke detectors, burglar alarms, or storm shutters can qualify you for discounts.
-
Loyalty Discounts: Some insurers offer reduced rates for long-term customers. Ask if this is an option.
Evaluating and selecting the right local homeowners insurance agent involves asking the right questions, understanding deductibles, and leveraging discounts. By following these steps, you’ll find an agent who can provide the personalized service and coverage you need.
Next, we’ll tackle some frequently asked questions about working with local homeowners insurance agents.
Frequently Asked Questions about Local Homeowners Insurance Agents
Is it better to use a local insurance agent?
Absolutely! Local homeowners insurance agents offer personalized service that you simply can’t get from a national hotline. They understand the specific needs and risks of your area. For example, if you live in Honeoye Falls, NY, a local agent will know the common regional risks like heavy snow or flooding and tailor your policy accordingly.
Moreover, local agents can provide excellent claim assistance. When disaster strikes, having someone nearby who can guide you through the claims process can make a stressful situation much more manageable.
What is the 80% rule in homeowners insurance?
The 80% rule is a critical concept to grasp. It means that your insurance will only fully cover damage if your policy covers at least 80% of your home’s replacement value. For example, if your home is valued at $200,000, your policy should cover at least $160,000. If not, you might end up paying a significant portion of repair costs out of pocket.
Understanding this rule helps ensure you’re neither underinsured nor overpaying for unnecessary coverage. Always discuss this with your local agent to ensure your policy meets these coverage requirements.
Is it cheaper to go through an insurance agent?
Many people assume that skipping the middleman will save money, but that’s not always the case. Independent agents can often find better deals because they have access to multiple insurance providers, not just one. This means they can shop around for the best policy options and rates custom to your needs.
While agents do earn commissions, the savings they can find through discounts and bundled policies often outweigh their fees. Plus, the personalized advice and assistance they provide add significant value, making them a wise choice for most homeowners.
Choosing a local homeowners insurance agent can lead to better coverage, personalized service, and potentially lower costs. Next, we’ll conclude with how Mitchell-Joseph Insurance Agency can offer you these benefits.
Conclusion
At Mitchell-Joseph Insurance Agency, we pride ourselves on offering personalized service and custom coverage that fits your needs. Our team, with over 200 years of combined experience, is dedicated to ensuring you have the right protection for your home, especially in areas like Honeoye Falls, NY, where local knowledge is crucial.
Why choose us?
-
Custom Coverage: We understand that no two homes are the same. That’s why we offer customized policies to ensure you’re covered for the unique risks in your area, whether it’s heavy snow, flooding, or anything else nature throws your way.
-
Personalized Service: Being a family-owned business, we value relationships. We take the time to get to know you and your needs, offering guidance and support every step of the way. From selecting the right policy to navigating the claims process, we’re here for you.
-
Competitive Quotes: As independent agents, we have access to 24 different insurance companies. This means we can shop around to find you the best coverage at the most competitive rates, ensuring you get the best value for your money.
When you choose Mitchell-Joseph Insurance Agency, you’re not just getting an insurance policy; you’re getting a partner in protecting your home.
Explore our homeowners insurance options today and let us help you find the perfect coverage for your peace of mind.

