

Understanding Your Hidden Homeownership Risk
Is exterior water and sewer line insurance worth it? For most homeowners in older properties (pre-1970) with mature trees, it’s a smart investment—costing just $20-$50 annually while protecting against repair bills that can exceed $20,000. However, if you own a newer home with savings set aside for emergencies, you may not need this coverage.
Quick Answer:
| You Probably Need It If: | You Probably Don’t Need It If: |
|---|---|
| Your home was built before 1970 | Your home is less than 20 years old |
| You have large trees on your property | You have substantial emergency savings ($5,000+) |
| Your water main is 50+ years old | Your neighborhood has no history of line failures |
| You lack emergency repair funds | You’re comfortable self-insuring |
Here’s what many upstate New York homeowners don’t realize: you’re responsible for the underground pipes running from the street to your house. When these lines fail—a common issue during our harsh freeze-thaw cycles—you’re on the hook for repair bills that can devastate a budget. The worst part? Your standard homeowners insurance won’t cover a penny of it.
I’m Jeffrey Joseph, and I’ve been helping homeowners in the Finger Lakes region steer questions about is exterior water and sewer line insurance worth it since 1999 through Mitchell-Joseph Insurance Agency. I’ve seen how a $50 annual premium can save families from financial disaster when their 1960s cast iron pipes finally give out.
Evaluating the Risks: Is Exterior Water and Sewer Line Insurance Worth It?
It’s a question that often arises when a letter from a utility company or an unexpected plumbing issue sparks concern: is exterior water and sewer line insurance worth it? To answer that, we need to understand what this coverage entails and the true financial impact of a pipe failure.
What’s Covered vs. What’s Not?
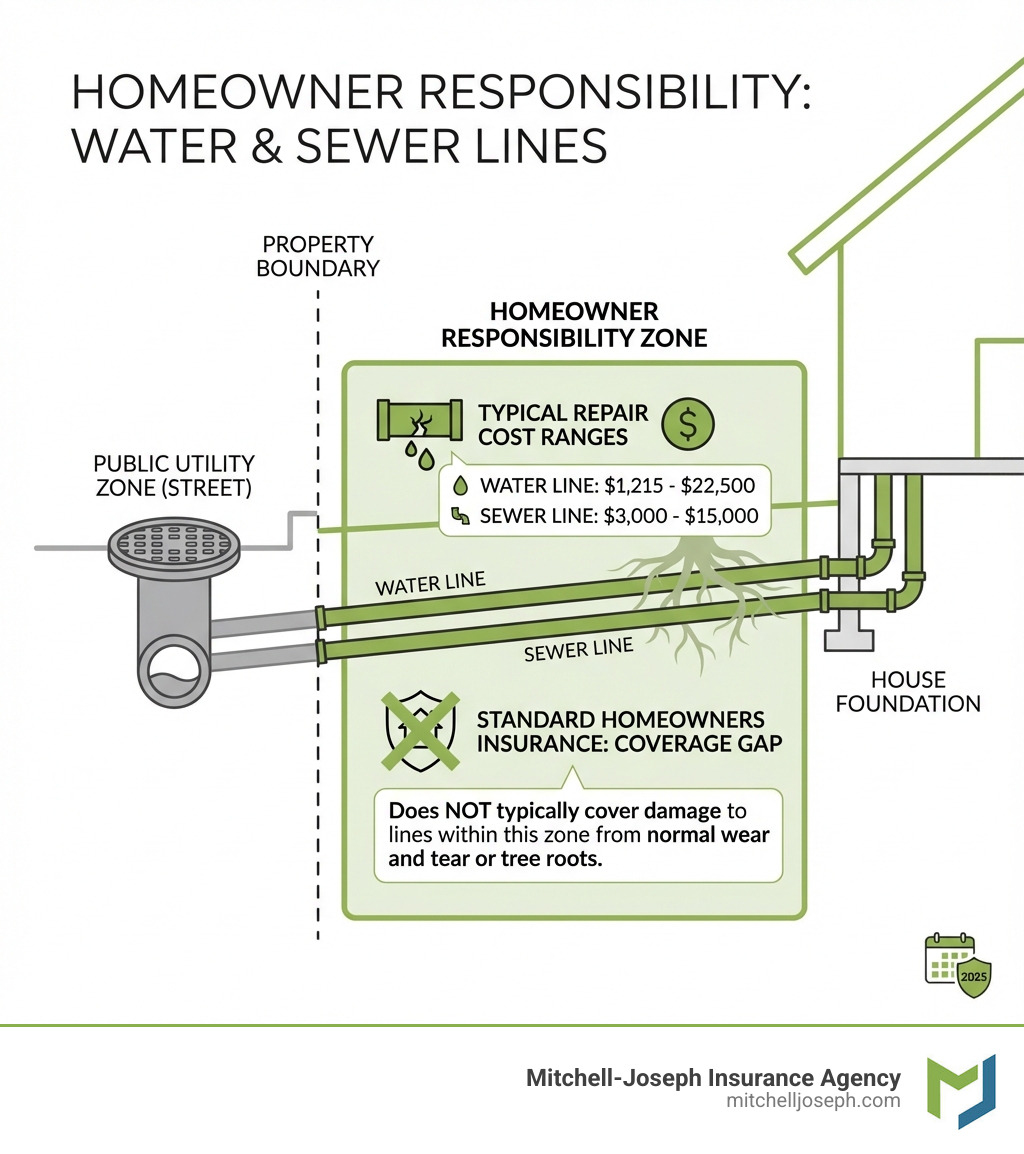
Your standard homeowners insurance almost never extends to the underground service lines outside your home’s foundation. It protects against water damage inside your home, but the moment that pipe goes underground, it’s generally outside the bounds of standard coverage. This is a crucial “coverage gap” many homeowners find during a crisis.
Exterior water and sewer line insurance, or service line coverage, is an add-on that protects you from the cost of repairing or replacing the pipes that bring fresh water to your home and carry wastewater away.
Here’s what it typically covers:
- Repair or replacement of damaged underground utility lines on your property (water, sewer, gas, electric, etc.).
- Damage from common causes like wear and tear, leaks, root invasion, corrosion, and freezing.
- Excavation costs to access the damaged line.
- Landscaping restoration for property, driveways, or walkways disturbed during the repair.
- Temporary living expenses if the damage makes your home uninhabitable.
However, service line coverage generally won’t pay for:
- Pre-existing damage or issues arising during an initial waiting period (often 30 days).
- Above-ground lines or interior plumbing.
- Separate systems like water wells, septic systems, or fuel tanks.
- Damage from negligence or lack of maintenance.
- Certain natural disasters like floods or earthquakes, depending on the policy.
Understanding these distinctions is the first step in deciding if this specialized coverage is right for your home in Honeoye Falls, Canandaigua, or anywhere else in our Finger Lakes communities.
The True Cost of a Broken Pipe
A broken pipe isn’t just an inconvenience; it’s a potential financial nightmare. The numbers speak for themselves:
- The average cost to replace your main water line is around $3,750.
- Replacing a sewer line costs about $3,200 on average, but can easily climb much higher.
These are just averages. A simple 10-foot PVC water line replacement might cost around $1,215, but a worst-case scenario involving a 100-foot copper pipe could set you back up to $22,500. Sewer line repairs often range from $3,000 to $15,000, depending on the severity and location.
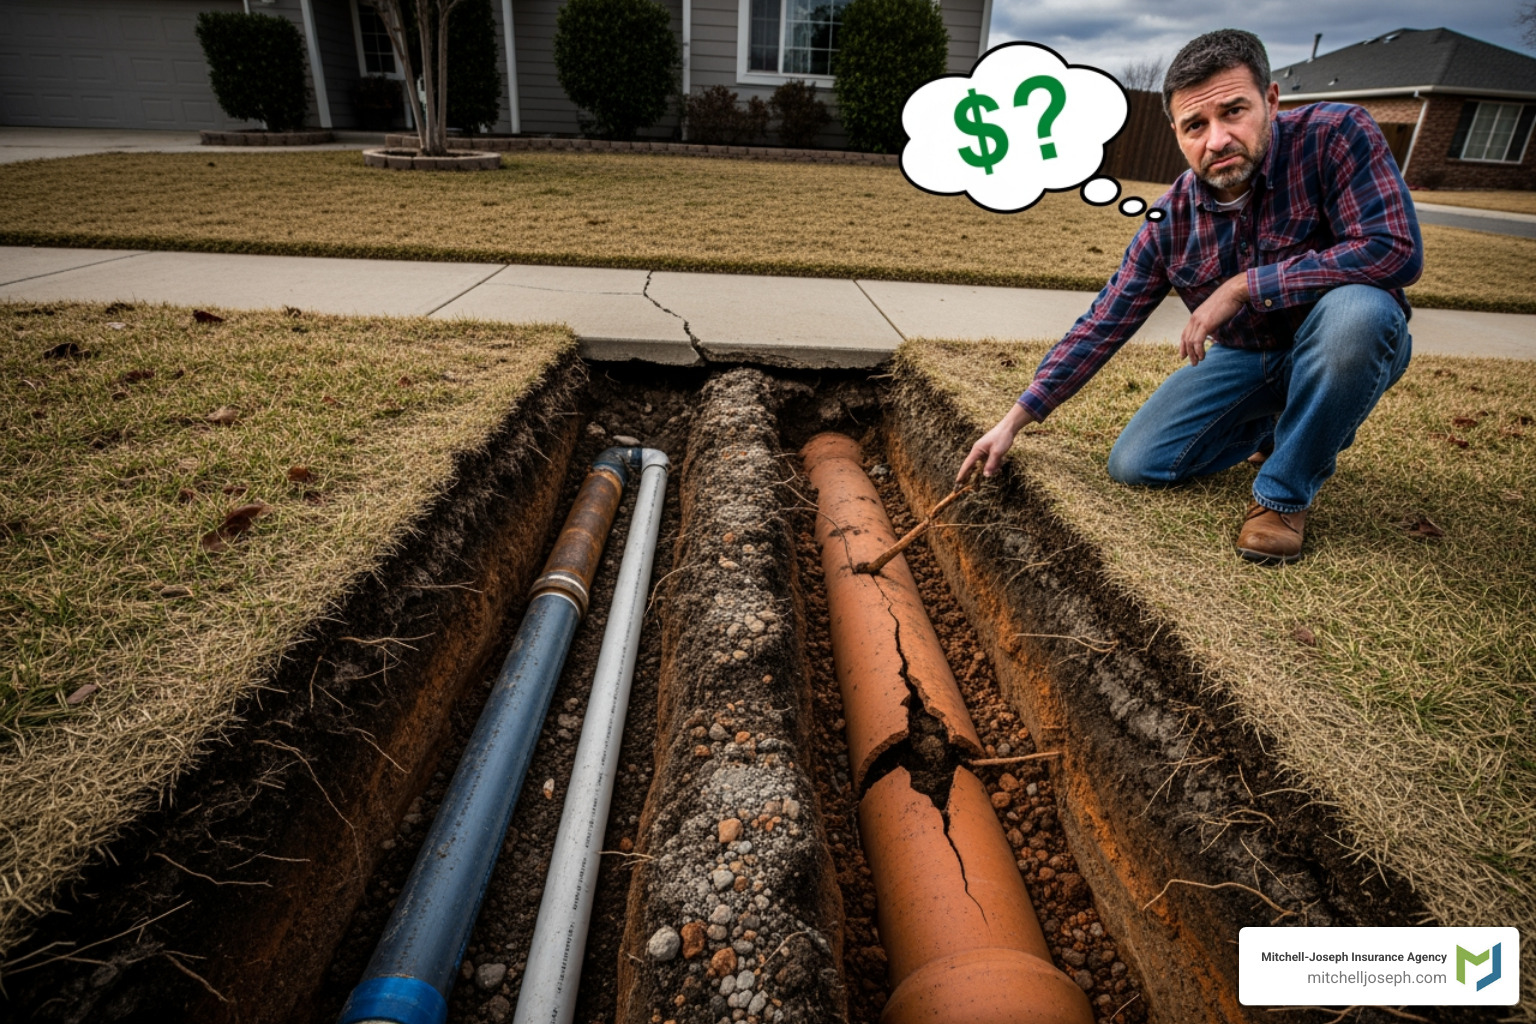
What causes these underground headaches?
- Aging Pipes: Water service lines typically last about 50 years. In older communities like Rochester and Bloomfield, many homes built before 1970 have original pipes that are prime candidates for failure.
- Tree Root Intrusion: Large, mature trees have roots that seek water, often infiltrating and breaking sewer or water lines. This is a significant risk for properties in Mendon or Rush.
- Freeze-Thaw Cycles: Our harsh Upstate NY winters cause ground shifting that puts immense stress on underground pipes, leading to cracks and breaks.
- Gradual Corrosion: Over decades, pipes made of certain materials can corrode, weakening their structure and leading to leaks or collapses.
- Construction or Landscaping Work: Any significant ground disturbance on your property, from a new patio in Canandaigua to foundation work in Avon, can damage buried lines.
For a modest annual premium, you can shield yourself from these unexpected expenses.
Factors to Consider for Your Home
Deciding whether is exterior water and sewer line insurance worth it boils down to a personalized risk assessment. Here are the key factors we encourage our clients in Naples, Lima, and beyond to consider:
-
Age of Your Home and Pipes: This is the most critical factor. If your home was built before 1970, your risk is much higher, as water service lines typically last about 50 years. Copper pipes last 50+ years, while modern PVC can last 75+ years. If you’re unsure of your pipe’s age or material, it’s worth investigating.
Pro Tip: Ask neighbors in older areas like Honeoye Falls or Pittsford if they’ve had line replacements. A trend on your street is a strong indicator of future repairs for you.
-
Presence of Large Trees: The roots of beautiful, mature trees in Victor or West Bloomfield are relentless in their search for water and can easily break pipes, especially sewer lines.
-
Pipe Materials: Older homes might have cast iron or galvanized steel pipes, which are less durable than the PVC or copper found in newer homes. PVC costs about 50 cents to $5 per foot, while durable copper runs $20 to $30 a foot.
-
Neighborhood History: If multiple homes on your street have had water or sewer line issues, it’s a strong sign that the infrastructure in your area is aging.
-
Climate Impact: Here in Upstate NY, our severe freeze-thaw cycles put immense pressure on pipes, making them more prone to cracking and shifting.
-
Your Emergency Fund: If you have substantial emergency savings ($5,000+) and your home is low-risk, you might feel comfortable self-insuring. However, if an unexpected $3,750 or $15,000 repair bill would be a strain, the modest annual cost of insurance is an attractive alternative.
For tips on building an emergency fund, check out the AARP Money Map.
Making an Informed Decision on Coverage
Now that we’ve evaluated the risks, let’s talk about the solutions. If you’ve determined that your home is at a higher risk, or if the peace of mind alone is worth the investment, then exploring coverage options is your next step.
How Much Does Coverage Cost and Where Can You Get It?
One of the most appealing aspects of exterior water and sewer line insurance is its affordability, especially when compared to the potential repair costs.
- As an add-on to your homeowners policy: This is often the most cost-effective and comprehensive option, typically ranging from $20 to $50 per year.
- Through utility-offered plans: Many utility companies partner with third-party warranty providers to offer plans. These can range roughly from $60 to $96 per year ($4.99-$7.99 monthly) but may have lower coverage limits.
- Home warranty service line coverage: Standalone home warranty companies also offer service line coverage, typically costing approximately $30-$100 annually.
At Mitchell-Joseph Insurance Agency, we specialize in finding the best solutions for our clients in Cohocton, Gorham, and throughout the Finger Lakes. We can help you explore options to add this vital protection to your existing homeowners policy. You can learn more on our Water Line Insurance page.
When considering a policy, pay attention to:
- Deductibles: This is the amount you pay out of pocket before insurance kicks in, typically $500-$1,000 for this type of add-on.
- Coverage Limits: Policies have a maximum payout per incident. You’ll want a policy with at least $10,000 in coverage, with many offering $10,000-$15,000.
Water Line vs. Sewer Line: Should You Bundle?
Water and sewer lines serve distinct functions and face different problems. Water lines bring fresh water in and are prone to corrosion and freezing. Sewer lines carry wastewater away and are more susceptible to tree root intrusion and collapse.
Given these distinct risks, should you purchase separate policies or a combo plan? We almost always recommend a combo plan. You’ll typically save money, and the price difference is often small. As a client in Canandaigua noted, it was an easy choice to protect both lines when it was only $12 more per year.
This comprehensive protection offers true peace of mind. You can explore more about this specialized coverage on our Sewer Line Insurance page.
So, Is Exterior Water and Sewer Line Insurance Worth It? The Final Verdict
The decision of is exterior water and sewer line insurance worth it comes down to your personal risk tolerance and financial preparedness. For many homeowners in the Finger Lakes region, particularly those in older homes or with mature trees, we believe it makes tremendous sense.
Here’s our summary:
| Homeowner Profile | Is it Worth It? | Why? |
|---|---|---|
| High-Risk Homeowners (Older homes, mature trees, limited emergency funds, neighborhood history of issues) | YES, absolutely. | The cost of a policy ($20-$50/year) is a tiny fraction of potential repair bills ($1,200-$22,500). It offers invaluable peace of mind and prevents financial hardship. |
| Low-Risk Homeowners (Newer homes, no large trees, substantial emergency savings) | Probably NOT necessary. | With a new home and a robust emergency fund, you’re well-positioned to handle unlikely repairs yourself. |
A client in Honeoye Falls once told us, “I never thought about my water line until it broke—then I couldn’t think about anything else for days. I wish I’d gotten the coverage sooner.” That sentiment perfectly captures the value of this often-overlooked protection.
We at Mitchell-Joseph Insurance Agency understand the unique challenges faced by homeowners across our communities, from Stanley to Rushville, and we’re here to help you steer these decisions. We offer personalized quotes and expert advice to ensure you have the right coverage for your specific situation.
To learn more about protecting your home’s critical underground connections and to get a personalized quote, please visit our comprehensive guide on Service Line Coverage Complete Guide. We’re dedicated to helping you find peace of mind and protect your most valuable asset.

