Why Home Insurance Rochester Matters for Homeowners
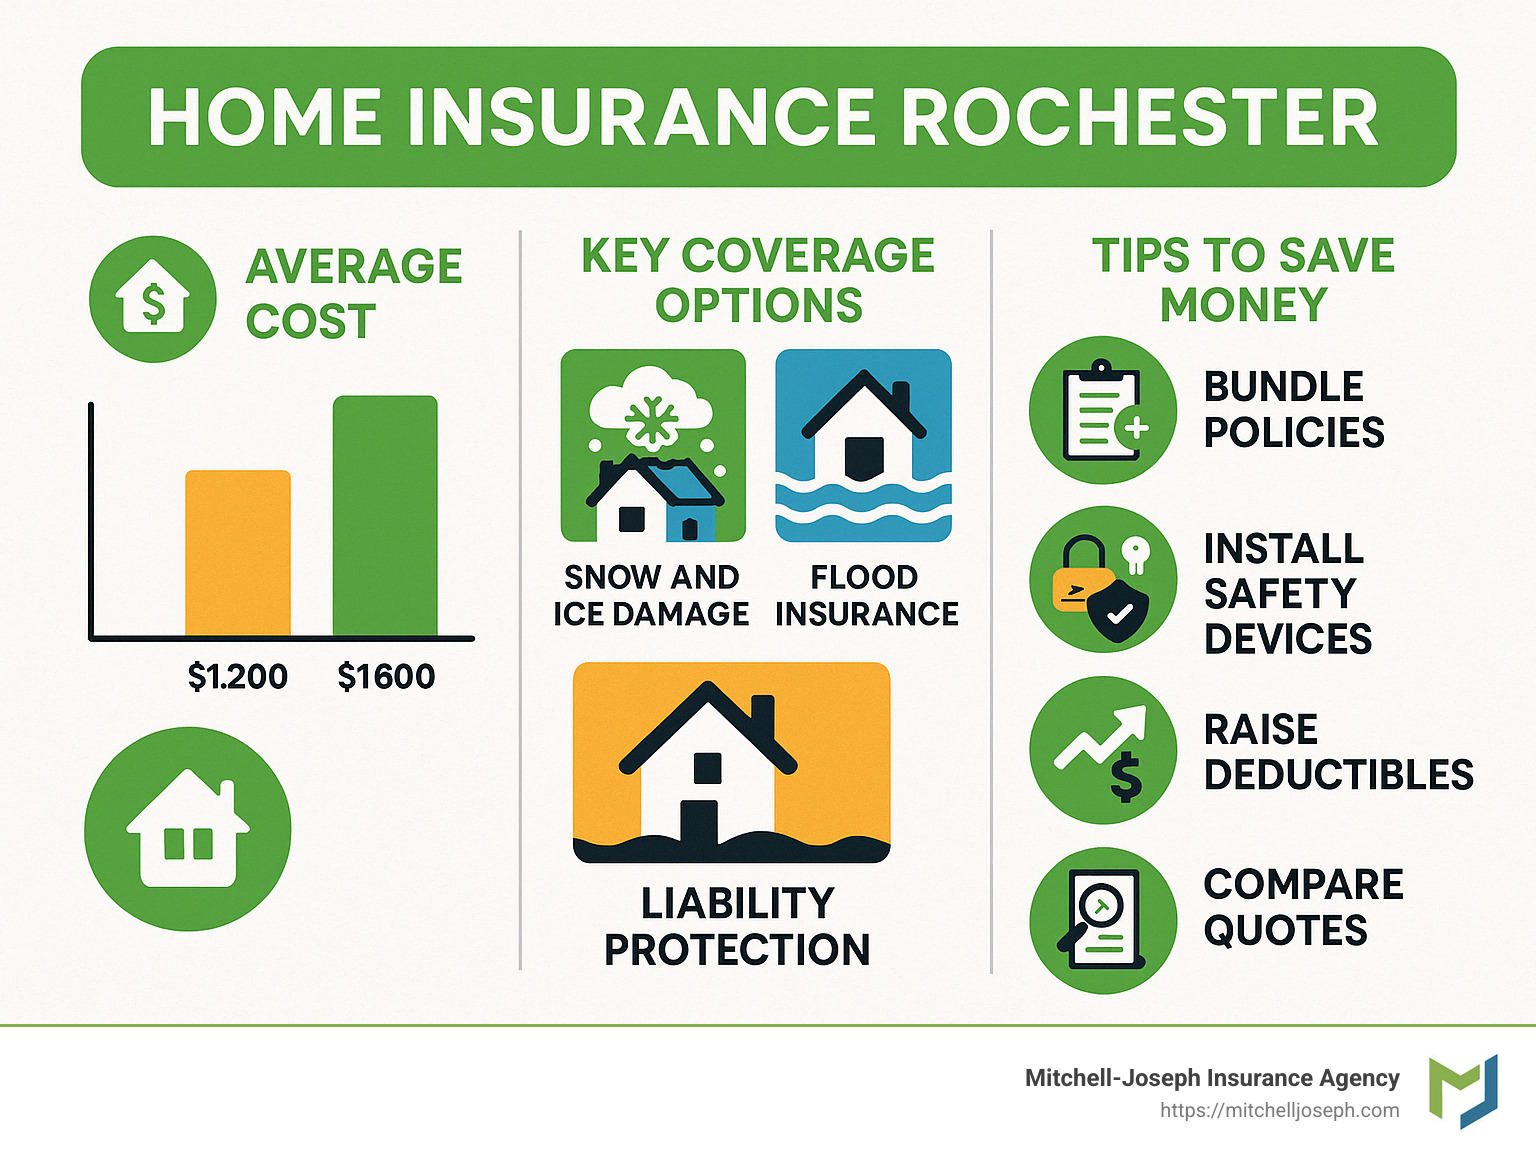
Home Insurance Rochester is essential for protecting your biggest investment against harsh winters, snowfall of up to 120 inches, flooding risks, and property crime in the area. Here’s a quick snapshot to help you compare options:
- Average annual cost: $1,524 (vs. national average $2,377)
- Cheapest insurer: Ocean Harbor Casualty (~$402 per year)
- Top bundling discount: Up to 35% savings with New York Central Mutual Insurance
- Important coverages: Snow and ice damage, flood insurance, liability protection
- Savings tips: Bundle policies, install safety devices, raise deductibles, compare quotes regularly
As a Rochester homeowner, having the right home insurance isn’t optional—it’s crucial to safeguarding your family’s financial security and peace of mind.
My name is Jeffrey Joseph. As the owner of Mitchell-Joseph Insurance Agency, I’ve spent over 20 years providing personalized Home Insurance Rochester solutions to protect families and their homes across the region.
Understanding Home Insurance in Rochester
When you’re making a home in Rochester, you quickly realize that home insurance isn’t just paperwork for your mortgage company—it’s your best protection against the unexpected. At Mitchell-Joseph Insurance Agency, we’ve been guiding Rochester homeowners for years, helping them understand exactly what their Home Insurance Rochester policy covers, and why that’s important.
Here in Rochester, we face some unique challenges. From winter storms dumping up to 120 inches of snow each year, to seasonal flooding and property crimes, insurance coverage custom to our specific risks is a must. Thankfully, a standard homeowners policy provides several essential protections that help you sleep better at night.
Your first priority is Dwelling Coverage, which protects the building itself. This coverage pays to repair or fully rebuild your home if it’s damaged by events like fires, windstorms, vandalism, or even ice damage—a common concern during our harsh winters. Because local Rochester building codes and materials can make rebuilding costly, it’s smart to carry enough dwelling coverage to fully reconstruct your home from the ground up.
Next up is Personal Property Coverage, which protects the belongings inside your home. Your furniture, electronics, clothing, appliances, and other possessions are covered if they’re damaged or destroyed by a covered event. There are limits on certain valuables—so if you have an expensive art collection or jewelry, you may need additional coverage to fully protect those items.
Another critical component is Liability Protection. Suppose someone slips on your icy driveway (a genuine Rochester winter hazard!) and gets injured. Liability coverage protects you from costly lawsuits and legal fees. We typically recommend at least $300,000 in liability coverage, although many Rochester homeowners choose higher limits for added peace of mind.
Your policy will also include coverage for Additional Living Expenses—this helps pay for temporary housing, meals, and other costs if your home is damaged by a covered event and becomes unlivable. Given Rochester’s tight rental market, this coverage can be a lifesaver during an emergency.
Here at Mitchell-Joseph Insurance Agency, our team has over 200 years of combined experience helping Rochester families steer their home insurance needs. We know that the right coverage can make all the difference when disaster strikes.
Key Coverage Types in Home Insurance Rochester
When exploring your options for Home Insurance Rochester, it’s helpful to understand exactly how different coverages work together to protect you financially.
Your Dwelling Coverage is the backbone of your policy, paying to repair or rebuild your home’s structure if disaster strikes. According to experts, you should aim for coverage levels that meet at least 80% of your home’s replacement cost. In Rochester, rebuilding costs can run high due to local building codes and climate conditions, so we recommend insuring your dwelling for the full estimated replacement cost.
Personal Liability Coverage steps in if someone is injured or their property is damaged while visiting your home. Winter weather in Rochester increases the risk of slips and falls, so adequate liability coverage is vital. Most local homeowners carry at least $300,000, but you might feel more secure with higher limits, particularly if you frequently have guests.
When incidents happen that require immediate medical attention, Medical Payments Coverage offers quick relief. This coverage pays medical bills right away, no matter who’s at fault, typically ranging from $1,000 to $5,000.
Finally, Loss of Use Coverage covers costs if your home becomes temporarily uninhabitable. It pays for things like hotel stays, meals out, and even laundry expenses until your home is repaired. Considering the limited rental options in the Rochester area, this coverage can provide essential peace of mind.
At Mitchell-Joseph Insurance Agency, we partner with 24 different insurance providers. This allows us to compare policies and find the perfect coverage package custom specifically for Rochester’s unique risks and your family’s needs. Check out this detailed guide on Home Insurance Coverage Types for more helpful information.
Tailoring Your Home Insurance Rochester Policy
Every Rochester home has its own character—and that means your insurance should be just as unique. Tailoring your Home Insurance Rochester policy with the help of a local agent ensures you’re fully protected without paying for coverage you don’t need.
The first step to customizing your policy is understanding exactly what you have to protect. It’s a good idea to start with a detailed home inventory, including photos and estimated values of your belongings. Next, take note of any special features in your home, like expensive collections, high-end appliances, or custom-built additions. These might require specialized coverage.
You’ll also want to evaluate local risks based on your neighborhood. In some Rochester areas, flooding from snowmelt is a significant concern, making flood insurance especially important. In other neighborhoods, higher property crime rates could mean you need additional personal property protection or security device discounts.
Working with a local, independent agent makes a big difference. At Mitchell-Joseph Insurance Agency, our team lives and works right here in the Rochester area, from Honeoye Falls and Pittsford to downtown neighborhoods. We know which risks are most common in each community. Learn more about working with Local Homeowners Insurance Agents who understand your needs.
For instance, a Rochester homeowner recently came to us surprised to learn that her valuable art collection wasn’t fully covered by her standard policy. We helped her add a scheduled personal property endorsement, ensuring her artwork had proper protection.
This personalized approach is exactly why Rochester homeowners choose local agents like us—because your insurance should reflect your life, your home, and Rochester’s unique personality.
Average Cost of Home Insurance in Rochester
If you’ve ever wondered whether you’re paying too much (or hopefully, just right!) for your Home Insurance Rochester policy, you’re not alone. Understanding typical insurance costs in our area can help you feel more confident in the value of your coverage.
On average, homeowners in Rochester enjoy insurance premiums that are significantly lower than the national norm. According to recent data:
“Residents in Rochester, New York, pay an average of $1,524 annually for a homeowners insurance policy with $300,000 in dwelling coverage and a $1,000 deductible.”
Compare this to the national average of $2,377 per year, and you can see we’re actually getting a pretty good deal around here.
Of course, your personal rate can vary depending on several factors. The most significant of these include the amount of dwelling coverage you select and your chosen deductible. As coverage amounts increase, your premium naturally goes up. Here’s a quick glance at what you can expect for typical coverage levels in Rochester:
| Dwelling Coverage | Average Annual Premium |
|---|---|
| $200,000 | $1,017 |
| $300,000 | $1,524 |
| $400,000 | $2,032 |
| $500,000 | $2,541 |
Similarly, your deductible—the amount you’ll pay out-of-pocket before insurance kicks in—affects your premium. For example, choosing a lower deductible such as $500 gives you higher premiums (around $1,569 per year), while increasing your deductible to $2,000 could bring your annual premium down to approximately $1,432. It’s all about finding the sweet spot that fits your family’s budget and comfort level.
At Mitchell-Joseph Insurance Agency, we’ve spent years helping Rochester homeowners strike that perfect balance between affordability and excellent coverage. Because we’re an independent, family-owned agency, we can shop around and compare quotes from 24 different insurance companies to find you the best rates and coverage options. We don’t just love saving you money—we live for it.
If you’re curious whether you’re getting the best possible deal on your Home Insurance Rochester, don’t hesitate to reach out. We’re always happy to chat, review your policy, and help you keep more of your hard-earned cash in your pocket.
Factors Affecting Home Insurance Rates in Rochester
If you’re shopping around for Home Insurance Rochester, it’s helpful to understand what impacts your rates. Here in Rochester, we have a unique set of considerations that insurers look at when determining your premiums.
One major factor, of course, is our notorious severe winter weather. With snowfall totals often reaching up to 120 inches annually, Rochester homes face a higher risk of damage from snow and ice. Insurers know homes here need to handle heavy snow loads, ice dams, and freezing pipes—so naturally, these weather-related risks influence your policy costs.
Another factor is the local property crime rate. Rochester averages around 3,605 property crimes per 100,000 residents each year, which is higher than many other areas. Neighborhoods with liftd crime rates typically see higher home insurance premiums, as insurers factor in greater risks of theft and vandalism.
The age and construction of your home also play a big role. Many neighborhoods in Rochester feature beautiful but older homes. Older houses often come with outdated electrical systems, plumbing, or building materials, increasing the risk of fire or water damage. If you own a historic or vintage home, you’ll likely need specialized coverage—and that could bump your premiums up slightly.
Where you’re located in relation to fire protection services matters too. Homes closer to fire stations and hydrants tend to qualify for better rates due to quicker emergency response times. If you live further out from Rochester proper and emergency services take longer to reach you, you might notice slightly higher premiums on your policy.
You might not realize it, but certain features of your home can also help lower your insurance rates. Insurers love homes that have safety measures like security systems, functioning smoke detectors, deadbolt locks, and storm-resistant windows. At Mitchell-Joseph Insurance Agency, we’ve helped clients qualify for discounts simply by making these kinds of home improvements.

Another important consideration in Rochester is your roof’s age and condition. Because of the frequent heavy snowfall, insurers pay close attention to your roof. Homes with newer, stronger roofs often benefit from lower premiums since they’re less likely to suffer costly damage.
Lastly, your personal and neighborhood claims history has a significant impact on your rates. Areas in Rochester prone to frequent claims—such as flooding from snowmelt or storm damage—often experience higher overall premiums. Insurers look at your individual claims record as well, offering the best rates to homeowners with clean claim histories.
That’s why our team at Mitchell-Joseph Insurance Agency works closely with homeowners to understand these factors clearly. By identifying ways to improve home safety and reduce risks, we can often help lower your premiums without sacrificing important coverage.
Common Risks and Perils for Rochester Homeowners
Understanding Rochester’s unique home risks is key to securing a strong Home Insurance Rochester policy. By knowing the most common hazards, you’ll ensure your home is protected from the unexpected.
First off, anyone who’s spent a winter here knows snow and ice damage is a real concern. Heavy snow can put massive pressure on roofs, sometimes causing collapse or structural damage. Ice buildup can lead to damaging ice dams, causing water leaks inside your home. And let’s not forget frozen pipes bursting—that’s an insurance claim waiting to happen!
Just recently in January 2024, Rochester saw significant snowfall followed by a quick warm-up. The result? Widespread snowmelt causing floods in parts of Rochester. Unfortunately, standard homeowners policies don’t cover flood damage, whether from snowmelt or heavy rains. That’s why adding separate flood insurance through the National Flood Insurance Program can be so important for Rochester residents near Lake Ontario, the Genesee River, or other flood-prone neighborhoods.
Property crime is another risk Rochester homeowners should consider. Given our city’s higher-than-average property crime rates, make sure your policy covers you well for theft or vandalism—including your personal belongings inside the home.
Strong wind storms also happen throughout our region, often damaging roofs and siding, or even knocking trees onto homes. Thankfully, standard home insurance usually covers wind-related damage, but it’s always wise to double-check your individual policy limits and deductibles.
Finally, older Rochester homes can face challenges from water damage due to plumbing issues. Sudden pipe bursts or accidental leaks are typically covered by standard insurance policies—but gradual leaks or general neglect usually aren’t. Regular maintenance and prompt repairs can save you headaches later on.
At Mitchell-Joseph Insurance Agency, we’ve seen just how important proper coverage can be. For instance, last winter, one of our clients in Pittsford experienced severe roof damage from heavy snow accumulation. Fortunately, they had comprehensive dwelling coverage, which handled the full replacement cost (even as construction prices soared). They were back under a safe roof quickly—without draining their savings.
Having the right Home Insurance Rochester coverage means you’re prepared for whatever our area throws your way. And trust us—we’ve seen it all.
Ways to Save on Home Insurance Premiums in Rochester
As a homeowner in Rochester, you’re likely familiar with heavy snowfall, icy winters, and other unique local challenges. But did you know you can still enjoy substantial savings on your Home Insurance Rochester premiums without sacrificing coverage? At Mitchell-Joseph Insurance Agency, we’ve spent years helping Rochester residents find smart ways to cut insurance costs while keeping their homes fully protected.
One of the best ways to lower your premiums is to bundle your policies. By combining your home insurance with auto or umbrella coverage through the same insurer, you can access impressive discounts—often up to 25%. New York Central Mutual Insurance even offers bundling discounts of up to 35% when you add umbrella insurance. That’s a big win for your wallet.
Another simple strategy is to increase your deductible. Choosing a higher deductible—for example, increasing from $500 to $2,000—could cut around 9% off your annual premium. Just make sure you’re comfortable paying that deductible amount out of pocket if you ever need to file a claim.
Investing in safety measures is another smart move. Installing safety and security features like smoke detectors, carbon monoxide alarms, burglar alarms, deadbolt locks, and sprinkler systems can net you savings of anywhere from 5% to 20%. Not only will you save money, but you’ll also gain valuable peace of mind.
Did you know your credit score can influence your insurance premiums? Many insurers look at credit-based insurance scores when calculating your rates. Maintaining a good credit standing could open the door to lower premiums.
Insurance companies love loyalty, too. Staying with the same insurer for multiple years often earns you loyalty discounts—typically around 5% after three years and up to 10% after five years. Building a long-term relationship with your insurer quite literally pays off.
Don’t forget the importance of home maintenance. Making strategic home improvements like updating your electrical, plumbing, or HVAC systems can reduce your home’s risk profile, leading to lower premiums. Considering Rochester’s extreme winters, choosing weather-resistant upgrades such as impact-resistant roofing can also help you qualify for special discounts.
It never hurts to ask your agent about additional savings. Insurance companies often provide special discounts for retirees, members of certain professional groups, or employees at specific companies. At Mitchell-Joseph Insurance Agency, because we partner with 24 different insurance carriers, we’re always able to hunt down every available discount on your behalf.
Lastly, regularly reviewing your policy is important. Review and update your policy regularly to make sure you’re getting coverage that matches your current needs. You may find opportunities to trim unnecessary coverage or take advantage of new discounts.
Specific Discounts Available for Rochester Homeowners
Living in Rochester means dealing with tough winters, and insurers recognize this. As a homeowner, you may qualify for several special discounts focused specifically on managing regional risks.
Many insurers offer winter weather preparation discounts for homes equipped with insulation upgrades, heat tape on pipes, or water leak detection systems. These upgrades help reduce the likelihood of winter-related home damage—good news for both you and your insurer.
Given the heavy snowfall Rochester sees each year, installing a new roof can pay off significantly. Many insurance providers offer new roof discounts of 5% to 10% for roofs less than 10 years old—which can really add up in long-term savings.
If you’ve been diligent about property maintenance, insurers reward you. Maintaining a claims-free status for 3 to 5 years can qualify you for discounts of up to 20%. It’s like getting a pat on the back for taking great care of your home.
And let’s not forget smart technology. Smart home technology discounts reward homeowners who install modern sensors and monitoring devices to detect water leaks, monitor temperature to prevent frozen pipes, or alert you about potential intrusions.
If you’re retired, you might qualify for a retired homeowner discount of around 5% to 10%. Since retirees tend to spend more time at home, insurers view them as lower risk: a benefit you definitely deserve after years of hard work.
First-time homeowners aren’t overlooked either—insurers frequently offer special first-time homebuyer discounts to attract new residents into Rochester’s vibrant community.
At Mitchell-Joseph Insurance Agency, we’ve helped countless families in Rochester and surrounding communities like Honeoye Falls, Pittsford, and Canandaigua find these hidden savings. Recently, one Rochester family we serve saved over $400 annually by bundling their home and auto policies, installing smart water leak detectors, and qualifying for a claims-free discount. With the extra savings, they were able to comfortably increase their coverage limits, providing even better protection for their home, without stretching their budget.
Finding affordable, comprehensive Home Insurance Rochester doesn’t have to be complicated or stressful. Let Mitchell-Joseph Insurance Agency show you how easy it can be.
Essential Coverage Options for Rochester Homeowners
Living in Rochester comes with many perks: beautiful seasons, charming historic neighborhoods, and plenty of community spirit. But as any seasoned Rochester homeowner knows, it also means dealing with some unique challenges—like heavy snowfall, ice dams, flooding concerns, and aging infrastructure. At Mitchell-Joseph Insurance Agency, we make sure your Home Insurance Rochester policy covers those local risks, giving you peace of mind no matter what Mother Nature (or old pipes!) throws your way.
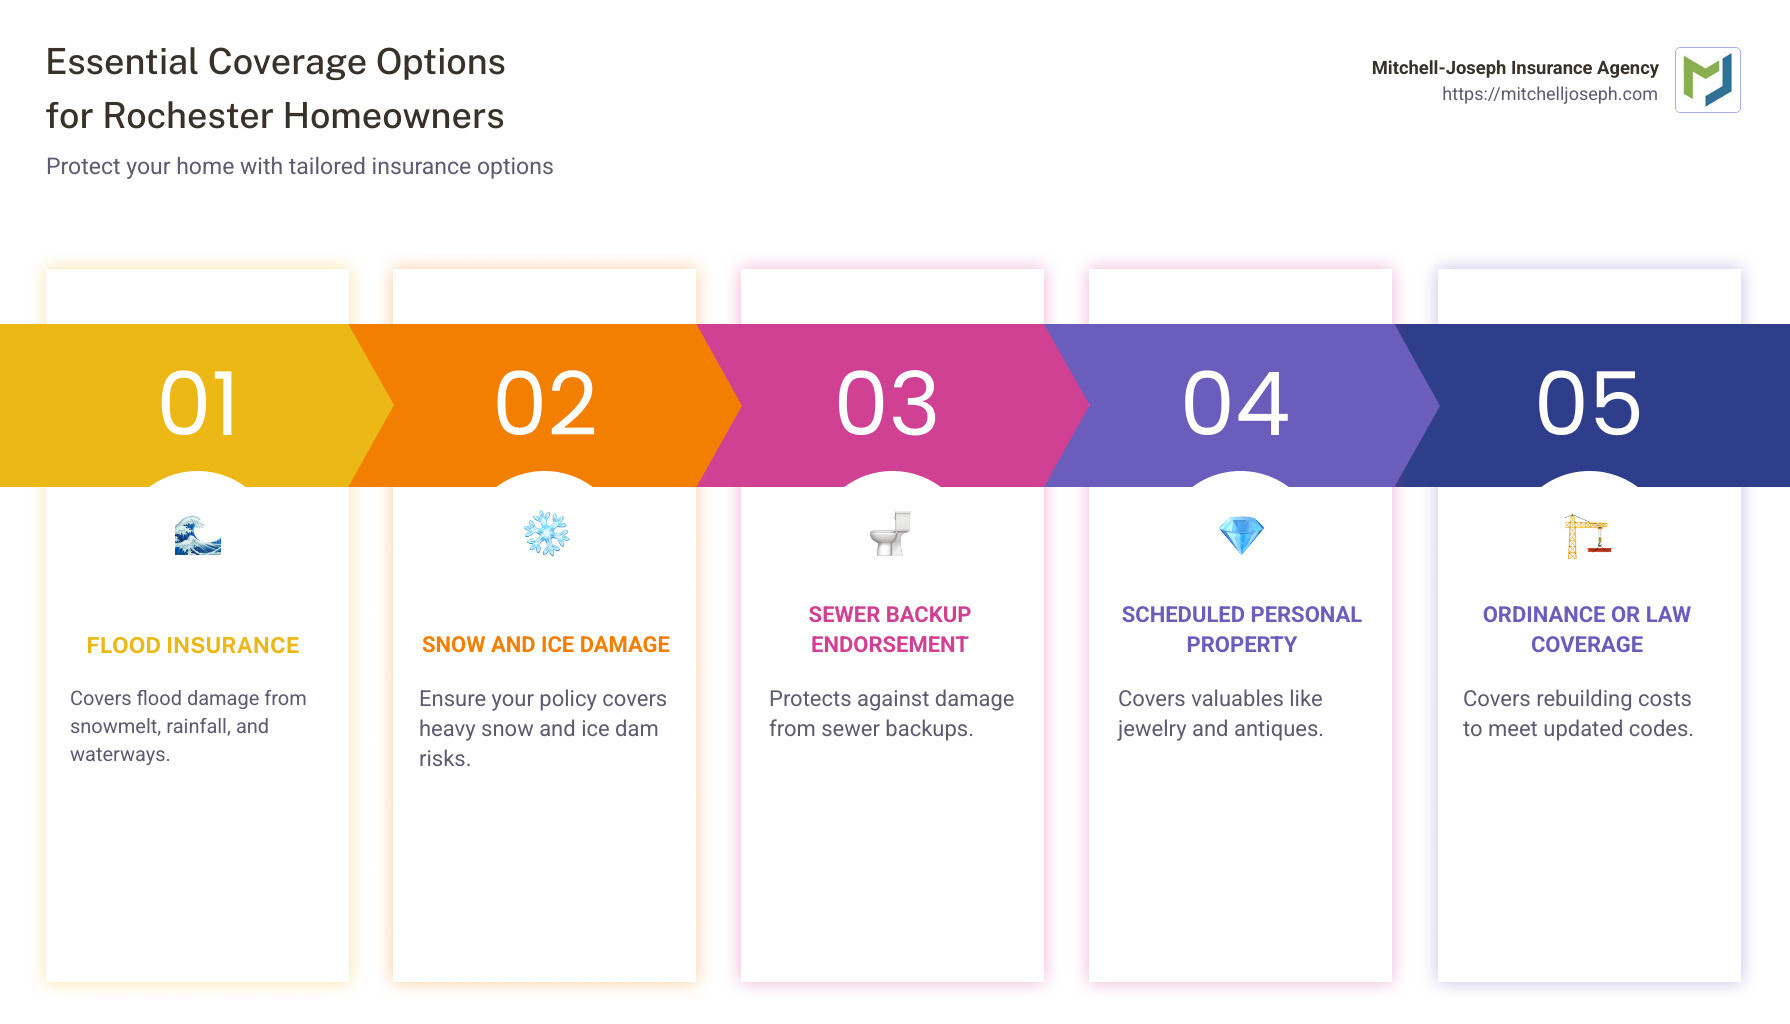
One critical piece of protection we always talk about is flood insurance. Many homeowners are surprised to learn standard homeowners policies don’t cover flooding—even though Rochester sees its fair share from snowmelt, spring rains, and proximity to Lake Ontario, Irondequoit Bay, and the Genesee River. A separate flood policy through the National Flood Insurance Program (NFIP) or a private insurer can save you from having to pay potentially tens of thousands of dollars out-of-pocket. Trust us—when your basement feels more like a wading pool, you’ll thank yourself for having flood insurance.
Another essential consideration is snow and ice damage coverage. Most standard policies do typically cover roof collapses and damage caused by heavy snow. But Rochester homeowners need to double-check their specific coverage limits, especially regarding ice dams. Ice dams form when snow melts, then refreezes at the edge of your roof, potentially causing leaks and extensive water damage. Ensuring your policy specifically addresses these risks is a smart move—after all, dealing with ice dams is enough of a headache without finding out you’re on the hook for expensive repairs.
Then there’s the dreaded sewer backup—not anyone’s favorite topic, but a reality in some Rochester neighborhoods with aging sewer systems. Unfortunately, a standard homeowners policy won’t cover damage from backed-up sewers or drains. Adding on a sewer backup endorsement will save you from a messy (and costly) nightmare if your drain ever decides to revolt during heavy rains or storm events.
Rochester is proud of its historic homes, many packed with antiques, artwork, or collectibles. Standard home policies have limited coverage for valuable items. That’s why we often recommend scheduled personal property coverage, which provides higher limits specifically custom for your valuables. This endorsement can be a lifesaver—especially if you’ve collected precious heirlooms or one-of-a-kind art pieces over the years.
Another often-overlooked option is service line coverage. Rochester’s dramatic freeze-thaw cycles can wreak havoc on underground utility lines coming into your property. This affordable endorsement covers the repair or replacement of utility lines, helping you avoid an unexpected and hefty bill.
If you run a business out of your home, your standard homeowners policy probably won’t protect your business equipment or offer any liability protection for business activities. Adding home business coverage ensures you’re properly covered—whether it’s for a daycare, consulting, or an Etsy shop selling hand-knit winter scarves.
And speaking of aging homes—building codes in Rochester have changed dramatically over the years. Rebuilding after a covered disaster could come with significant additional costs just to meet today’s strict codes. Ordinance or law coverage fills the gap, covering the extra expenses required to rebuild your home to current standards.
Lastly, with identity theft and cyber risks continuing to rise, adding identity theft coverage to your homeowners policy helps you handle the often overwhelming costs involved in restoring your identity and credit after an incident.
At Mitchell-Joseph Insurance Agency, our goal isn’t to sell you every available option—it’s to recommend the coverages that truly make sense for you, your home, and your budget. We’ve been helping Rochester-area homeowners steer these questions for over 20 years, and we’re here to make sure you’re protected from whatever Rochester living brings your way.
Understanding Flood Insurance in Rochester
You might not picture Rochester as a hotspot for flooding—but the truth is, our city sees more than its fair share of potential flood risks. Between Lake Ontario, the Genesee River, Irondequoit Bay, and countless smaller creeks and streams, heavy rains and rapid snowmelt can quickly trigger flooding. Unfortunately, standard home insurance policies don’t cover flood damage at all, leaving homeowners potentially exposed to huge costs.
Flood insurance policies through the National Flood Insurance Program (NFIP) generally provide up to $250,000 in coverage for your home’s structure, and up to $100,000 for your personal belongings. Just keep in mind, flood insurance policies typically have a 30-day waiting period before coverage starts, so it pays to plan ahead.
Private flood insurance is another good option, sometimes offering higher coverage limits, shorter waiting periods, and competitive premiums custom specifically to your home’s flood risk.
Here’s the thing—even if your home isn’t located in a designated high-risk flood area, flooding can still happen. In fact, over 20% of NFIP flood claims come from homes outside official “flood zones.” We’ve helped Rochester clients steer floods they never expected—like the family whose basement flooded after intense spring rains combined with rapid snowmelt. Luckily, they took our advice and had flood insurance, saving them more than $30,000 in out-of-pocket expenses.
The bottom line? Flood insurance isn’t just for waterfront homes. At Mitchell-Joseph Insurance Agency, we look closely at flood maps and local flood history, helping you decide whether this coverage makes sense for your home.
When it comes to Home Insurance Rochester, we believe being prepared makes all the difference. Whether it’s flooding, snowstorms, or anything else Rochester dish out, we’ve got your back.
Benefits of Bundling Home Insurance with Other Policies
If you’re a homeowner in Rochester, you’re probably always looking for ways to simplify your life and save a few dollars. One of the best-kept secrets to achieving both goals is bundling your Home Insurance Rochester policy with your other insurance coverage, such as auto or umbrella policies. Here at Mitchell-Joseph Insurance Agency, we always advise our clients in Rochester and surrounding areas like Pittsford, Honeoye Falls, and Canandaigua to explore the possibility of bundling—because the benefits truly speak for themselves.
First and foremost, bundling your insurance can lead to significant cost savings. By combining your home and auto policies with the same insurance provider, you can usually enjoy discounts of around 10% to 25%. In fact, some providers, like New York Central Mutual Insurance, offer bundling discounts of up to 25% when you combine auto and home insurance—and even up to 35% savings if you add umbrella insurance. These discounts can add up to hundreds of dollars each year, giving you extra money to spend on things you actually enjoy (like finally replacing your snowblower before next winter!).
Another great benefit is simplified policy management. Let’s face it—trying to keep track of multiple insurance policies with different companies, renewal dates, and billing cycles can be a headache. Bundling helps you streamline everything into one easy-to-manage package. You’ll have just one renewal date, one company to deal with, and a single point of contact for all your questions and claims. Trust me: during an emergency, the last thing you want to do is go through a stack of papers to remember which company covers what!
When your policies are bundled, it’s also easier to avoid dangerous coverage gaps. Your insurance agent will have a clear, comprehensive overview of all your policies and can quickly identify any weak spots or overlaps. This ensures you have just the right amount of protection—nothing missing, nothing unnecessary.
Another lesser-known perk offered by some insurers is a single deductible benefit. Imagine this: a fierce Rochester winter storm damages both your home and your car. Without bundled coverage, you might have to pay two separate deductibles. But if your policies are bundled, some insurers will require just one deductible for the entire event. That can be a huge relief when you’re already dealing with unexpected expenses.
Insurance companies also tend to reward loyalty. By bundling your coverage, you become a long-term, valued customer, which often translates into better loyalty benefits. These might include extra discounts, flexible payment options, or faster claims processing.
Finally, bundling allows you to add layers of coverage more easily, such as umbrella insurance. An umbrella policy kicks in when you’ve exhausted the liability limits on your home or auto insurance, providing an extra safety net for your financial security. This can be especially valuable if you have significant assets to protect or simply want extra peace of mind.
We recently helped a family from Pittsford who were paying over $3,200 annually for separate home and auto policies with different insurance providers. After reviewing their options, we bundled their policies through Mitchell-Joseph Insurance Agency and reduced their combined premium to just $2,600 a year—that’s a savings of $600! Even better, we managed to increase their total coverage limits, leaving them better protected than ever.
At Mitchell-Joseph Insurance Agency, we have access to competitive quotes from 24 different insurance companies. That means we can shop around on your behalf to find the best bundling options available, ensuring you get the perfect balance of coverage, convenience, and cost savings.
Ready to see how much you could save by bundling your policies? Visit our Homeowners Insurance in Rochester NY page to explore your options or talk to one of our friendly local agents today.
Frequently Asked Questions about Home Insurance in Rochester
How does the cost of homeowners insurance in Rochester compare to the national average?
Good news for Rochester homeowners: Home Insurance Rochester policies are generally more affordable compared to the national average. On average, Rochester residents pay around $1,524 per year for a standard policy that includes $300,000 in dwelling coverage and a $1,000 deductible. This is significantly lower than the nationwide average of about $2,377 for similar coverage.
Several reasons help keep Rochester’s home insurance rates relatively affordable. For one, the city has lower median home values—around $159,900 compared to higher national averages—which reduces replacement costs for insurers. Additionally, Rochester has strong local building codes designed to handle severe winter weather, which reduces the risk of extensive damage and helps keep costs down. Plus, Rochester benefits from a healthy competitive insurance market, giving homeowners plenty of options and competitive pricing.
That said, remember your personal premiums can still vary widely depending on the specifics of your house, its location, your insurance history, and the exact coverage you choose. At Mitchell-Joseph Insurance Agency, we always take the time to review your situation closely, ensuring you get coverage that’s just right for you—at a price that won’t break the bank.
What factors affect the cost of homeowners insurance in Rochester?
Many different factors can impact the price you pay for Home Insurance Rochester, and some are unique to our area. Rochester’s winter weather, for example, is a big factor. With annual snowfall reaching up to 120 inches, insurers consider your home’s ability to withstand heavy snow loads, ice damming, and potential flooding from snowmelt. Homes with newer roofs, reinforced structures, or winter-weather preparedness features often earn lower premiums.
The characteristics of your home itself matter, too. Older properties—common in Rochester’s historic neighborhoods—can cost more to insure, as insurers factor in the higher costs of repairing outdated electrical or plumbing systems. Similarly, larger homes or those built using more expensive construction materials typically require higher premiums since they’re more costly to repair or rebuild.
Where your home is located within Rochester can also affect your rates significantly. Neighborhoods closer to fire stations with good emergency response times often have lower premiums than more rural areas. Areas with higher crime rates or proximity to flood-prone locations like the Genesee River or Irondequoit Bay may see higher insurance costs or need to add flood insurance coverage separately.
Personal factors play a role as well—your claims history, credit rating, and the length of time you’ve been insured can all influence your premiums. Finally, the coverage options you select will directly impact your cost. Higher liability limits, a lower deductible, or adding endorsements for valuables or special perils generally translate to higher premiums, while choosing a higher deductible can lower your payment.
At Mitchell-Joseph Insurance Agency, we carefully evaluate all these factors to find you the best coverage at the best rate. Our local expertise ensures we pinpoint exactly what influences your home insurance costs, saving you money while keeping you well-protected.
Are there specific discounts available for Rochester homeowners?
Absolutely! Rochester homeowners have access to several discounts specifically custom to encourage preparedness, reward loyalty, and help reduce the costs associated with our challenging local climate.
Because winter weather is a major factor here, insurers offer Winter Weather Preparation Discounts for homeowners who invest in protective features. Proper insulation, heat tape installed on pipes, and water leak detection systems all contribute to safer homes—and lower premiums.
Another great way to save is by bundling your insurance policies. Combining your home and auto policies, for instance, can provide savings of up to 25% with many insurers. Some companies, like New York Central Mutual Insurance, even offer discounts of up to 35% when you add umbrella coverage into the mix.
If you’ve been careful and haven’t filed any claims in recent years, you can qualify for Claims-Free Discounts, typically saving up to 20% annually. Additionally, insurers reward homeowners who update their roofs with newer, more durable materials; these New Roof Discounts are especially valuable given Rochester’s heavy snowfall.
Smart technology can help protect your home and lower your bill, too. Devices like water leak sensors, temperature monitoring systems (to prevent frozen pipes), and home security alarms can qualify you for Smart Home Technology Discounts.
Other ways to save include discounts for homeowners belonging to specific professional associations or employer groups (Professional Association Discounts), loyalty benefits for long-term customers (Loyalty Discounts), and special savings for senior citizens or retirees who are often home more frequently (Senior or Retiree Discounts).
At Mitchell-Joseph Insurance Agency, we know every discount matters. We thoroughly review your unique situation and ensure you’re not missing out on any savings opportunities. Our relationships with 24 different insurance providers allow us to match you with the perfect coverage at the lowest possible price—keeping your home protected and your wallet happy.
Conclusion
Protecting your home with comprehensive Home Insurance Rochester coverage isn’t just smart financial planning—it’s about giving yourself and your loved ones peace of mind. As homeowners in Rochester, we face unique challenges: the famously heavy snowfall, flooding risks from snowmelt, and property crime rates that remind us that we don’t exactly live in Mayberry. Having the right insurance makes all the difference.
Throughout this guide, we’ve covered the essentials of home insurance in Rochester, including understanding the average costs (remember, our local average is around $1,524 annually—much easier on the wallet compared to the national average of $2,377!). We’ve also dived into key coverage types you should consider and broken down the specific factors that influence your premiums.
If you take away anything from this guide, let it be the importance of customizing your coverage to fit Rochester’s unique risks. Heavy snow and ice can damage roofs and lead to flooding when it melts. Crime rates require thoughtful coverage for theft and vandalism. Older homes, common throughout our city, often need specialized policies. Tailoring your policy to include coverages like flood insurance, sewer backup protection, and adequate snow and ice damage coverage can save you from nasty surprises later on.
And don’t forget about the many savings opportunities specific to our area. You can save significantly by bundling your home and auto insurance—up to 35% with insurers like New York Central Mutual Insurance. Installing safety features such as security alarms, water leak detectors, and upgrading your roof can earn you discounts. By regularly reviewing your insurance policy, you make sure your coverage stays current and cost-effective.
At Mitchell-Joseph Insurance Agency, we’ve been proudly serving Rochester and surrounding communities like Honeoye Falls, Pittsford, and Canandaigua for decades. As a family-owned business, we’re more than just a voice on the phone—we’re your neighbors. With over 200 years of combined experience, our team knows what it takes to keep Rochester homeowners well-protected.
We partner with 24 top-rated insurance companies, which means we can find the ideal blend of coverage and affordability custom specifically to you. Our local expertise ensures you won’t miss important coverages unique to our region.
Ready to make sure your Rochester home is truly protected? We warmly invite you to reach out to us at Mitchell-Joseph Insurance Agency for a personalized review of your current home insurance or to explore new coverage options. We promise no complicated jargon, just straightforward advice—and maybe even a joke or two to keep things interesting.
Don’t wait until a storm hits or an unexpected event leaves you scrambling. Get prepared today, so you can relax tomorrow.