

How does rental reimbursement work for car insurance? It’s a straightforward yet significant part of your auto insurance puzzle. To give you a quick picture:
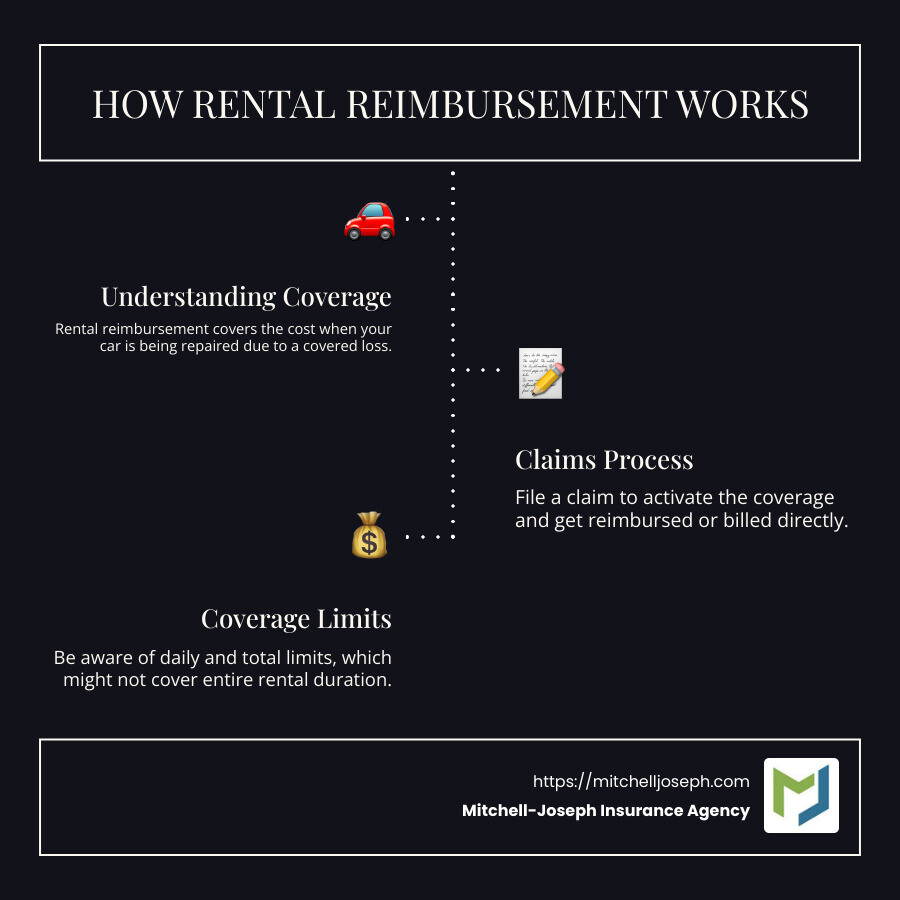
- Rental reimbursement helps cover the cost of a rental car while your vehicle is out for repairs due to a covered loss.
- It kicks in when the repair is due to an accident, and you’re not at fault, or you’ve got comprehensive or collision coverage on your policy.
- It’s optional coverage. You won’t get it unless you add it to your policy.
Navigating rental reimbursement in car insurance can save you from unexpected expenses when your vehicle is out of commission. It ensures you’re not stranded without transportation during repairs after a covered incident. At Mitchell-Joseph Insurance, we understand the critical role this coverage plays in your day-to-day life.
As Jeffrey Joseph, at Mitchell-Joseph Insurance, I have over two decades of experience helping clients understand how does rental reimbursement work for car insurance. I’m dedicated to simplifying insurance matters for homeowners and business owners alike in upstate New York. With this guide, we’ll help you explore the details of this important coverage option.
What is Rental Reimbursement Coverage?
Rental reimbursement coverage is an optional add-on to your auto insurance policy. It covers the cost of renting a car while your own vehicle is being repaired due to a covered accident.
Why Consider Rental Reimbursement?
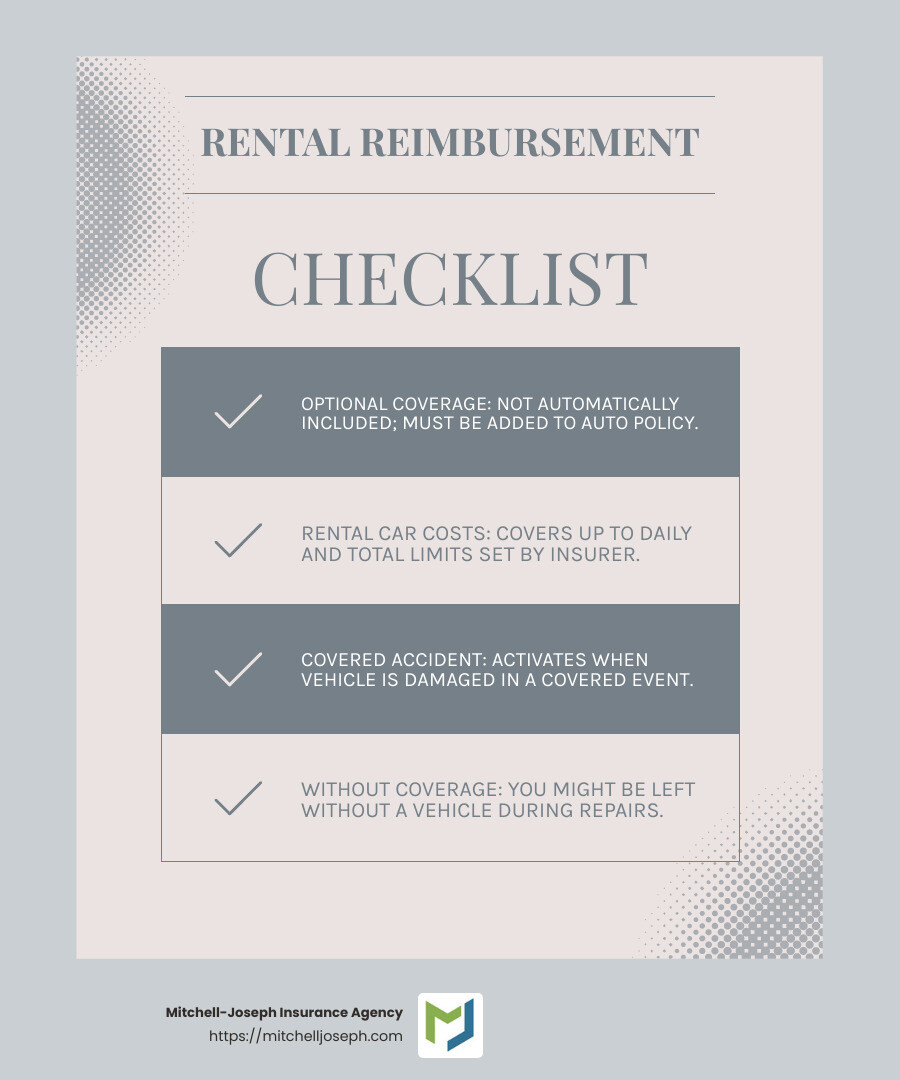
Imagine getting into an accident and your car needs repairs. Without rental reimbursement, you might be left without a vehicle. This coverage steps in to pay for a rental car, ensuring you can continue your daily activities without interruption.
Key Features of Rental Reimbursement Coverage
-
Optional Coverage: Unlike liability or collision insurance, rental reimbursement isn’t automatically included in most auto policies. You have to choose to add it.
-
Rental Car Costs: This coverage helps pay for your rental car expenses. However, there are limits. Usually, insurance companies set a daily limit (often around $30-$50 per day) and a total claim limit.
-
Covered Accident: Rental reimbursement kicks in when your vehicle is out of action due to a covered accident. This could be an accident where you’re not at fault, or incidents covered under your comprehensive or collision insurance.
Important Considerations
-
Check Your Limits: With rental cars becoming more expensive, it’s crucial to know your policy’s limits. If your coverage is capped at $30/day but rentals cost more, you’ll pay the difference out of pocket.
-
Plan Ahead: If having a car is vital for your daily routine, consider adding rental reimbursement to your policy. It’s a small monthly cost that can save you a lot of hassle and money in the long run.
At Mitchell-Joseph Insurance, we make it easy to understand and choose the right coverage for your needs. Whether you’re commuting to work or running errands, rental reimbursement can be a lifesaver when your car is in the shop.
How Does Rental Reimbursement Work for Car Insurance?
When it comes to how rental reimbursement works for car insurance, understanding the claim process and reimbursement limits is key. Rental reimbursement coverage is designed to help you stay on the road while your car is being repaired after a covered event.
When Can You Use Rental Reimbursement?
Rental reimbursement can be used when your car is in the shop due to a covered accident. These events typically include accidents where you have collision or comprehensive coverage. For instance, if your car is damaged in a storm or an accident, you can rely on this coverage to pay for a rental car.
-
Repair Duration: You can use the rental until your car is fixed or until you hit the reimbursement limits. These limits might be a daily amount (like $30 to $50) or a total amount per claim.
-
Total Loss: If your car is declared a total loss, the rental coverage period might be shorter. You’ll need to start looking for a replacement vehicle quickly.
Is There a Deductible for Rental Reimbursement?
Good news! There is no deductible for rental reimbursement. This means you won’t have to pay anything out of pocket to start using a rental car.
- Comprehensive and Collision Coverage: Rental reimbursement usually works alongside these types of coverage. If your car is damaged in a way that’s covered by your comprehensive or collision insurance, your rental costs can be covered too.
Claim Process and Direct Billing
The claim process for rental reimbursement is straightforward. If your car is in the shop due to a covered event, you can set up a rental through your insurance company. Some insurers offer direct billing with certain rental companies, like Enterprise Rent-A-Car. This means the rental company bills your insurer directly, saving you from paying upfront and waiting for reimbursement.
- Reimbursement Limits: Be aware of your policy’s limits. If your rental costs exceed these limits, you’ll need to cover the extra costs yourself.
Knowing these details can help you make the most of your rental reimbursement coverage. It’s all about ensuring you’re not left stranded without a vehicle when you need one the most.
How Long Will Insurance Pay for a Rental Car?
When you have rental reimbursement coverage, it’s important to know how long your insurance will pay for a rental car. This is determined by two main factors: the daily limit and the total limit of your policy.
Daily Limit
The daily limit is the maximum amount your insurance will cover per day for a rental car. This is often between $30 to $50 per day. However, as rental car prices have increased, this amount might not cover the full cost of a rental, especially in areas where rental cars are more expensive. Make sure you know your policy’s daily limit so you can plan accordingly.
Total Limit
The total limit is the maximum amount your insurance will cover for a rental car per claim. This can be a set dollar amount or a time limit, such as 30 days. For example, if your policy covers up to $900 total for a rental, and your daily rental cost is $40, you could rent a car for up to 22 days before reaching your limit.
Coverage Duration
The duration of your rental car coverage depends on how long it takes to repair your car or until you reach your policy’s limits. If repairs take longer than expected, or if your car is deemed a total loss, you might need to explore other transportation options once your coverage runs out.
Understanding these limits helps you avoid unexpected expenses and ensures you’re not left without transportation while your car is being repaired. Always check your policy details and speak with your insurance agent to confirm your coverage specifics.
What is Not Covered by Rental Reimbursement?
While rental reimbursement is a helpful feature, it’s crucial to know what isn’t covered to avoid surprises. Here are some key exclusions you should be aware of:
Gas Costs and Mileage
Rental reimbursement coverage typically doesn’t include the cost of gas. You’ll need to fill up the tank yourself, just like with your own car. Additionally, any mileage fees imposed by the rental company are not covered. Keep an eye on the rental’s mileage policy to avoid extra charges.
Additional Insurance
When you rent a car, the rental company might offer you additional insurance options. These can include collision damage waivers or liability insurance. However, rental reimbursement won’t cover these extra insurance costs. If you have comprehensive and collision coverage on your personal auto policy, it often extends to the rental car. But, it’s wise to verify this with your insurance agent before declining rental insurance.
Security Deposits and Other Fees
Rental companies often require a security deposit, usually held on your credit card. This deposit is not covered by rental reimbursement. Also, any administrative fees or charges for extra services, like GPS or car seats, are your responsibility.
Understanding these exclusions helps you plan better and manage your expenses when using rental reimbursement. Always check your policy details and consult with your insurance agent for personalized advice.
Frequently Asked Questions about Rental Reimbursement
How Does Car Insurance Reimbursement Work?
Rental reimbursement coverage is an optional part of your personal auto insurance policy. It helps cover the cost of a rental car when your vehicle is being repaired after a covered accident. But how exactly does it work?
When you file an insurance claim for a covered loss, rental reimbursement kicks in to help you stay on the road. Your insurance company will either pay the rental car company directly or reimburse you for the rental costs. That coverage limits apply, so you should know the daily and total limits of your policy. Anything beyond these limits will come out of your pocket.
Who Pays for a Rental Car After an Accident?
After an accident, determining who pays for the rental car depends on who is at fault. If the other driver is at fault, their insurance should cover the cost of your rental car while your vehicle is being repaired. However, if you are the at-fault driver, you will need rental reimbursement coverage to avoid paying out of pocket for the rental.
If the fault is contested, having rental reimbursement can be a lifesaver. You can get a rental car while the insurance companies sort out who is responsible. If the other driver is eventually deemed at fault, your insurer can seek reimbursement from their insurance company.
Can I Add Rental Reimbursement Coverage After an Accident?
Unfortunately, you cannot add rental reimbursement coverage to your policy after an accident to cover that specific incident. Insurance policies only cover future losses, not past events. Therefore, it’s crucial to have rental reimbursement in place before an accident occurs.
You can, however, make policy changes at any time to protect yourself in the future. Adding rental reimbursement coverage now will ensure you’re prepared for any unforeseen events down the road.
Understanding these key aspects of rental reimbursement can help you make informed decisions about your coverage. If you have questions or need to adjust your policy, don’t hesitate to contact your insurance agent for guidance.
Conclusion
At Mitchell-Joseph Insurance Agency, we pride ourselves on offering personalized service and custom coverage options to meet your unique needs. With over 200 years of combined experience, our team is dedicated to helping you steer the complexities of insurance, including rental reimbursement coverage.
Why Choose Us?
We’re not just about providing insurance; we’re about providing peace of mind. As an independent, family-owned business, we have the flexibility to offer competitive quotes from 24 different insurance companies. This means we can tailor your coverage to fit your specific requirements, ensuring you get the best possible protection at the right price.
Our Commitment to You
Whether you’re in Honeoye Falls, Pittsford, or any of our other locations in New York, our goal is to deliver exceptional service and support. We understand that dealing with car repairs and insurance claims can be stressful. That’s why we’re here to guide you through every step, making sure you have the coverage you need when you need it.
Ready to learn more about how we can help with your auto insurance needs, including rental reimbursement? Visit our Auto Insurance page to explore your options and get in touch with our team today.
With Mitchell-Joseph Insurance Agency, you’re not just a policy number—you’re part of our family. Let us help you find the coverage that’s right for you.

