

Why Home Insurance Victor NY Matters for Your Property and Peace of Mind
Home Insurance Victor NY is essential protection for homeowners in this thriving Ontario County community. Understanding your options helps you protect your investment and find the right coverage at a competitive price.
For homeowners in Victor, NY, here’s a quick overview:
- Average Cost: New York homeowners pay around $1,200 per year, but local factors can cause this to vary.
- Required Coverage: Most mortgage lenders require homeowners insurance.
- Key Policy Type: An HO-3 (Special Form) policy is most common, covering your dwelling, personal property, and liability.
- Important Rule: Insure your home for at least 80% of its replacement cost to avoid penalties on claims.
- Local Considerations: Victor’s weather patterns may require extra coverage for water backup or windstorm damage. Flood insurance is a separate, vital policy to consider.
- Available Discounts: Bundling home and auto, installing security systems, and using loss-prevention devices can significantly reduce premiums.
As Jeffrey Joseph, owner of Mitchell-Joseph Insurance Agency, I have over 25 years of experience serving the Finger Lakes Region, including Victor. Our team helps homeowners find Home Insurance Victor NY coverage that balances comprehensive protection with competitive pricing. With multiple locations, we provide personalized service and compare quotes from numerous insurers to ensure you get the best value.
Your Guide to Navigating Home Insurance Victor NY
Finding the right home insurance doesn’t have to be overwhelming. For Victor, NY homeowners, understanding your options is the first step toward protecting what matters most. These resources will help you steer Home Insurance Victor NY with confidence.
Resource 1: Understanding New York Home Insurance Basics
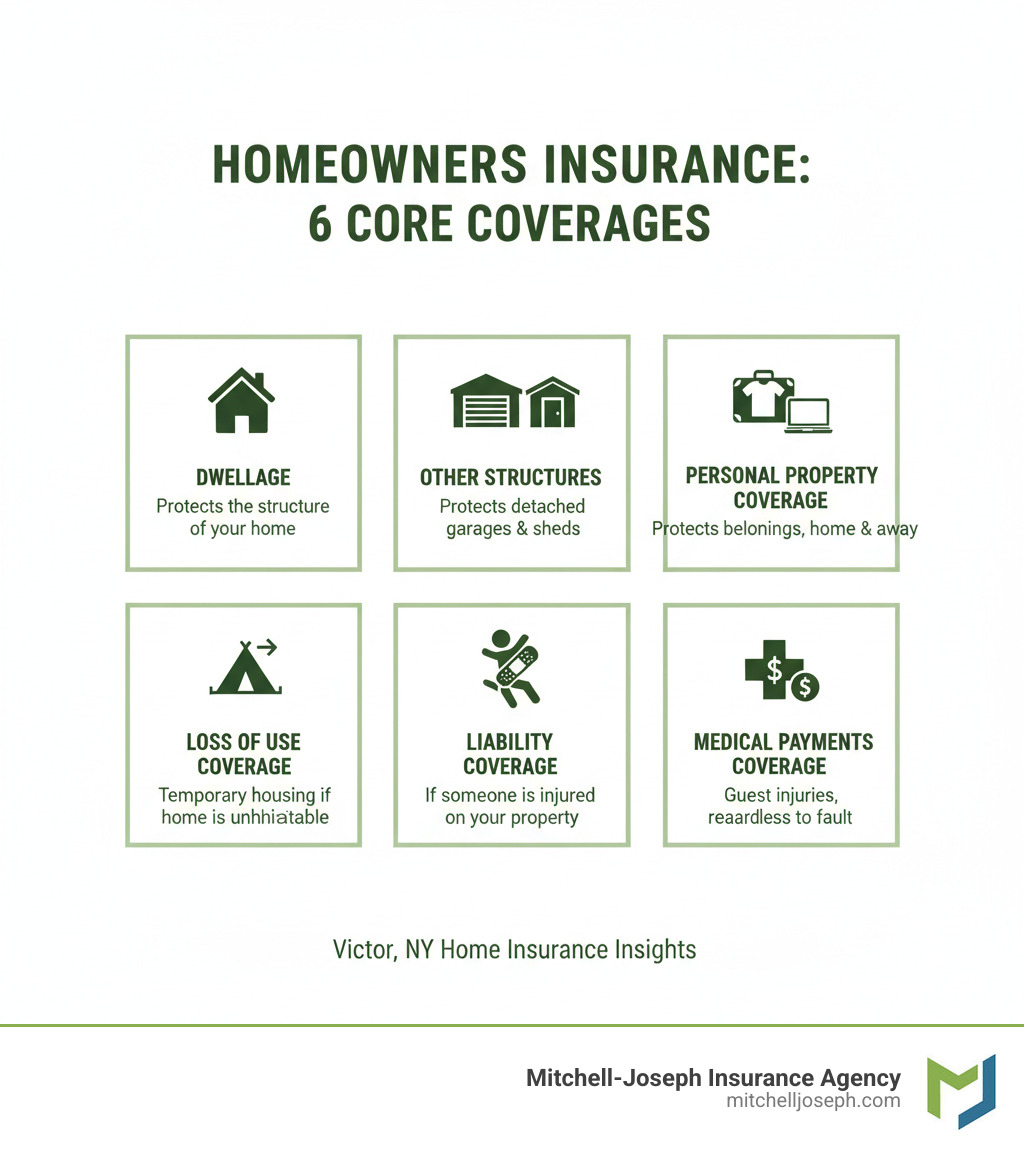
When shopping for Home Insurance Victor NY, you’ll encounter several policy types. Most homeowners choose an HO-3 (Special Form) policy, which protects your home’s structure against all risks unless specifically excluded, while covering your personal belongings for a list of named perils. For broader protection, an HO-5 (Comprehensive Form) covers both your home and belongings against all non-excluded risks. Condo owners need an HO-6 policy for their unit’s interior and belongings, while renters use an HO-4 policy. For a deeper dive, see our Home Insurance Coverage Types page.
Several factors determine your premium. Your home’s location, age, construction materials, and proximity to a fire station all play a role. Your chosen coverage limits and deductible amount directly impact the cost, as does your personal claims history. The good news is that discounts are widely available for safety features like smoke detectors and security systems, bundling policies, and having a newer roof. For more on how costs are calculated, visit our page on New York Home Insurance Rates.
It’s critical to insure your home for its replacement cost—the cost to rebuild it from scratch—not its market value. The New York State Department of Financial Services (DFS) advises insuring for at least 80% of this value to avoid a co-insurance penalty, which can reduce your payout on a claim. For personal property, create a detailed home inventory by listing your belongings and their value. This is invaluable during a claim.
A standard policy covers many perils, including fire, windstorms, hail, theft, and vandalism. However, it’s just as important to know the exclusions. Flood damage and earthquakes are almost always excluded and require separate policies. Damage from wear and tear or lack of maintenance is not covered. A common surprise for homeowners is that sewer backup and sump pump overflow are also typically excluded unless you add a specific endorsement. Given our local weather, this is a crucial add-on to consider. You can also check your property’s flood risk using FEMA’s Flood Map Service Center. Learn more at our Water Sewer Backup Coverage Homeowners page.
Resource 2: The Value of a Local Insurance Expert for Home Insurance Victor NY

In an age of online quotes, a local agent provides personalized service and expertise. For Home Insurance Victor NY, an agent is your guide, advocate, and advisor. We translate complex insurance terms, assess your unique risks (like a home business or swimming pool), and help you find the right amount of coverage. Most importantly, we’re your advocate during a claim, leveraging our local knowledge to smooth the process.
The key difference is between independent and captive agents. A captive agent works for one company and can only offer their products. An independent agent, like Mitchell-Joseph Insurance Agency, works with multiple carriers. We partner with 24 different insurance companies, allowing us to shop the market on your behalf. This gives you more choices and ensures you find the best combination of coverage and price. We do the comparison shopping for you, saving you time and providing unbiased advice custom to your needs. Learn more about finding the right partner on our Home Insurance Agent page or our page on Independent Auto and Home Insurance Agents Victor NY.
Resource 3: Mastering Your Policy and Claims
Understanding your policy’s fine print is crucial. A key term is the difference between Actual Cash Value (ACV) and Replacement Cost (RC). ACV pays for a damaged item’s value minus depreciation, leaving you to cover the difference for a new one. RC pays the full cost to replace the item with a new one of similar quality. For both your home and belongings, RC coverage provides far greater financial protection.
Standard policies can be improved with endorsements for specific risks in Victor. We highly recommend water backup and sump pump overflow coverage. A separate flood insurance policy is also vital, as standard policies do not cover flood damage. You can learn more on our Homeowners Insurance and Flood Insurance page. If you own high-value items like jewelry or art, a personal articles floater provides better protection. A personal umbrella policy offers extra liability coverage above your standard limits.
If you need to file a claim, first ensure everyone’s safety and take steps to prevent further damage. Document everything with photos and videos before cleaning up, and contact your agent promptly. We will guide you through the process and work with the insurance adjuster.
Finally, bundling your home and auto insurance with the same provider is one of the simplest ways to save, often reducing your total premium by 15-20%. It also simplifies your life with one point of contact for your major policies. For a complete overview, check out our Homeowners Insurance Guide NY.
Secure Your Victor, NY Home with Confidence
Your Victor, NY home is your largest financial investment and the center of your family’s life. Ensuring it’s properly protected provides peace of mind against the unexpected.
Key Takeaways for Victor Homeowners
- Choose Replacement Cost: This coverage ensures you can rebuild your home and replace your belongings without deductions for depreciation.
- Address Local Risks: Add endorsements for water backup and purchase a separate flood insurance policy to protect against common issues in our region.
- Review Annually: Your needs change, and so do construction costs. An annual review ensures your coverage remains adequate and you’re not underinsured.
- Bundle and Save: Combining your home and auto insurance is one of the easiest ways to save 15-20% or more on your premiums. Ask about other discounts for security systems, a claims-free history, and home safety features.
At Mitchell-Joseph Insurance Agency, we’ve been helping families in Victor and the Finger Lakes region for decades. As an independent agency, we work for you, not an insurance company. We leverage our relationships with 24 carriers to shop the market and find you the right Home Insurance Victor NY policy at a competitive price. Our team is committed to providing honest advice and personalized service to our neighbors.
Ready to feel confident in your home’s protection? Let’s work together to find the right coverage for your family.

