

The Critical Difference: Vacant vs. Unoccupied Homes
Home insurance for vacant property is essential when your house is empty for an extended time, as standard policies often drop coverage after 30-60 days. Understanding the difference between a vacant and an unoccupied home is the first step to ensuring you’re protected.
A vacant home is empty with no personal belongings, while an unoccupied home contains furniture, indicating an intent to return. Standard homeowners insurance is designed for occupied homes, and most policies include vacancy clauses that can void your coverage entirely if the home is empty for too long, leaving you exposed to major financial loss.
I’m Jeffrey Joseph of Mitchell-Joseph Insurance Agency. Since 1999, I’ve helped Finger Lakes homeowners steer complex insurance challenges, and I’ve seen how the right vacant property coverage can prevent financial disaster.
Why Standard Home Insurance May Not Be Enough
An empty home is a greater insurance risk than an occupied one. After 30 to 60 days, most standard policies can be voided, leading to claim denials even if you’ve paid your premiums. The risks are significant:
- Theft and Vandalism: Empty homes are prime targets for break-ins, theft of materials like copper piping, and vandalism such as graffiti or broken windows.
- Undetected Damage: A small water leak or minor storm damage can go unnoticed for weeks, leading to catastrophic structural problems, mold, and costly repairs.
- Fire Risk: Vacant properties face a heightened risk of arson. In some cities, arson at vacant buildings has reached record highs, underscoring the extreme vulnerability of empty structures.
Standard insurance isn’t built for these unique risks, which is why specialized home insurance for vacant property is a necessity for our clients across Honeoye Falls, Pittsford, and other Finger Lakes communities.
Defining ‘Vacant’ vs. ‘Unoccupied’ for Insurers
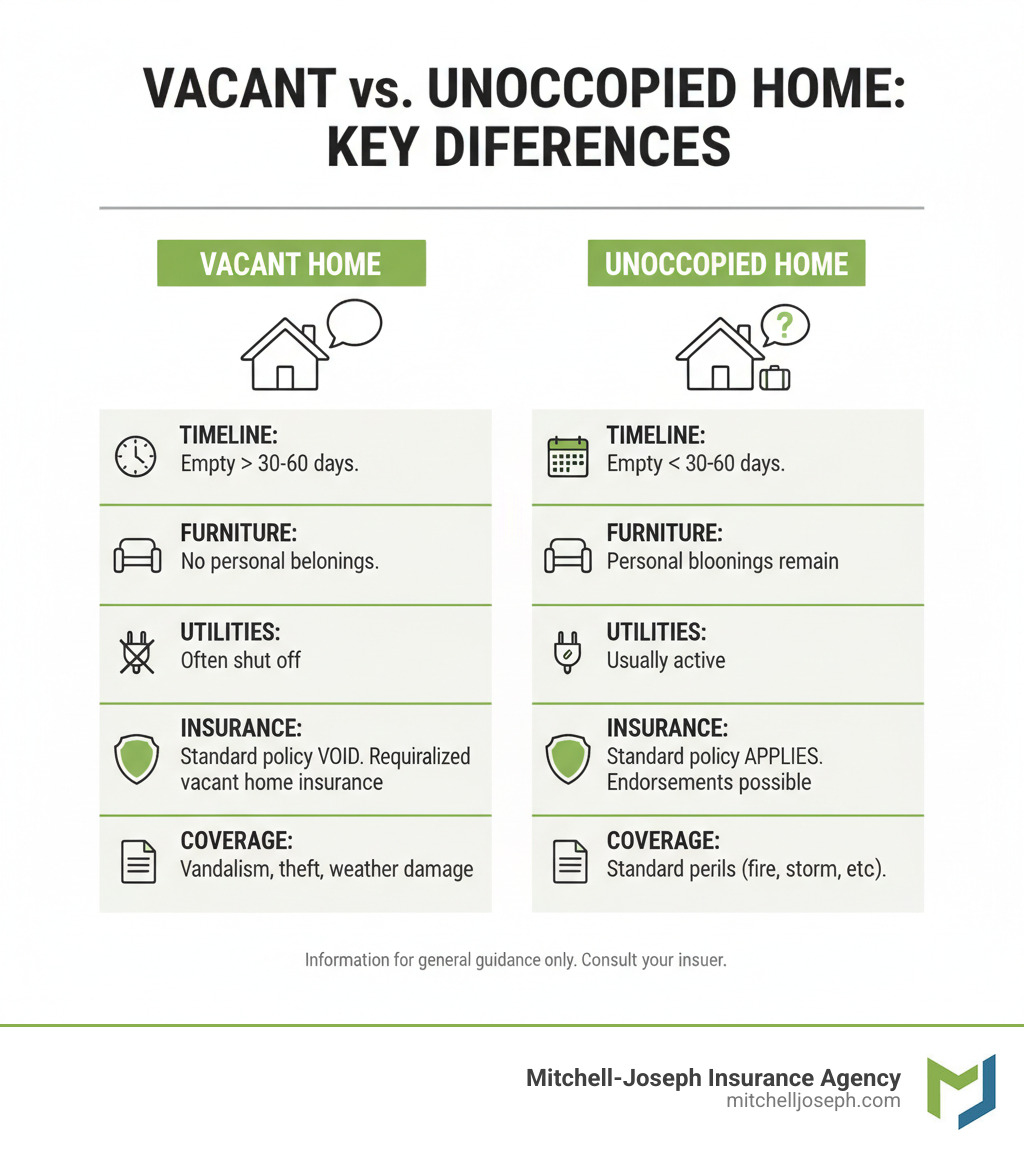
Insurance companies use precise definitions for “vacant” and “unoccupied,” and the distinction is key to your coverage.
- Unoccupied Home: The residents are temporarily away (e.g., vacation, business trip) but intend to return. The home is still furnished and ready to be lived in. Most policies allow for unoccupancy up to 30 days.
- Vacant Home: No one is living in the property, and there is no immediate plan for anyone to move in. The home is often empty of personal belongings, and utilities may be off. This applies to homes for sale, between tenants, or under renovation.
Here’s a quick comparison:
| Feature | Unoccupied Home | Vacant Home |
|---|---|---|
| Intent to Return | Yes, residents intend to return soon | No immediate intent for anyone to live there |
| Presence of Furniture | Still furnished, personal items present | Largely or completely empty of personal belongings |
| Utilities Status | Usually connected | May be shut off |
| Insurance Implications | Standard policy may cover short periods | Requires specialized home insurance for vacant property |
When a home is vacant, the risks increase dramatically. We help our clients in Canandaigua, Victor, and Mendon find the right specialized coverage for these situations.
A Comprehensive Guide to Home Insurance for Vacant Property

When you need home insurance for vacant property, you have a few options: a vacancy permit to temporarily extend your current policy, an endorsement to add specific vacancy coverage, or a completely separate policy designed for vacant homes.
Expect to pay 50% to 60% more than a standard policy. Costs are influenced by the length and reason for the vacancy, how often the property is checked, its condition, and your claim history. While it’s an added expense, it’s minor compared to the cost of an uninsured disaster.
Common Scenarios Requiring Specialized Coverage
Many situations can leave a home empty and in need of specialized coverage. We frequently help clients in the Finger Lakes region who are:
- Selling a home and have already moved out.
- Landlords with a rental property between tenants.
- Undergoing extensive renovations that make the home unlivable.
- Inheriting a property that will sit empty during the estate process.
- Away for extended travel, work, or medical stays.
- Owning a seasonal property that is vacant outside of the normal season.
What Does Home Insurance for Vacant Property Typically Cover?
Vacant property insurance usually covers specific “named perils” rather than offering broad protection. Key coverages often include:
- Fire and lightning: Essential protection, especially given the higher risk of arson in empty buildings.
- Windstorm and hail: Covers damage from severe weather, which can be devastating in our Finger Lakes winters.
- Explosions: Protects against damage from events like gas leaks.
- Vandalism and theft: Often available, though it may require specific security measures.
- Liability coverage: Crucial protection if someone is injured on your property, covering legal fees and potential lawsuits.
Most policies pay claims based on Actual Cash Value (ACV), which is the depreciated value of damaged items. Replacement Cost Value (RCV), which pays the full cost to replace items, may be available for a higher premium.
Common Exclusions and Additional Coverage Options
Understanding what isn’t covered is just as important. Common exclusions include:
- Water damage from burst pipes, especially from freezing if the property wasn’t properly winterized.
- Vandalism, theft, and glass breakage may be excluded or have strict limits on some policies.
- Mold and fungi, which can spread quickly in a damp, unmonitored home.
You can often fill these gaps with endorsements or separate policies, such as:
- Sewer backup coverage.
- Flood insurance, which is always a separate policy.
- Vacant land insurance for liability on empty lots without structures.
Navigating these options can be complex, but at Mitchell-Joseph Insurance Agency, we help you find the right balance of coverage and cost for your specific needs.
Proactive Protection and Securing the Right Coverage

Securing the right home insurance for vacant property is your financial safety net, but proactive measures are your first line of defense. Taking simple steps to secure your property can deter troublemakers, prevent damage, and may even lower your insurance premiums.
How to Protect Your Property and Reduce Insurance Costs
To make your vacant property less of a target, consider these essential steps:
- Arrange Regular Inspections: Have someone check the property weekly. A documented log of these visits is crucial for insurance claims.
- Boost Security: Install quality locks, an alarm system, and security cameras.
- Maintain the Exterior: Keep the lawn mowed and snow shoveled to make the house look cared for.
- Simulate Occupancy: Use light timers and ask a neighbor to park in the driveway occasionally.
- Inform Your Insurer: Always notify your insurance agent of a vacancy to prevent your policy from being voided.
- Prevent Water Damage: In our cold Finger Lakes climate, use a smart thermostat to monitor temperatures. For long-term vacancies, shut off the water, drain pipes, and winterize toilets.
- Manage Mail: Forward mail and stop deliveries to avoid a pile-up that signals an empty house.
Finding the Right Policy and Final Steps
Finding the right home insurance for vacant property can be challenging, as not all companies offer it. At Mitchell-Joseph Insurance Agency, we simplify the process. Our relationships with 24 different insurance carriers allow us to find competitive quotes custom to your unique situation.
We’ll help you conduct a thorough policy review, looking beyond the price to understand coverage limits, exclusions, and any specific requirements. As an independent, family-owned agency in Honeoye Falls, we have over 200 years of combined experience serving the Finger Lakes region, from Pittsford to Naples.
Our commitment is to personalized service. We take the time to understand your needs and provide clear, expert guidance. Your vacant property is a significant investment; let us help you protect it.

