Finding the Best Home Insurance in Rochester NY
When it comes to protecting your Rochester home, not all insurance providers are created equal. As a homeowner in our snow-laden corner of New York, you need coverage that understands our unique challenges.
The good news? Rochester residents enjoy surprisingly affordable home insurance rates compared to the rest of the nation. While you’re paying an average of $1,524 annually, homeowners across America shell out about $2,377 – that’s a significant savings that leaves more money in your pocket for those inevitable winter heating bills!
After helping hundreds of Rochester families find the right coverage over my 20+ years in the business, I’ve seen which home insurance companies Rochester NY consistently deliver the best value. Here are the standouts:
Some carriers offer remarkably budget-friendly options with rates as low as $402 per year for qualifying homes. Others provide impressive bundling discounts up to 25% when you combine home and auto policies. If you’re hunting for discounts, certain insurers provide numerous opportunities to lower your premium. For specialized coverage options, look for carriers that excel with extensive menus of optional protections. And of course, the most popular choices earn their reputation through reliability and exceptional service to Rochester homeowners.
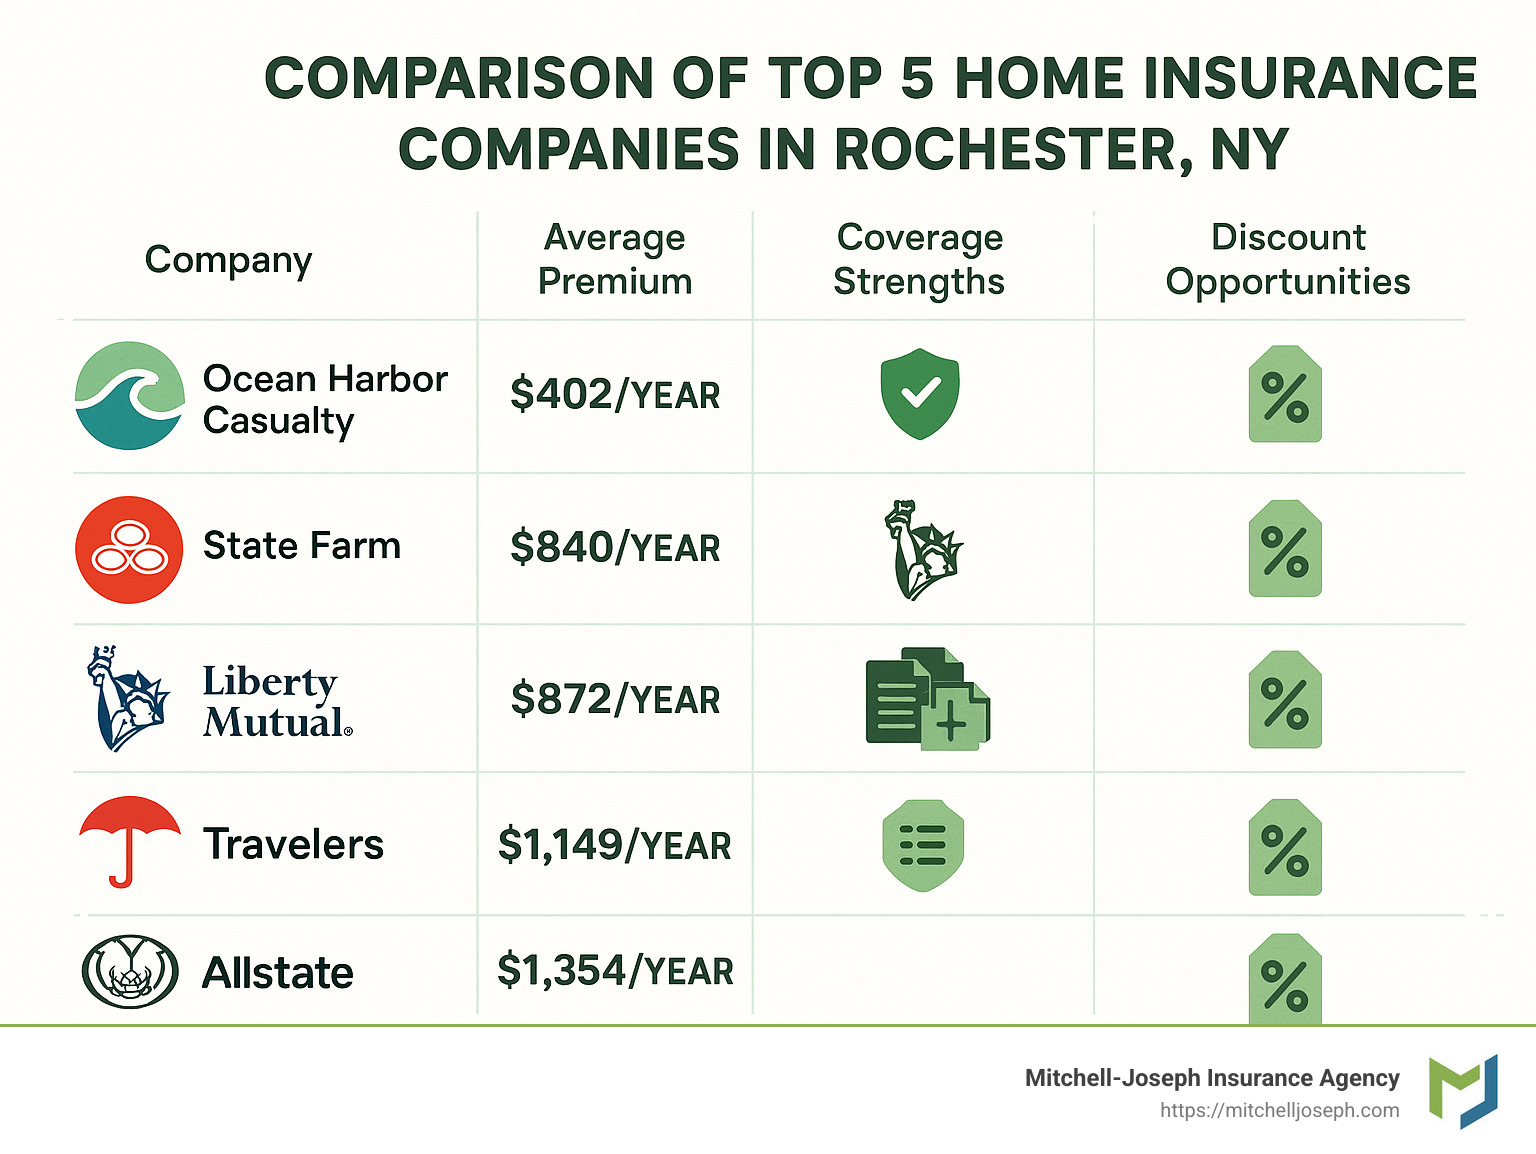
When comparing home insurance companies Rochester NY, remember to consider our region’s specific challenges. Our winters bring up to 120 inches of snow annually (that’s 10 feet!), we face higher-than-average property crime rates at 3,605 per 100,000 residents, and Lake Ontario occasionally reminds us of its presence with flooding concerns. Your ideal policy should address these realities.
I’m Jeffrey Joseph, and at Mitchell-Joseph Insurance Agency, my team and I don’t just sell policies – we build relationships. With three convenient locations throughout the Finger Lakes region, we’re your neighbors as well as your insurance advisors. We take pride in matching Rochester homeowners with coverage that truly fits their unique homes and lifestyles.
Whether you’re buying your first home or reviewing coverage for your long-time residence, we’re here to help steer the options from numerous home insurance companies Rochester NY with honest, personalized guidance.
Looking for more specific insurance information? Check out our resources on home insurance rochester, renters insurance rochester ny, or rochester ny insurance agencies.
Home Insurance Costs in Rochester for 2024
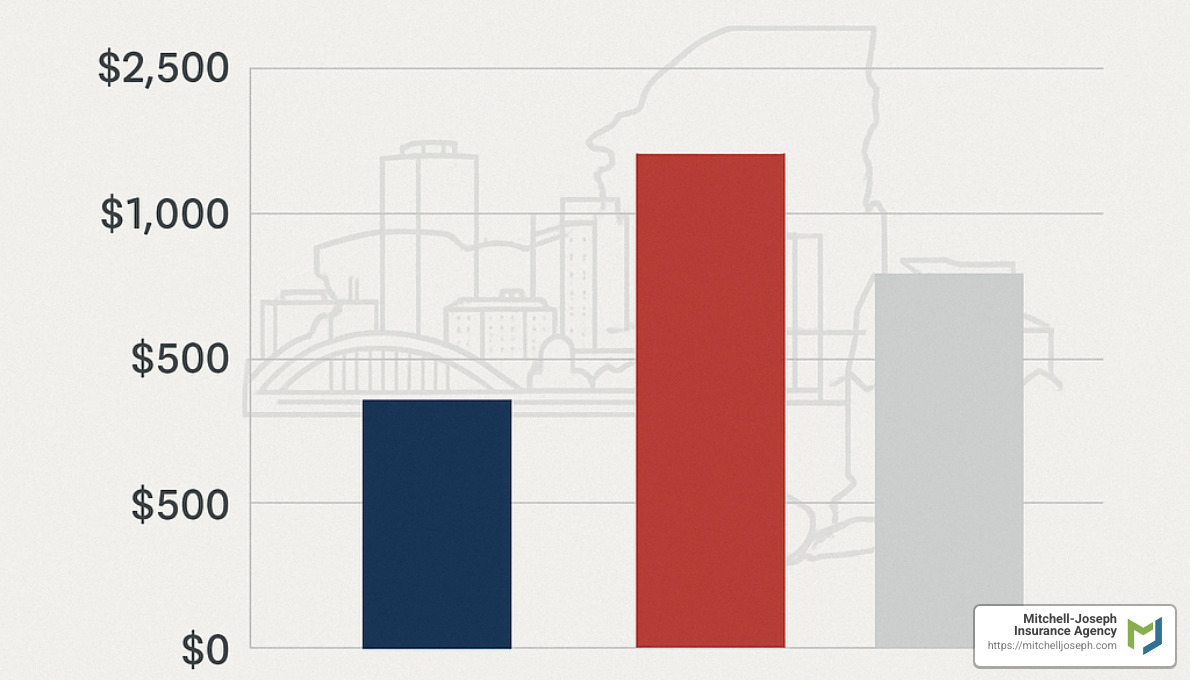
Good news for Rochester homeowners! Your wallet gets a bit of a break when it comes to protecting your home. If you’re shopping for home insurance companies Rochester NY, you’ll be pleased to know that our local premiums are quite reasonable compared to state and national averages.
The typical Rochester homeowner pays about $1,524 annually for standard coverage—that breaks down to just $127 per month. When you compare this to the New York state average of $2,257 or the national average of $2,377, the savings become pretty clear. It’s one of the financial perks of owning a home in our corner of New York!
Dwelling Coverage Tiers and Their Impact on Pricing
Your home’s rebuild cost (dwelling coverage) plays the biggest role in determining your premium. Here in Rochester, with our median home value of $159,900, most homeowners need to consider how much it would actually cost to rebuild rather than just looking at market value.
A modest home might need $100,000 in dwelling coverage, costing around $999 annually. Meanwhile, a larger or more custom home requiring $500,000 in coverage might see premiums around $3,640 per year. Most Rochester homes fall somewhere in between.
“I always tell my clients to aim for at least 80% of their home’s true replacement cost,” shares Brian Maust, one of our insurance specialists. “With Rochester’s housing market, many homeowners find they need between $200,000-$300,000 in coverage to adequately protect their investment.”
Deductible Choices and Premium Effects
Your deductible choice creates a simple trade-off: pay more now or pay more later. With a $500 deductible, your annual premium averages $1,569. Bump that up to a $1,000 deductible, and you’ll pay slightly less at $1,524 annually. Go higher to $2,500, and your premium drops to approximately $1,372.
We’ve seen many Rochester families save 10-15% on their premiums by choosing higher deductibles. But before you jump at those savings, consider this: could you comfortably come up with $2,500 out-of-pocket if your roof springs a leak during one of our famous lake-effect snowstorms? Only raise your deductible if you have the emergency funds to match.
Rochester vs. Other New York Cities
Rochester holds its own quite nicely when comparing insurance costs across the state. Our average premium of $1,524 beats Buffalo’s $1,689 and Albany’s $1,612. We’re in the same neighborhood as Syracuse at $1,566. All of us upstate folks enjoy significant savings compared to New York City’s whopping $2,873 average premium.
These differences aren’t random—they reflect each city’s unique risk factors. Our lower crime rates compared to some areas, responsive emergency services, and even how we’ve adapted to our winter weather patterns all contribute to keeping our insurance costs competitive.
Want to dig deeper into Rochester’s insurance landscape? Visit our detailed guide to Average Homeowners Insurance Rochester NY for more insights on how your specific neighborhood, home age, and other factors might affect your rates.
At Mitchell-Joseph Insurance Agency, we love helping homeowners understand these numbers and find the sweet spot between adequate protection and affordable premiums. After all, proper coverage doesn’t have to break the bank—especially here in Rochester.
Rochester Risks & Coverage Essentials
Living in Rochester means enjoying four distinct seasons, but it also means preparing for some unique challenges when it comes to protecting your home. As a Rochester homeowner myself, I’ve seen how our local weather patterns and other factors can impact insurance needs.
Weather-Related Risks
Lake-Effect Snow and Winter Weather
If you’ve spent even one winter here, you know that Rochester’s relationship with Lake Ontario creates quite the snowy situation! Our city regularly sees a whopping 120 inches of lake-effect snow annually. That’s ten feet of the white stuff!
“Most of our clients are surprised to learn just how much this extreme snowfall affects their insurance needs,” says Jeffrey Joseph, owner of Mitchell-Joseph Insurance Agency. “From potential roof collapses to those pesky ice dams that can force water into your attic, winter weather is probably our number one concern.”
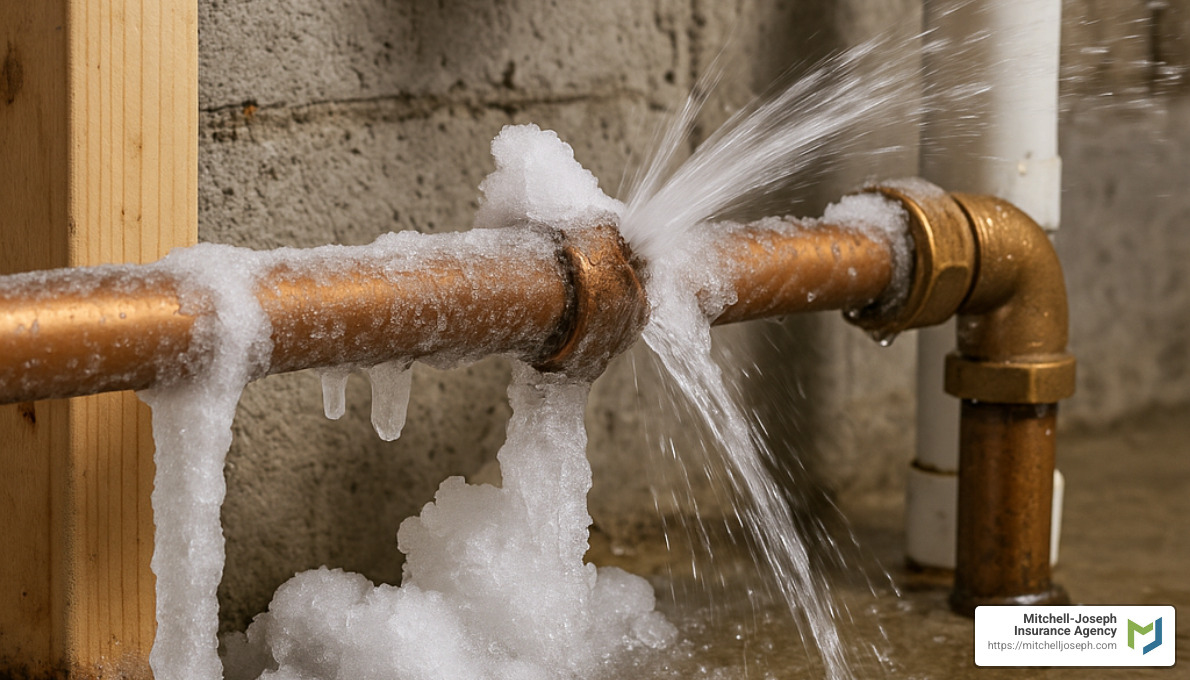
Standard home insurance companies Rochester NY typically cover most winter-related damages, including those dreaded frozen and burst pipes that can flood your basement when temperatures plummet. However, it’s worth checking your specific policy limits, especially if you own a historic home or have unique structures on your property.
Flooding and Water Concerns
Just this past January, Rochester neighborhoods experienced minor flooding from a combination of heavy rainfall and melting snow. It’s a reminder that water damage isn’t just a winter concern.
Here’s the important part many homeowners miss: standard policies typically do not cover flood damage. If you live near the Genesee River, Lake Ontario shoreline, or in one of Rochester’s low-lying areas, you’ll want to consider separate flood insurance through the National Flood Insurance Program (NFIP) or a private carrier.
Crime and Property Protection
Rochester’s property crime rate sits at 3,605 per 100,000 residents – significantly higher than the national average. While this might be concerning, the good news is that theft is covered under standard home insurance policies.
That said, if you have valuable jewelry, electronics, art collections, or other high-value items, you might need what we call “scheduled personal property endorsements” to ensure they’re fully protected. Think of it as extra protection for your most precious belongings.
Essential Coverage Components for Rochester Homes
Based on our local risks, here’s what a solid Rochester home insurance policy should include:
Dwelling Coverage protects your home’s structure against fire, windstorms, and vandalism. For Rochester’s median home value of $159,900, you’ll want to ensure your coverage reflects today’s rebuilding costs, not just market value.
Personal Property Coverage typically ranges from 50-70% of your dwelling coverage and protects everything from furniture to clothing. Given our higher-than-average property crime rates, this is particularly important in Rochester.
Liability Protection of at least $300,000 is recommended. This might seem high, but when someone slips on your icy sidewalk (a real concern with our winters!), you’ll be glad you have it.
Water Backup Coverage is an essential add-on in Rochester, especially in older neighborhoods with aging infrastructure. This endorsement covers damage from sewer or drain backups – something standard policies typically exclude.
Extended Replacement Cost provides a cushion (typically 25-50% above your limit) if rebuilding costs exceed expectations. With construction costs constantly rising, this can be a lifesaver.
For more comprehensive information about coverage types, visit our Home Insurance Coverage Types page. And if you’re curious about Rochester’s unique climate patterns, the National Weather Service Rochester Climate Information offers fascinating insights backed by scientific research.
At Mitchell-Joseph Insurance, we’ve helped thousands of Rochester homeowners steer these local risks. After all, protecting your home isn’t just about having insurance – it’s about having the right insurance for where you live.
How to Compare Home Insurance Options in Rochester
Shopping for home insurance in Rochester isn’t just about finding the lowest price. As a homeowner in our unique city, you’ll want to look deeper to find protection that truly fits your needs. Let me walk you through how to compare your options effectively.
Financial Strength and Stability
When winter storms blanket Rochester in snow, you need an insurer with the financial muscle to handle thousands of claims at once. Before signing on the dotted line, check their financial ratings from independent agencies. AM Best ratings of A or better, Standard & Poor’s ratings of AA or higher, and Moody’s ratings of Aa or better all signal an insurer with strong financial health.
These aren’t just fancy letters – they represent a company’s ability to be there when you need them most, even after a major weather event affects our entire community.
Claims Satisfaction and Customer Service
Your premium dollars don’t just buy coverage – they buy service. We’ve seen how a smooth claims process can make all the difference during stressful times. Take a few minutes to check J.D. Power ratings, the NAIC Complaint Index, and BBB scores before making your decision.
“I always tell my clients that saving $50 a year isn’t worth it if you’re fighting for your claim check when your pipes burst in February,” says our claims specialist at Mitchell-Joseph Insurance. “For Rochester homeowners, especially during our challenging winters, strong claims service is priceless.”
Local Expertise vs. National Resources
There’s something comforting about working with someone who knows exactly what it means when you say you live “near the bay” or “just off East Avenue.” Local agencies bring deep knowledge of Rochester neighborhoods and our unique risks. Meanwhile, national carriers offer robust 24/7 claims services and extensive resources.
At Mitchell-Joseph, we believe you shouldn’t have to choose. Our team combines hometown knowledge with access to 24 national insurance companies, giving you the best of both worlds – someone who understands your neighborhood backed by companies with significant resources.
Digital Tools and Accessibility
Today’s best insurers offer convenient digital tools like mobile apps, online policy documents, and digital claims filing. These features are wonderful time-savers for managing your policy on a typical day.
But when lake-effect snow dumps two feet overnight and damages your roof, having a local agent who can personally guide you through the claims process becomes invaluable. The ideal insurer offers both digital convenience and human support when you need it most.
Policy Customization Options
Rochester homes face unique challenges that may require special coverage. Look for insurers offering endorsements that matter here: water backup coverage for our aging infrastructure, scheduled personal property for your valuables, and service line coverage for those older neighborhoods with buried utility lines.
Other useful options include identity theft protection, home business coverage, and equipment breakdown coverage. The right insurer will help you customize a policy that addresses your specific concerns rather than selling a one-size-fits-all solution.
Bundling Opportunities
Nearly every Rochester homeowner can save by bundling policies. New York Central Mutual offers up to 25% savings when you combine home and auto coverage. Add umbrella coverage, and you might save an additional 10%. Even renters can benefit, with many carriers offering 5-15% discounts for bundling renters and auto policies.
These savings add up over time, often making a seemingly more expensive company the better value when all your policies are considered together.
Deductible Structure
Your deductible choice significantly impacts both your premium and your out-of-pocket costs when filing a claim. Some Rochester insurers offer innovative options like percentage-based deductibles (typically 1% of your dwelling coverage), separate wind/hail deductibles, or even disappearing deductibles that reduce over time.
I particularly appreciate companies that offer a single deductible option for multiple losses from the same event – imagine paying only one deductible when both your roof and fence are damaged in the same storm.
Getting Quotes: Timeline and Process
For the best results, start gathering quotes about 30-45 days before your current policy expires. Be prepared with detailed information about your home’s construction, features, and safety devices. Always request the same coverage limits across all quotes to ensure you’re making an apples-to-apples comparison.
Don’t forget to ask about all available discounts – many homeowners miss out on savings simply because they didn’t know to ask. Finally, review the quotes with an independent agent who can explain subtle differences in coverage that might not be obvious at first glance.
For more ways to save on your Rochester home insurance, check out our detailed guide to Homeowners Insurance Discounts.
Types of Home Insurance Providers Available in Rochester
When shopping for home insurance companies Rochester NY, you’ll find several distinct types of providers, each bringing something unique to the table. Understanding these differences will help you find the perfect partner to protect your Rochester home.
Independent Agencies: Personalized Service for Rochester Homeowners
Think of independent agencies like Mitchell-Joseph as your personal insurance shoppers. Instead of representing just one company, we work with multiple insurers to find you the best fit.
“Being independent means we can offer Rochester homeowners quotes from 24 different insurance companies,” I often explain to new clients. “We’re not tied to selling just one company’s policies, so we can truly find what works best for your specific situation.”
This approach offers several advantages for Rochester homeowners. You’ll receive personalized guidance from agents who genuinely understand our city’s unique risks, from lake-effect snow to aging infrastructure. We provide ongoing advocacy during claims and policy changes, and build long-term relationships that evolve as your insurance needs change. Plus, you’ll have access to multiple quote options without having to contact numerous companies yourself.
Independent agencies shine particularly bright for Rochester homeowners with unique properties, historic homes, or special coverage needs that don’t fit neatly into standard policies.
Mutual & Cooperative Providers: Community-Focused Alternatives
Several mutual insurance companies serve Rochester homeowners. What makes these companies special is their ownership structure – they’re owned by policyholders rather than shareholders.
This community-focused approach creates some wonderful advantages. Since mutuals aren’t focused on pleasing Wall Street investors, they can concentrate on member-oriented service. They typically have a community focus with deep understanding of local Rochester risks. Many offer competitive rates, especially for loyal members. Some even provide potential dividends during successful years, returning profits to members rather than shareholders.
Many mutual insurers have been serving New York homeowners for decades, building a reputation for fair rates and strong local knowledge that serves Rochester homeowners well.
Full-Service Carriers
The large national carriers you see advertised during sporting events offer comprehensive services with their own exclusive agents. These home insurance companies Rochester NY typically invest heavily in technology and customer service infrastructure.
These carriers excel at providing broad coverage options with extensive endorsements and add-ons. Their 24/7 claims service ensures around-the-clock support for emergencies – particularly valuable during Rochester’s winter storms. They typically offer advanced digital tools including sophisticated apps and online platforms, and provide multi-state coverage that’s seamless if you own property in multiple states.
Full-service carriers typically provide smooth experiences for straightforward claims, though they may lack the local expertise of Rochester-based providers.
Online & Direct Options
The digital revolution has brought direct-to-consumer insurers that bypass traditional agents. These companies offer a digital-first experience with streamlined online policy management and quick quotes – often providing instant online pricing.
The potential cost savings can be attractive, as their lower overhead may translate to lower premiums. Their self-service options include digital tools for policy changes and simple claims processing.
These options may appeal to tech-savvy Rochester homeowners comfortable managing their insurance digitally, though they sacrifice the personalized advice that local agents provide – advice that can be particularly valuable given Rochester’s unique weather patterns and housing stock.
Specialty & High-Risk Insurers
Some Rochester homes require specialized coverage due to their unique characteristics. Perhaps your home sits near Lake Ontario or the Genesee River in a flood zone. Maybe you own one of Rochester’s many historic homes built before 1940. Or perhaps you have a vacant or seasonal property that standard insurers won’t cover.
Specialty insurers fill these gaps with custom coverage options like flood insurance through NFIP or private carriers, historic home coverage with specialized restoration protection, high-value home policies for luxury properties, and vacant home insurance for unoccupied properties.
For more information about local agents who can help steer these specialized options, visit our Local Homeowners Insurance Agents page.
Quick Answers to Common Rochester Home Insurance Questions
How much does homeowners insurance cost in Rochester?
Rochester homeowners enjoy relatively affordable insurance rates, with an average annual premium of $1,524 for a policy with $300,000 in dwelling coverage and a $1,000 deductible. This is significantly lower than both the New York state average ($2,257) and the national average ($2,377).
Your specific rate will depend on several factors including your home’s age and construction, proximity to fire stations, security systems, claims history, credit-based insurance score (where legally permitted), and your chosen coverage limits and deductibles.
As I tell my clients, no two homes in Rochester are exactly alike, so your premium will be uniquely yours – just like your home.
Which factors can lower my Rochester home insurance premium?
You might be surprised by how many ways you can reduce your insurance costs. Many Rochester homeowners don’t realize they qualify for multiple discounts that could save them 15-30% through a combination of discounts and coverage adjustments.
Your home features can make a big difference – impact-resistant roofing, central alarm systems, water leak detection systems, and smart home monitoring devices all typically earn discounts. Recent updates to your roof, electrical, plumbing, or HVAC systems can also lower your rates.
Smart policy choices include bundling home and auto policies (saving up to 25%), increasing deductibles, paying annually instead of monthly, going paperless, and setting up automatic payments.
Personal factors that often reduce premiums include maintaining a claims-free history (typically saving 5-20%), loyalty discounts for long-term customers, senior discounts (usually for those 55+), new homebuyer discounts, and military/veteran discounts with qualifying companies.
Is flood insurance necessary near Lake Ontario?
This is one of the most important questions for many Rochester homeowners. The simple answer is: standard homeowners insurance policies exclude flood damage, regardless of the cause. For homes near Lake Ontario, the Genesee River, or in low-lying areas, separate flood insurance is strongly recommended.
When deciding about flood insurance, consider your FEMA flood zone designation, the history of flooding in your neighborhood, your basement features and contents, proximity to bodies of water, and your property’s elevation.
Even homes outside designated flood zones can experience flooding from heavy rainfall, rapid snowmelt, or water main breaks – all too common in Rochester’s climate. The National Flood Insurance Program (NFIP) provides coverage, as do several private insurers serving Rochester.
At Mitchell-Joseph Insurance Agency, we’ve helped countless Rochester homeowners assess their flood risk and secure appropriate coverage, whether through the NFIP or private market options that may offer more competitive rates and broader coverage.
Conclusion
Navigating the landscape of home insurance companies Rochester NY requires understanding both the unique risks of our region and the diverse provider options available. With Rochester’s significant snowfall, above-average property crime rates, and occasional flooding concerns, having the right coverage is essential for protecting your most valuable asset.
When comparing home insurance providers, the lowest premium doesn’t always indicate the best value. Consider:
- Financial strength and claims satisfaction ratings
- Coverage options custom to Rochester’s specific risks
- Local expertise versus national resources
- Digital tools and accessibility
- Bundling opportunities and discount availability
For most Rochester homeowners, a strategic approach includes:
- Customizing coverage to address winter weather risks, potential water damage, and adequate personal property protection
- Comparing quotes from different provider types—independent agencies, mutual companies, national carriers, and direct insurers
- Balancing deductibles and premiums to find the sweet spot between monthly affordability and out-of-pocket exposure
- Reviewing policies annually to ensure coverage keeps pace with home improvements and changing values
At Mitchell-Joseph Insurance Agency, we’ve been helping Rochester homeowners steer these decisions for decades. With our access to 24 insurance companies and deep understanding of local risks across neighborhoods from Pittsford to Canandaigua, we’re uniquely positioned to find the right coverage for your specific needs.
Whether you’re insuring a historic home in Rochester’s older neighborhoods, a modern suburban property, or a seasonal lake house, we can help you compare options and secure protection that gives you confidence through every season—especially our challenging winters.
For personalized assistance with your Rochester home insurance needs, contact Mitchell-Joseph Insurance Agency today. Our team is ready to leverage our 200+ years of combined experience to help you protect what matters most.
For more information about our home insurance services, visit our Home Insurance page.