

Why Finding the Right Home Insurance Agent Matters
A home insurance agent can save you hundreds of dollars annually while ensuring your most valuable asset gets proper protection. Whether you’re shopping for your first policy or frustrated with limited options from your current provider, the right agent makes all the difference.
Quick Answer: What Does a Home Insurance Agent Do?
• Shop multiple carriers to find the best coverage and price
• Analyze your specific needs and recommend appropriate coverage levels
• Explain complex policy terms in plain language
• Advocate for you during claims to ensure fair settlements
• Review your policy annually to catch gaps or savings opportunities
The insurance landscape has evolved dramatically. With more than 40,000 independent insurance agents operating nationwide, homeowners now have access to extensive carrier networks and personalized service that online-only platforms simply can’t match.
Independent agents can compare quotes from dozens of companies with a single phone call, while captive agents offer deep expertise with specific carriers like State Farm’s network of over 19,000 agents. The key is understanding which type serves your unique situation best.
Finding quality representation shouldn’t feel overwhelming. This guide breaks down exactly how to identify, evaluate, and work with the right home insurance agent for your needs – whether you’re protecting a single-family home, rental property, or need specialized coverage for valuable collections.
I’m Jeffrey Joseph, owner of Mitchell-Joseph Insurance Agency, and I’ve been helping Finger Lakes region homeowners steer their insurance choices since 1999. As both an independent home insurance agent and someone who understands the frustrations of limited options and high premiums, I’ll walk you through the exact process for finding an agent who truly serves your interests.
Why Work With a Home Insurance Agent?
Finding the right home insurance agent feels like finding a trusted advisor who genuinely cares about protecting your family’s future. After decades of helping homeowners across the Rochester and Finger Lakes region, we’ve witnessed countless moments where the right agent relationship made all the difference between financial security and devastating loss.
Think about it this way: your home represents years of hard work, memories, and dreams. Would you really want to protect all of that with a one-size-fits-all policy from a website that doesn’t know you from the next customer?
Personalized advice transforms insurance from a confusing maze into a clear protection plan. When you work with a skilled agent, they take time to understand your unique situation. Maybe you’ve got a vintage guitar collection in the basement, or you run a small business from your home office. Perhaps your teenage driver just got their license, or you’re planning a major kitchen renovation. A good agent considers all these details when crafting your coverage recommendations.
The coverage matching process reveals why agents earn their keep. We recently helped a family in Canandaigua who thought they had adequate coverage through an online provider. When we reviewed their policy, we finded they were underinsured by nearly $200,000 on their home’s replacement cost. That’s the kind of gap that can destroy a family’s financial future after a total loss.
Discount hunting becomes an art form with experienced agents. Most homeowners leave money on the table because they don’t know what discounts exist. Bundle your home and auto insurance, and you might save hundreds annually. Install a smart security system or update your roof, and additional savings appear. We’ve seen clients reduce their premiums by over $1,000 per year just by taking advantage of overlooked discounts.
When disaster strikes, claims advocacy separates great agents from the rest. Your agent becomes your personal champion during the most stressful time imaginable. They help document damage, explain what your policy covers, and push back when insurance companies try to lowball settlements. It’s like having a knowledgeable friend who speaks fluent insurance fighting in your corner.
Local expertise matters more than you might expect. Agents who understand regional weather patterns, common risks, and local building costs provide insights that generic online platforms simply can’t match. We know that homes near the Finger Lakes face unique ice dam risks during winter. We understand how lake-effect snow impacts different neighborhoods differently. This knowledge directly impacts the coverage recommendations we make.
| Feature | Captive Agent | Independent Agent |
|---|---|---|
| Carrier Options | Single company | Multiple companies (often 10-24) |
| Product Knowledge | Deep expertise in one carrier’s products | Broad knowledge across multiple carriers |
| Price Comparison | Limited to one company’s rates | Can compare rates across many carriers |
| Loyalty Benefits | Access to exclusive company programs | Flexibility to switch carriers if needed |
| Local Presence | Often strong local presence | Varies by agency |
What Does a Home Insurance Agent Do?
A professional home insurance agent wears many hats throughout your relationship, and understanding these roles helps you appreciate the value they bring to your financial security.
Needs analysis starts every great agent relationship. During your first meeting, expect detailed questions about your lifestyle, property, and concerns. A thorough agent wants to know about recent home improvements, valuable possessions, family changes, and future plans. They’re not being nosy – they’re gathering information to build the most effective protection plan for your specific situation.
Policy shopping showcases where independent agents truly shine. Instead of spending your weekends calling different insurance companies or filling out endless online forms, your agent handles the heavy lifting. With access to multiple carriers, they can generate comprehensive quotes in minutes rather than the hours or days it would take you to do the same research.
Coverage explanation transforms insurance jargon into plain English. Your agent should clearly explain why replacement cost coverage costs more than actual cash value, help you choose deductibles that balance premium savings with out-of-pocket risk, and identify potential gaps before they become expensive problems. If you leave a meeting feeling confused about your coverage, that’s a red flag about your agent’s communication skills.
Claims support extends far beyond selling you a policy. When you need to file a claim, your agent guides you through documentation requirements, communicates with adjusters on your behalf, and monitors progress to ensure fair treatment. This ongoing advocacy often determines whether your claims experience feels smooth or becomes a nightmare.
Home Insurance Agent vs Online DIY
Choosing between a home insurance agent and online platforms involves trade-offs that vary based on your comfort level, time availability, and coverage complexity. Our experience helping Finger Lakes families steer these decisions reveals important considerations.
Human guidance provides context that no algorithm can replicate. When a Honeoye Falls homeowner asks about coverage for their historic farmhouse, an experienced local agent understands unique challenges like outdated electrical systems, replacement cost issues for period materials, and heating system risks that might not surface during an online questionnaire.
Error reduction becomes critical when dealing with coverage decisions that could impact your family’s financial future. We regularly review policies purchased online and find concerning gaps or inappropriate coverage levels. One recent client had purchased a policy online that excluded water damage from their basement – a costly oversight they finded only when we reviewed their coverage during a consultation.
Time savings might seem backwards since online quotes promise instant results. However, the time invested in agent consultations often pays significant dividends through better coverage selection and smoother claims experiences. One client recently shared that our guidance during a house fire claim saved them weeks of frustration and thousands in out-of-pocket expenses.
Negotiation leverage gives agents tools that individual consumers lack. When carriers propose rate increases or dispute claim settlements, agents can leverage their business relationships and industry expertise to advocate for better outcomes. You’re not just another policy number – you’re part of their business reputation.
Types of Agents & How They Get Paid
Understanding how home insurance agents operate and earn their income helps you make better decisions about who to work with. It’s not complicated, but knowing these basics ensures you choose an agent whose interests align with yours.
Captive agents work for just one insurance company. Think of them as that company’s dedicated representatives. They know their carrier’s products inside and out, which can be incredibly valuable when you need specialized coverage or have complex claims. These agents often have direct phone lines to underwriters and can sometimes get answers faster than independent agents.
Independent agents like us at Mitchell-Joseph Insurance Agency work with multiple companies. We represent 24 different carriers, which means we can shop around to find you the best combination of coverage and price. Instead of being married to one company’s rates and rules, we have the freedom to move your business if a carrier isn’t treating you fairly.
Commission structures are pretty straightforward in our industry. Most home insurance agents earn between 10-15% of your annual premium when you first buy a policy. After that, we typically earn smaller renewal commissions each year you stay with us. This system actually works in your favor – we make more money when you’re happy and stick around.
Fee-based services aren’t common for regular home insurance, though some agents charge consulting fees for complex commercial risks or specialized advice. For most homeowners, you won’t pay any direct fees to your agent. The insurance company pays us from their marketing budget.
Transparency about how we get paid builds trust. Good agents will openly discuss their compensation and focus on finding coverage that works for you, not just maximizing their paycheck. When an agent recommends a particular carrier or coverage level, you should feel confident they’re thinking about your needs first.
Incentive alignment happens naturally when agents focus on long-term relationships over quick sales. Independent agencies that have earned recognition as a Great Place to Work often demonstrate this commitment to ethical practices and client satisfaction.
The bottom line? Whether your agent earns $200 or $400 in commission shouldn’t drive their recommendations. Look for agents who ask detailed questions about your situation and explain their reasoning clearly.
Captive vs Independent: Pros & Cons
Choosing between captive and independent agents isn’t about right or wrong – it’s about what works best for your situation. Both types can provide excellent service, but they operate differently.
Captive agents bring deep expertise about their company’s products. When you call with questions about your policy, they know exactly how their carrier handles different situations. They often have special access to underwriters and claims departments, which can speed up processes. Plus, their company may offer loyalty discounts or exclusive programs for long-term customers.
The trade-off? Carrier choices are limited to whatever their company offers. If their rates go up significantly or their coverage doesn’t fit your needs anymore, your only option is finding a new agent with a different company.
Independent agents offer flexibility that many homeowners find valuable. We can compare quotes from multiple carriers and help you switch companies without changing agents. If one carrier disappoints you with poor claims service or big rate increases, we can move your business elsewhere while maintaining the relationship you’ve built with us.
Bundling options often work better with independent agents because we can compare bundle deals across different companies. Instead of being limited to one company’s auto and home package, we can mix and match to find the best overall deal.
Local presence depends more on the individual agent than whether they’re captive or independent. Both types can provide excellent local service. However, independent agencies often develop stronger community ties because we’re not constrained by corporate policies about local involvement.
Potential conflicts exist in both models. Captive agents might push their company’s products even when competitors offer better deals. Independent agents might favor carriers that pay higher commissions. The key is finding an agent who’s transparent about these dynamics and prioritizes your interests.
How to Choose the Right Home Insurance Agent Near You
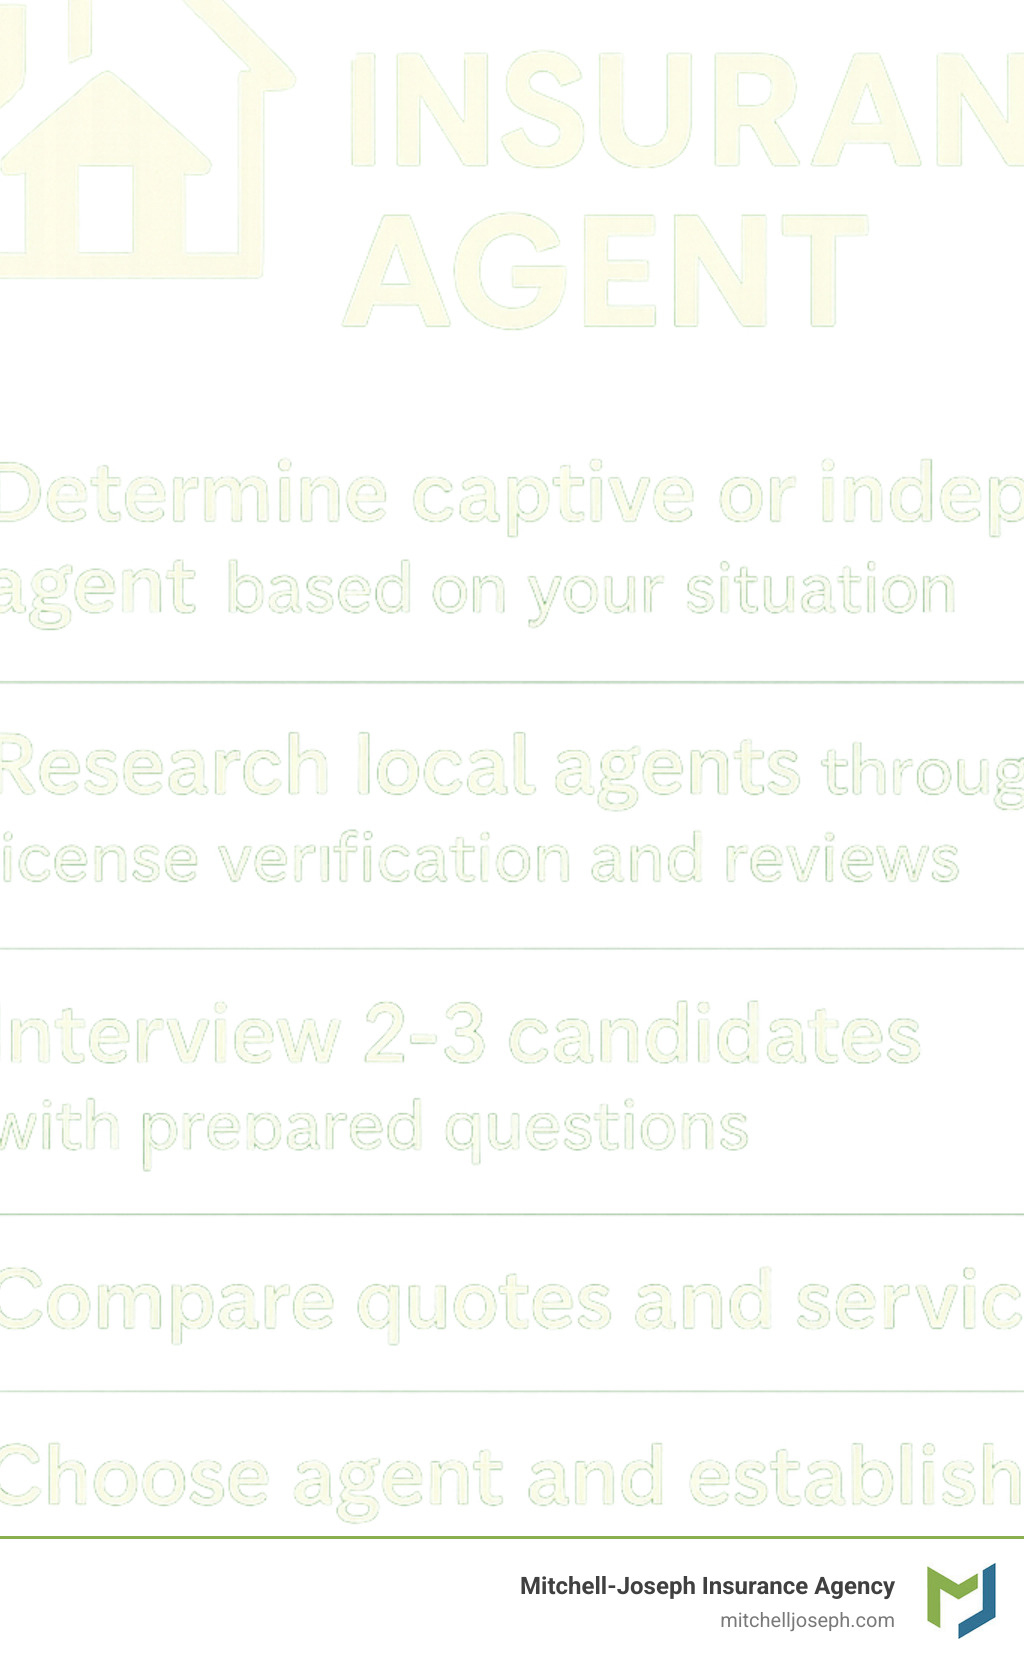
Finding the right home insurance agent doesn’t have to feel like searching for a needle in a haystack. After helping thousands of families in the Rochester area, we’ve learned that the best agent relationships start with a bit of homework and the right questions.
Start with license verification – it’s like checking someone’s driver’s license before getting in their car. Every state runs an online database where you can confirm your potential agent actually has the credentials they claim. New York’s Department of Financial Services makes this easy and free. You’d be surprised how this simple step weeds out the pretenders.
Reputation tells the real story beyond any slick marketing materials. Online reviews give you a glimpse into how agents handle both good times and stressful claim situations. But don’t stop there – ask potential agents for references from current clients. Any home insurance agent worth their salt will happily connect you with satisfied customers who can share their real experiences.
The best referrals often come from people you already trust. Your neighbor who just went through a smooth claim process, your realtor who sees agents in action regularly, or your mortgage broker who works with insurance professionals daily – these folks have insider knowledge about who actually delivers on their promises.
Digital detective work reveals a lot about how agents operate. Professional websites, active social media presence, and thoughtful responses to online reviews all signal an agent who takes their reputation seriously. If someone can’t maintain a basic online presence in 2024, how well will they handle your policy details?
The interview process separates the relationship-builders from the quick-sale artists. Prepare specific questions about their experience with properties like yours, their carrier relationships, and how they handle claims. Pay attention to whether they’re asking thoughtful questions about your needs or just trying to rush you toward a signature.
Here in the Finger Lakes region, we understand the unique challenges homeowners face – from ice dam damage during brutal winters to flooding risks near our beautiful lakes. Our team at Mitchell-Joseph Insurance Agency brings over 200 years of combined experience and relationships with 24 different insurance companies. We’ve built our reputation one satisfied family at a time over more than two decades. Learn more about our local homeowners insurance agents and find how we serve communities throughout Monroe, Ontario, and surrounding counties with the personal attention your family deserves.
Questions to Ask Your Home Insurance Agent
Walking into an agent meeting with the right questions transforms what could be a confusing sales pitch into a productive conversation about protecting your home. Think of these questions as your roadmap to finding an agent who truly understands your needs.
Coverage limits deserve your first attention: “How do you determine the right dwelling coverage for my home?” A skilled agent will walk you through replacement cost calculations, explain inflation guard protection, and help you understand why the 80% rule matters. They should talk about local construction costs, not just pull numbers from thin air.
Deductible discussions reveal how well an agent understands your financial picture. Ask “What deductible options make sense for my situation?” The right home insurance agent will explain how higher deductibles lower your premiums but increase your out-of-pocket costs during claims. They’ll help you find that sweet spot between affordable premiums and manageable claim expenses.
Special possessions often surprise homeowners during claims. “How does my policy handle jewelry, artwork, or my husband’s vintage guitar collection?” Standard policies typically cap coverage for these treasures at frustratingly low amounts. Your agent should explain scheduling options and additional coverage without making you feel foolish for asking.
Discount opportunities can save you hundreds annually, but only if your agent actively seeks them out. “What discounts am I missing, and how can I qualify for more savings?” Push for specifics about bundling deals, safety device credits, loyalty rewards, and those new smart home technology incentives that many homeowners don’t even know exist.
Review schedules separate proactive agents from the “sell and forget” crowd. “How often will you review my coverage, and what triggers a policy evaluation?” Quality agents schedule annual check-ins and reach out when life changes affect your insurance needs – new babies, home renovations, or that boat you finally bought.
Don’t forget to ask about their claims support process, how many carriers they work with, and their preferred communication style. The best agents welcome these questions because they know informed clients become satisfied long-term relationships.
Information You’ll Need for a Quote
Getting accurate quotes from a home insurance agent works best when you come prepared with the right information. Think of it as gathering ingredients before cooking – having everything ready makes the whole process smoother and more successful.
Your home’s vital statistics form the foundation of any quote. Gather details about your home’s age, square footage, construction materials, and architectural style. That recent appraisal or tax assessment provides a helpful starting point, though remember that insurance replacement costs often run higher than market values because they reflect actual rebuilding expenses.
Replacement cost thinking requires a different mindset than market value. Consider what you’ve spent on recent renovations, research local construction costs, and think about unique features that would cost extra to rebuild. Your agent will help refine these numbers, but starting with ballpark figures speeds up the conversation significantly.
Claims history affects both your rates and coverage options more than most homeowners realize. Dig up information about any claims filed in the past five years – dates, amounts, and what caused the damage. Even claims from previous owners can impact your rates, so don’t assume a clean slate just because you recently bought the house.
Safety features around your home translate directly into premium savings. Document your security system, smoke detectors, fire extinguishers, and any other protective devices. Smart home technology increasingly qualifies for discounts, so mention those connected thermostats, water leak sensors, and security cameras.
Credit information influences your rates in most states, though agents can’t magically improve your score overnight. They can explain how credit affects your premiums and help you find carriers that place less emphasis on credit factors if that’s a concern.
Understanding home insurance coverage types before your meeting helps you ask smarter questions and make better decisions about protecting your most valuable investment.
Money-Saving Strategies Your Agent Can Open Up
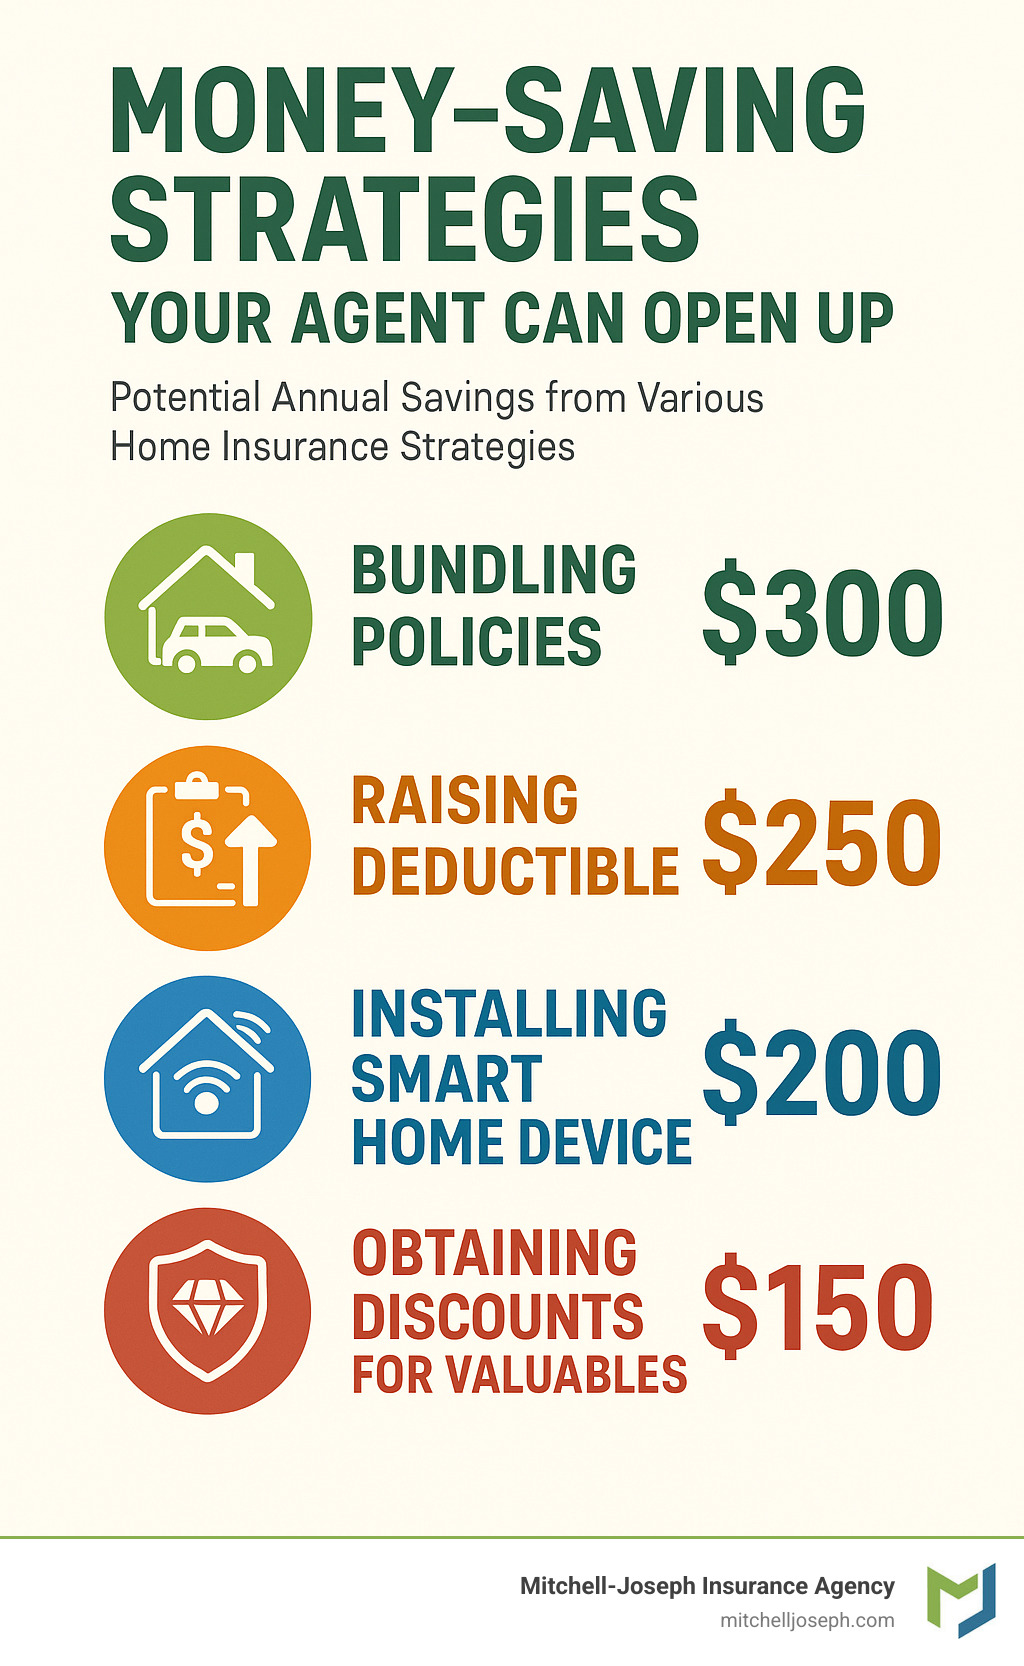
A skilled home insurance agent acts like a savings detective, hunting down discounts and strategies that can put hundreds of dollars back in your pocket each year. Many homeowners pay more than necessary simply because they don’t know what opportunities exist.
Bundling home and auto insurance often delivers the biggest bang for your buck. When you combine policies with the same carrier, you can save substantial amounts – sometimes over $1,000 annually. The beauty of working with an independent agent is they can compare bundle deals across multiple companies to find the sweet spot for your situation.
Smart home technology isn’t just convenient – it can shrink your premiums too. Water leak sensors that text you when trouble starts, smart smoke detectors that alert your phone, and security systems all signal to insurance companies that you’re serious about preventing claims. Some carriers reward comprehensive smart home setups with discounts up to 15%.
Your home insurance agent becomes your personal maintenance coach, sharing tips that prevent costly claims before they happen. Simple habits like cleaning gutters, checking your roof after storms, and maintaining your HVAC system keep your home in good shape while showing insurers you’re a responsible homeowner.
Regular review cycles ensure you never miss savings opportunities as your life changes. Maybe you’ve paid off your mortgage, installed a new security system, or reached a milestone birthday that qualifies for senior discounts. Annual check-ins with your agent catch these money-saving moments.
At Mitchell-Joseph Insurance Agency, we’ve finded that many of our Finger Lakes region clients were missing out on homeowners insurance discounts worth hundreds of dollars annually. From loyalty credits to safety improvements you’ve already made, these savings add up quickly when you know where to look.
The insurance industry increasingly uses targeted online advertising and savings programs to offer personalized discounts, making your agent relationship even more valuable for accessing these specialized opportunities.
Special Coverage Needs: Jewelry, Collectibles & Home Business
Your grandmother’s engagement ring, your baseball card collection, or that pottery business you run from your spare bedroom all need special attention that standard homeowners policies don’t provide. A knowledgeable home insurance agent helps you spot these coverage gaps before they become expensive surprises.
Scheduled personal property gives your valuables the VIP treatment they deserve. While your standard policy might cover only $1,500 for jewelry or $2,500 for artwork, scheduling these items individually provides full replacement value coverage without any deductible. Your agent can connect you with appraisers and handle the paperwork.
Policy endorsements work like add-ons that expand your coverage for specific situations. Water backup coverage protects when your basement floods from a backed-up sewer line. Equipment breakdown coverage handles when your expensive appliances fail outside of normal wear and tear.
Home-based businesses need careful attention since standard homeowners policies exclude most business activities. Whether you’re selling crafts online or running a consulting practice, your agent can recommend business endorsements or separate commercial policies to protect your income and equipment.
Umbrella liability policies provide an extra safety net for people with significant assets or higher lawsuit risks. For a relatively small premium, umbrella coverage adds another layer of protection that kicks in when your homeowners liability limits are exhausted.
How Often to Review Your Policy
Think of your insurance policy like a living document that needs regular check-ups to stay healthy. Your home insurance agent should be proactive about scheduling these reviews, not waiting for you to remember.
Annual policy reviews should happen automatically with any quality agent. These meetings catch important changes like new discount opportunities, coverage gaps from home improvements, or adjustments needed for rising construction costs. Even if nothing major has changed in your life, the insurance market constantly evolves with new products and pricing.
Major life events trigger immediate review needs. Getting married or divorced, having children, retiring, or inheriting valuable items all affect your insurance requirements. Your agent should ask about these changes and adjust your coverage accordingly.
Home renovations almost always require coverage updates. That beautiful new kitchen or master bedroom addition increases your home’s replacement cost. Notify your agent before starting major projects – some improvements might even qualify for additional discounts.
Inflation protection keeps your coverage amounts current with rising construction costs, but automatic adjustments don’t always keep pace with reality. Regular reviews ensure your coverage limits remain adequate, especially during periods when material and labor costs spike unexpectedly.
The key is finding an agent who treats these reviews as relationship-building opportunities rather than sales pitches. Quality agents focus on ensuring your protection stays current with your needs, knowing that satisfied clients become long-term relationships.
Claims & Ongoing Support
When disaster strikes your home, that’s when you find the real difference between having just an insurance policy and having a trusted home insurance agent in your corner. After helping thousands of families through everything from kitchen fires to ice dam damage here in the Finger Lakes region, I can tell you that proper claims support often makes the difference between a manageable situation and a nightmare.
Pre-loss preparation might sound boring, but it’s like having a fire extinguisher – you hope you’ll never need it, but you’ll be grateful when you do. A good agent helps you get ready before anything happens. They’ll walk you through creating a proper home inventory, explain exactly how your carrier’s claims process works, and even introduce you to reliable contractors in your area.
Think about it this way: when you’re dealing with water pouring through your ceiling at 2 AM, the last thing you want to do is figure out your insurance company’s phone tree or wonder if the restoration company you found online is legitimate.
Home inventory documentation becomes your best friend during claims. Your agent should guide you through photographing your belongings, storing receipts safely (cloud storage works great), and updating everything when you buy new items. It sounds tedious until you’re trying to remember every item in your flooded basement three months later.
Filing steps can feel overwhelming when you’re stressed about damage to your home. Your home insurance agent becomes your translator and guide through the entire process. They know exactly what information the adjuster needs, how to document damage properly, and when it makes sense to get repair estimates versus waiting for the insurance company’s assessment.
Contractor networks maintained by experienced agents save you time and worry during an already stressful period. We’ve built relationships with reliable contractors over decades of serving this community. When your furnace dies in January or a tree crashes through your roof, you don’t want to spend hours researching repair companies.
Settlement tracking ensures your claim doesn’t get lost in the shuffle. Insurance companies handle thousands of claims, but your agent focuses on making sure yours moves forward appropriately. They know when delays are reasonable and when it’s time to escalate issues.
How a Home Insurance Agent Helps During Claims
The difference between handling a claim alone versus having an experienced home insurance agent advocate for you is like the difference between representing yourself in court versus hiring a lawyer. You could do it yourself, but why would you want to?
Documentation guidance from your agent ensures you don’t accidentally hurt your own claim. They know that taking photos before cleaning up debris matters, that keeping receipts for temporary housing helps, and that certain statements to adjusters can be misinterpreted later. It’s not about gaming the system – it’s about making sure you get the coverage you’ve been paying for.
Advocacy becomes crucial when things get complicated. Maybe the adjuster’s estimate seems low, or there’s confusion about whether certain damage is covered. Your agent speaks the insurance company’s language and understands policy terms that might as well be written in ancient Greek to most homeowners.
Progress monitoring keeps your claim moving when you have a hundred other things to worry about. While you’re dealing with contractors, temporary housing, or just the emotional stress of damage to your home, your agent stays on top of paperwork, follows up with adjusters, and identifies potential delays before they become major headaches.
Stress reduction might be the most valuable service we provide during claims. One client recently told me that knowing we were handling the insurance side of their kitchen fire let them focus on taking care of their family instead of fighting with bureaucracy. That’s exactly how it should work.
When you’re choosing a home insurance agent, ask them about their claims support process. How quickly do they respond when you call about damage? Do they visit the property during major claims? How do they communicate with you throughout the process? The answers to these questions matter far more than saving a few dollars on your premium.
Frequently Asked Questions about Home Insurance Agents
Let’s tackle the most common questions homeowners ask about working with insurance agents. These answers come from real conversations we’ve had with clients throughout the Rochester and Finger Lakes region.
How does a home insurance agent get paid?
Home insurance agents earn their income through commissions paid by insurance companies, not from extra fees added to your premium. When you purchase a new policy, agents typically receive 10-15% of your annual premium as commission. Renewal commissions are much lower – usually 2-5% – which means agents succeed by keeping clients happy over the long term.
Independent agents like our team at Mitchell-Joseph may also earn bonus commissions based on the total business volume they write with specific carriers. This might sound concerning, but it actually works in your favor. These bonuses help us maintain strong relationships with our 24 insurance companies, often giving us access to better rates and faster claim service.
The commission structure naturally aligns our interests with yours. We make more money when you stay satisfied and renew your policy year after year. That’s why quality agents focus on finding the right coverage at fair prices rather than pushing expensive policies for higher commissions.
Can a home insurance agent really lower my premiums?
Absolutely! A skilled home insurance agent can often find significant savings that homeowners miss when shopping on their own. Our clients regularly save hundreds of dollars per year – sometimes over $600 – when we help them switch carriers or optimize their existing coverage.
Independent agents provide the biggest advantage here because we can compare rates across multiple companies with a single application. While you might spend hours getting quotes from different websites, we can generate 10-15 competitive quotes in minutes through our carrier relationships.
Beyond rate shopping, agents excel at finding hidden discounts. We know which carriers offer the best credits for smart home devices, security systems, or bundling policies. Many homeowners leave money on the table simply because they don’t know these opportunities exist.
We also help optimize your coverage structure. Sometimes raising your deductible from $500 to $1,000 can save $200 annually – money that quickly covers the higher deductible if you ever file a claim. Or we might find you’re paying for coverage you don’t actually need.
What’s the difference between a captive and an independent home insurance agent?
This question gets to the heart of how you want to shop for insurance. Captive agents work for just one insurance company – they can only sell that company’s products. Think of agents who work exclusively for major carriers. They know their company’s offerings inside and out and often have direct connections to underwriters and claims specialists.
Independent agents like our team represent multiple insurance companies. We work with 24 different carriers, which means we can compare options and find the best fit for your specific situation. If one company raises your rates or doesn’t handle your claim well, we can move you to a different carrier without you needing to find a new agent.
The choice comes down to your priorities and situation. Captive agents make sense if you’re already happy with a specific company and want deep expertise in their products. They might have access to exclusive programs or discounts not available elsewhere.
Independent agents work better for most homeowners because we provide options and flexibility. If your needs change or your current carrier disappoints you, we can adapt without starting over. Plus, our broad market access often uncovers better deals than sticking with just one company.
Both types of agents can provide excellent service – the key is finding someone who listens to your needs and explains your options clearly, regardless of their business model.
Conclusion
Finding the right home insurance agent doesn’t have to feel like searching for a needle in a haystack. The difference between a good agent and a great one often shows up in the details – how they explain confusing policy terms, whether they remember your family’s changing needs, and most importantly, how they support you when disaster strikes.
The benefits we’ve covered throughout this guide all point to one simple truth: personalized service beats automated quotes every time. You might save a few minutes filling out an online form, but you’ll spend hours trying to figure out what went wrong when your claim gets denied or your coverage falls short.
A quality home insurance agent becomes part of your support network. They’re the person you call when that tree falls on your roof during an ice storm, or when you’re wondering if your teenager’s fender-bender affects your homeowners policy. They celebrate with you when you renovate your kitchen and make sure your coverage keeps up with your improvements.
Download our agent selection checklist to keep track of important questions and compare your options systematically. Having everything organized makes those initial conversations much more productive.
Here in the Finger Lakes region, we’ve seen how the right insurance relationship makes all the difference. At Mitchell-Joseph Insurance Agency, we’ve helped families through kitchen fires, storm damage, and even the occasional bizarre claim (like the time a client’s vintage car collection got damaged by a wayward hot air balloon).
Our independence means we can shop 24 different companies to find you the best deal, but our local roots mean we understand exactly what risks face homes in Honeoye Falls, Victor, Canandaigua, and throughout Monroe and Ontario counties. We’ve been doing this for over 20 years because we genuinely enjoy helping our neighbors protect what matters most.
Whether you’re buying your first home or reviewing coverage on a property you’ve owned for decades, don’t settle for generic solutions. The right home insurance agent takes time to understand your unique situation, explains everything in plain English, and stays available when you need them most.
For business owners looking to protect their commercial interests, our business insurance services provide the same personalized approach we bring to homeowners coverage.
Remember: your home represents more than just a financial investment. It’s where your family creates memories, where you feel safe, and where you build your future. Make sure the person helping you protect it treats it with the same care and attention you do.

