

Why Your Luxury Condo Needs More Than Basic Coverage
High value condo insurance is specialized coverage for luxury condominiums, typically with replacement values over $1 million. It offers superior protection that standard HO-6 policies can’t match.
Key Features of High-Value Condo Insurance:
- Higher Coverage Limits: Personal liability up to $5 million.
- Specialized Protection: Generous coverage for fine art and jewelry.
- Superior Services: Guaranteed replacement cost and flexible claims settlements.
- Unique Benefits: Deductible waivers for large claims and worldwide liability.
- Typical Premiums: $2,000-$3,000 per $1 million of coverage.
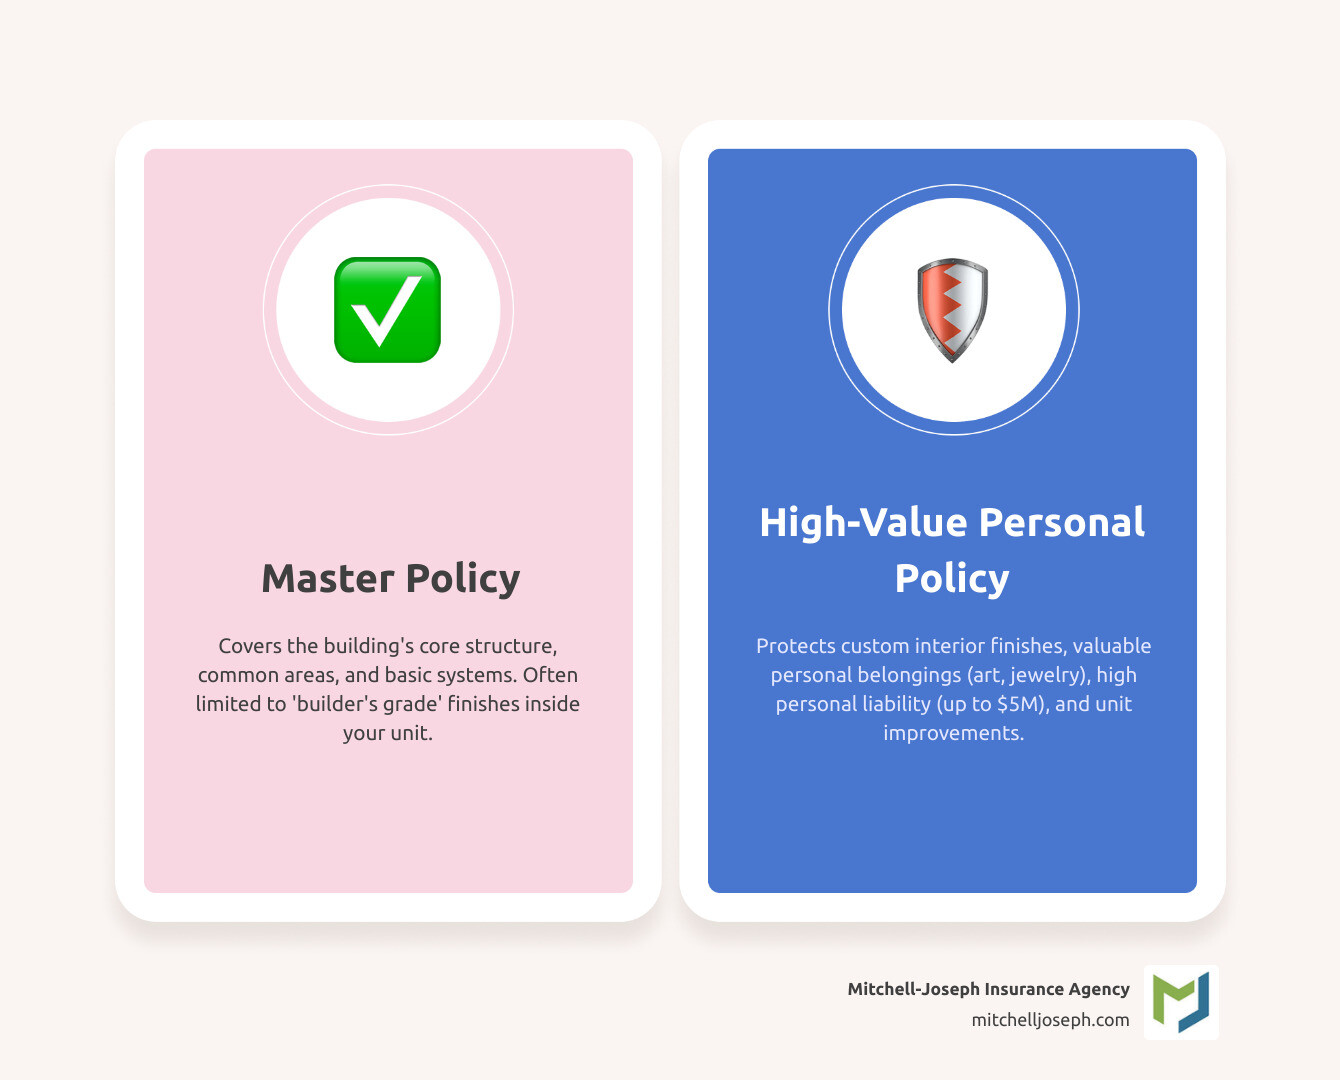
If you own a luxury condo with custom finishes, high-end renovations, or valuable collections, standard condo insurance leaves dangerous gaps. Your condo association’s master policy typically covers only “builder’s grade” materials and common areas—not your Italian marble countertops, custom millwork, or art collection. Standard policies also have low limits for valuables, often capping jewelry coverage at just $1,000.
As Jeffrey Joseph from Mitchell-Joseph Insurance Agency, I’ve helped affluent condo owners in the Finger Lakes region steer the complexities of high value condo insurance for over two decades. My experience shows that the right specialized coverage can be the difference between a minor inconvenience and a financial catastrophe.
Understanding the Difference: High-Value vs. Standard Condo Insurance
Most condo owners are familiar with a standard HO-6 policy, which covers personal belongings, unit improvements, and personal liability. While suitable for many, it’s often inadequate for luxury properties.
High value condo insurance is crafted for properties with a replacement value often exceeding $1,000,000. Unlike standard policies with limited coverage for high-end finishes or collections, a high-value policy provides broader coverage, higher limits, and specialized services designed to protect your entire lifestyle.
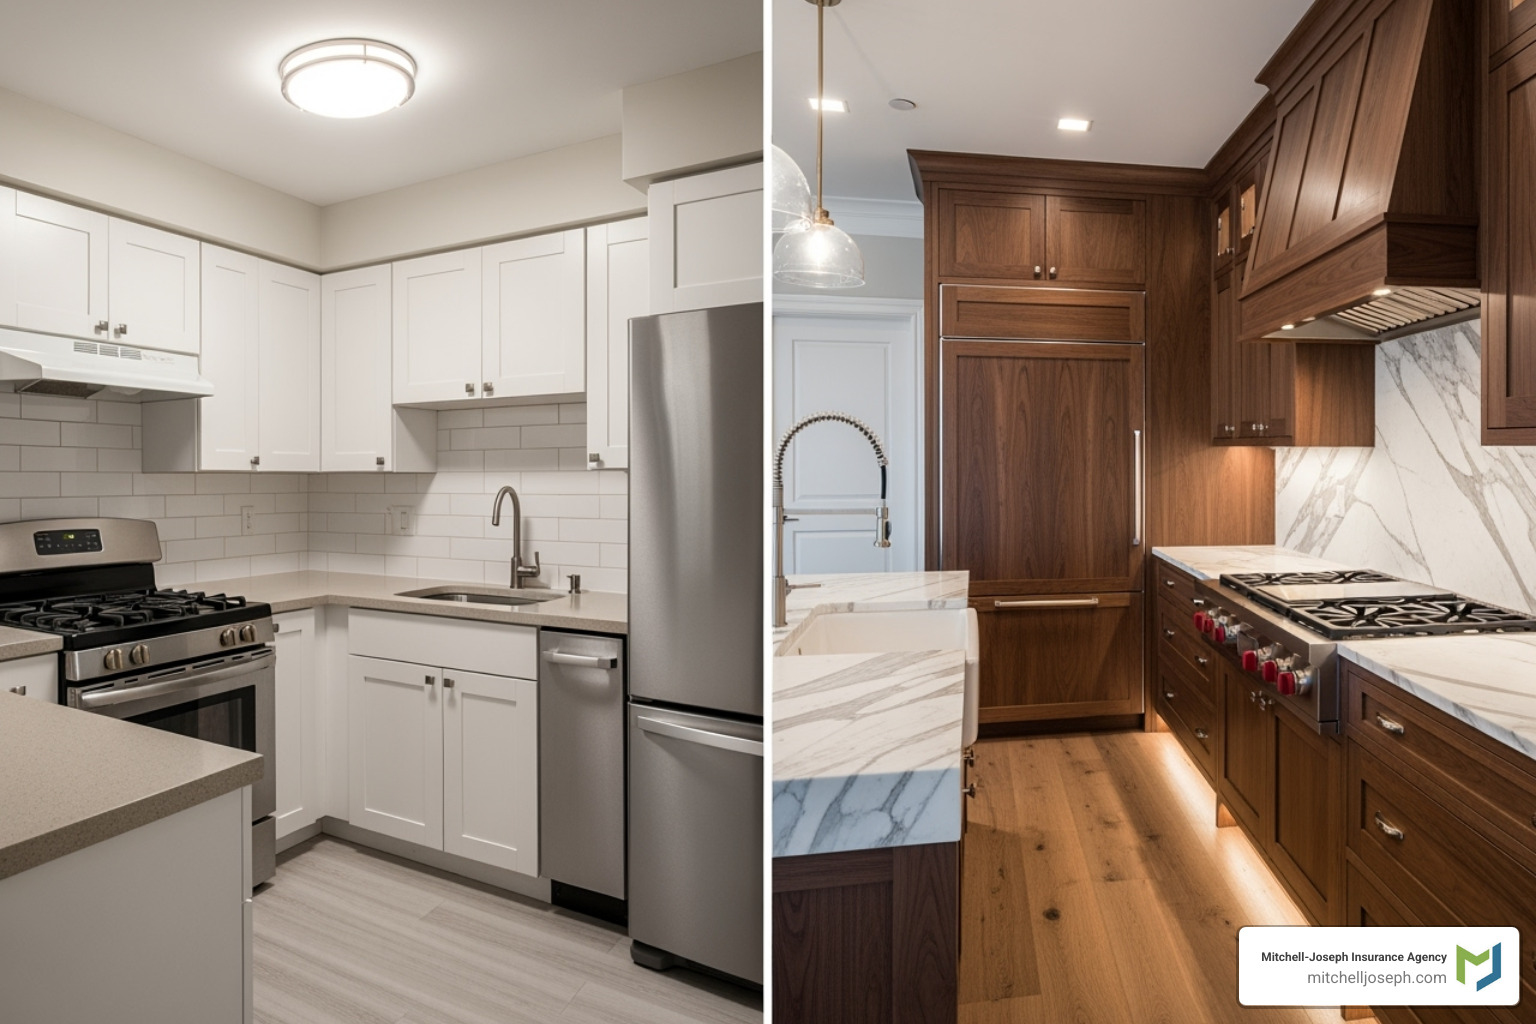
For instance, a high-value policy understands the risks and value of a custom-designed kitchen or an antique chandelier. If disaster strikes, you get the resources to restore your condo to its original, luxurious state. Many policies also offer flexible claims settlement options, including a cash settlement without the obligation to repair or replace, giving you ultimate control.
More info about home insurance coverage types
What Sets a High-Value Policy Apart?
A high value condo insurance policy is defined by its comprehensive protection and personalized service.
- Guaranteed Replacement Cost: This ensures your policy will cover the full cost to rebuild your condo to its original specifications, even if that cost exceeds your policy’s dwelling limit. This is vital for luxury condos with unique architectural details and custom features where rebuilding costs can escalate.
- Worldwide Liability Protection: This extends your liability coverage globally. If you accidentally cause bodily injury or property damage to someone, whether at home or while traveling abroad, your policy protects you.
- Flexible Claims Settlement: High-value policies often provide options like a cash settlement, giving you the flexibility to decide if, where, and how you want to rebuild or replace items.
- White-Glove Service: Providers offer proactive risk management, including complimentary in-home appraisals to document your property’s value and expert advice on improving home safety.
- Deductible Waivers: Many policies waive your deductible for major claims, often those exceeding $25,000, which can be a significant relief during a major loss.
Who Needs This Specialized Coverage?
High value condo insurance is essential for:
- Affluent individuals and high-net-worth families whose assets and lifestyle demand a higher level of protection.
- Owners of luxury penthouses and multimillion-dollar condos where unique designs and prime locations lead to higher replacement costs.
- Owners of condos with extensive custom renovations, such as imported marble, custom millwork, or integrated smart home systems that standard policies won’t fully cover.
- Collectors of fine art, jewelry, wine, or other high-value collectibles, as standard policies have very low sub-limits for these items.
- Individuals with significant personal liability exposure due to their profession, travel, or valuable assets that could attract lawsuits. High-value policies offer liability coverage up to $5 million or more.
Core and Specialized Coverages for the Affluent Condo Owner
A high value condo insurance policy is structured to protect your luxurious lifestyle with coverages that go far beyond the basics. These policies are designed to safeguard every detail of your home and life.
Core coverages include Additions & Betterments, Personal Property, Personal Liability, Loss Assessment, and Additional Living Expenses.
Essential Protections for Your High-Value Condo Insurance
- Additions & Betterments: This covers your custom upgrades at their true replacement cost. It ensures your high-end finishes, custom millwork, designer fixtures, and smart home systems can be restored to their original, exquisite state.
- Personal Property: This offers “all-risk” protection for your belongings, settled at replacement cost. This means you receive the funds to buy new items of similar quality without deduction for depreciation. You can learn more on our page about Personal Property Condo Insurance.
- Personal Liability: While standard policies offer low limits, high value condo insurance can provide liability limits up to $5 million. This protects your financial well-being if someone is injured on your property or if you accidentally cause damage to another’s property.
- Loss Assessment Coverage: If your condo association’s master policy is insufficient to cover damage to common areas, all unit owners may be assessed a share of the cost. A high-value policy includes ample loss assessment coverage to protect you from these unexpected expenses.
- Additional Living Expenses: If a covered loss makes your condo uninhabitable, this coverage helps you maintain your standard of living by covering costs for temporary housing, meals, and other necessary expenses, often with no specific dollar limit.
Exclusive Endorsements for Unique Lifestyles
High value condo insurance offers exclusive add-ons (“endorsements”) for affluent lifestyles:
- Scheduled Personal Property: Provides higher, specific limits and broader coverage for valuables like fine art, jewelry, wine collections, and rare collectibles. It can cover risks like accidental breakage or mysterious disappearance.
- Equipment Breakdown Coverage: Protects against the mechanical or electrical breakdown of essential systems and appliances, from your HVAC to your high-end kitchen appliances.
- Cyber and Identity Theft Protection: Covers expenses related to identity theft recovery and can extend to modern risks like cyberbullying or online fraud.
- Deductible Waivers for Major Claims: Your deductible may be waived entirely for a covered loss exceeding a certain amount (e.g., $25,000).
- Improved Household Protection: Offers financial support for expenses after traumatic events like home invasions or kidnappings.
- Business Property Coverage: Covers business equipment and supplies in your home office.
- Contents Extension: Extends coverage for personal property at other locations you own or rent, like a vacation home.
- Legal Expense Insurance: Provides access to a legal advice helpline and covers legal costs for issues like contract or property disputes.
The Critical Role of Your Condo Association’s Master Policy
To properly protect your condo with high value condo insurance, you must also understand your condo association’s master policy. This policy is held by the Homeowners Association (HOA) and generally covers the building’s main structure and common areas like lobbies, gyms, and pools.
Master policies vary, and knowing your building’s type is key:
- “Bare walls-in”: The most basic type, covering only the building’s structure and common areas. Everything inside your unit, from drywall to fixtures, is your responsibility to insure.
- “Single entity”: Covers the building, common areas, and original fixtures inside each unit. Any upgrades or custom renovations you’ve made are not covered.
- “All-in”: The most comprehensive type, covering the structure, common areas, and permanently installed items within your unit, including improvements. However, it may still be limited to “builder’s grade” materials and carry a large deductible.
The key takeaway is that most master policies have builder’s grade limitations, meaning they only replace damaged items with standard, basic materials. They will not cover the cost to replace your luxury finishes with items of equal quality.
Insurance for Condo Associations
Identifying and Filling the Gaps
The first step in securing the right high value condo insurance is to review your condo association’s bylaws and master policy. This clarifies what the association covers and what you are responsible for. Understanding this distinction is fundamental to condo ownership. For a general overview, resources like the Insurance Information Institute can be very helpful.
Once you understand your responsibilities, we can fill the gaps with your personal policy:
- Unit Contingency Coverage: This protects you if the master policy’s limits are exhausted or if it doesn’t cover a specific loss.
- Deductible Protection Coverage: If a loss affects your unit, you may be responsible for a portion of the master policy’s deductible. This coverage helps pay your share, which can be substantial.
- Understanding your responsibility: Your individual policy is the only thing protecting your personal property, your unique unit improvements, and your personal liability. Many owners mistakenly assume their association’s policy covers everything, leaving them financially exposed.
By identifying these gaps and tailoring your personal high value condo insurance policy, you ensure seamless protection for your investment and gain peace of mind.
Insurance for Condominium Owners
Determining the Cost of High-Value Condo Insurance and How to Save
Let’s be honest – when you’re considering high value condo insurance, the cost is probably one of your biggest questions. And rightfully so! These policies do cost more than standard homeowner’s insurance, but there’s a good reason for that. You’re getting coverage that actually matches the true value of your luxury condo and everything in it.
Think of it this way: if you’ve invested hundreds of thousands (or millions) in custom finishes, high-end appliances, and valuable collections, doesn’t it make sense to protect that investment properly? The extra premium you pay is really insurance against potentially devastating financial losses.
Factors That Influence Your Premium
Your high value condo insurance premium isn’t pulled out of thin air. Insurance companies look at several key factors to determine what you’ll pay, and understanding these can help you make smart decisions about your coverage.
The value of your unit and belongings is the biggest factor by far. If your condo’s interior and contents are worth $2 million, you’ll naturally pay more than someone with $500,000 in coverage. For luxury condos, rates typically range from $1.60 to $11.40 per $1,000 of insured value. A good rule of thumb? Expect to pay around $2,000 to $3,000 per million dollars of coverage for a low-to-medium risk property.
Where you live matters tremendously. A penthouse in a low-crime area with excellent fire protection will cost less to insure than one in a high-risk zone. Insurance companies look at everything from local crime statistics to how close you are to the fire department. If you’re in a hurricane zone or earthquake area, that’ll bump up your premium too.
Your building’s construction and age play a big role in pricing. Newer buildings with updated electrical, plumbing, and HVAC systems are seen as lower risk. If your building was constructed with fire-resistant materials or has modern safety features, you’ll likely pay less.
Claims history – both yours and your building’s – can significantly impact your rates. Insurance companies typically look back three to five years. If there have been multiple water damage claims in your building, or if you’ve filed several claims yourself, expect higher premiums.
Your deductible choice directly affects your premium. Choose a higher deductible (say, $10,000 instead of $2,500), and you could save nearly 30% on your premium. Just make sure you’re comfortable paying that amount out of pocket if something happens.
Even factors like your credit score can influence your rates in many states. Insurance companies use this information to create an “insurance score” that helps them assess risk.
Smart Strategies for Lowering Your Costs
Here’s the good news: there are plenty of ways to reduce your high value condo insurance premium without sacrificing the protection you need. Over the years, we’ve helped our clients save thousands of dollars by implementing these strategies.
Bundling your policies is probably the easiest money-saver. When you combine your condo insurance with your auto policy, umbrella coverage, or other insurance products with the same company, most carriers offer substantial discounts. We’ve seen clients save $500 or more just by bundling their condo and auto policies.
Security upgrades are another smart investment. Installing a comprehensive alarm system, security cameras, or smart home technology doesn’t just make your condo safer – it can also earn you significant discounts. Insurance companies love anything that reduces the risk of theft or damage.
Water leak detection systems are particularly valuable for condo owners. Since water damage is one of the most common and expensive claims, installing automatic shut-off valves and leak sensors can prevent major losses and qualify you for premium credits. It’s a win-win situation.
Raising your deductible is a straightforward way to lower your premium, but you need to find the right balance. There’s a point where increasing your deductible further won’t save you much more money, and we can help you find that sweet spot.
Keeping a clean claims record pays off in the long run. Try to avoid filing small claims that you could reasonably handle out of pocket. Save your insurance for the big stuff – that’s what it’s really for.
System upgrades in your condo can also lead to discounts. If you’ve recently updated your plumbing, electrical, or HVAC systems, make sure your insurance company knows about it. These improvements can earn you discounts of up to 15%.
Paying annually instead of monthly might seem like a small thing, but many insurance companies charge administrative fees for monthly payments. Pay your premium once a year, and you’ll avoid these extra costs.
If you’re in a coastal area, consider getting a wind mitigation inspection. This certified inspection can verify that your building has wind-resistant features, potentially saving you up to 31% on your premium.
The bottom line? High value condo insurance is an investment in protecting your lifestyle and financial security. While the premium might seem high compared to basic coverage, the peace of mind and comprehensive protection it provides are invaluable. And with the right strategies, you can keep those costs reasonable while still getting the coverage you need.
Frequently Asked Questions about High-Value Condo Policies
It’s normal to have questions about specialized coverage like high value condo insurance. Here are answers to some of the most common queries.
What officially qualifies a condo as “high-value”?
While there’s no single definition, a condo generally enters the “high-value” category based on several factors, primarily a replacement cost of $1 million or more. Other key indicators include:
- Extensive custom renovations and high-end finishes: Items like imported marble, custom cabinetry, and chef’s kitchens require specialized coverage.
- Unique architectural features: Custom layouts or built-ins that require expert craftsmanship to repair or replace.
- Prime location: Penthouses in major cities or exclusive waterfront properties often fall into this category due to high rebuilding costs.
- High value of personal assets: Significant collections of fine art, jewelry, or wine necessitate a policy that can properly cover them.
If your condo is a significant investment showcasing your personal style and housing valuable items, it likely needs high value condo insurance.
Do I need appraisals for my valuables like art and jewelry?
Yes, appraisals are highly recommended for your most valuable possessions. They are important for several reasons:
- Establishes Value: An appraisal provides an expert, official assessment of an item’s worth, ensuring you have the right amount of coverage.
- Smooths Claims Process: In the event of a loss, a pre-existing appraisal removes guesswork about value, leading to a faster, more accurate settlement.
- Required for Scheduled Items: To “schedule” individual items for broader coverage and higher limits, insurers typically require a recent appraisal.
- Peace of Mind: Knowing your most cherished possessions are accurately valued and properly insured provides invaluable peace of mind.
Does a high-value policy cover liability if I serve on the condo board?
This is an important question. Generally, your personal liability coverage on a high value condo insurance policy does not automatically cover your actions as a director or officer of the condo association.
The association itself should carry a separate Director & Officer (D&O) liability insurance policy to protect board members from lawsuits arising from their decisions.
However, some advanced high value condo insurance policies can offer supplementary D&O liability coverage as an add-on. It is crucial to:
- Confirm the D&O coverage your condo association has in place.
- Review your personal policy with us to see if it offers this protection or if it can be added as an endorsement.
This extra layer of protection is vital to safeguard your personal assets from lawsuits related to your board duties.
Your Condo is an Investment—Protect It Accordingly
Your luxury condominium is more than a home; it’s a significant investment, a reflection of your style, and a safe haven for your treasured possessions. Protecting it properly requires more than a typical insurance policy can offer.
This is where high value condo insurance excels. It’s a custom solution designed for luxury living, providing complete peace of mind. This specialized coverage offers:
- Comprehensive protection for custom interiors, high-end finishes, and valuable personal property.
- Robust, worldwide liability limits to shield your assets from unexpected legal challenges.
- Specialized coverages for risks like equipment breakdown and cyber threats.
- Critical protection to fill the gaps left by your condo association’s master policy.
At Mitchell-Joseph Insurance Agency, we believe your insurance should be as exceptional as your home. As an independent, family-owned agency with over 200 years of combined experience, we provide personalized service and competitive quotes from our network of 24 trusted insurance companies.
We proudly serve clients in the Finger Lakes region and beyond, including Honeoye Falls, Pittsford, Naples, Rochester, Canandaigua, Victor, and their surrounding communities. We build lasting relationships and offer expert advice to ensure your high value condo insurance is perfectly customized to protect your assets and give you peace of mind.
Your condo is a masterpiece. It deserves the best protection.
Get a personalized quote for your condominium from our experts

