

Why Rochester Homeowners Need Flood Protection
Standard homeowners insurance doesn’t cover flood damage. For flood insurance rochester ny, you need a separate policy. Here’s what Rochester residents should know:
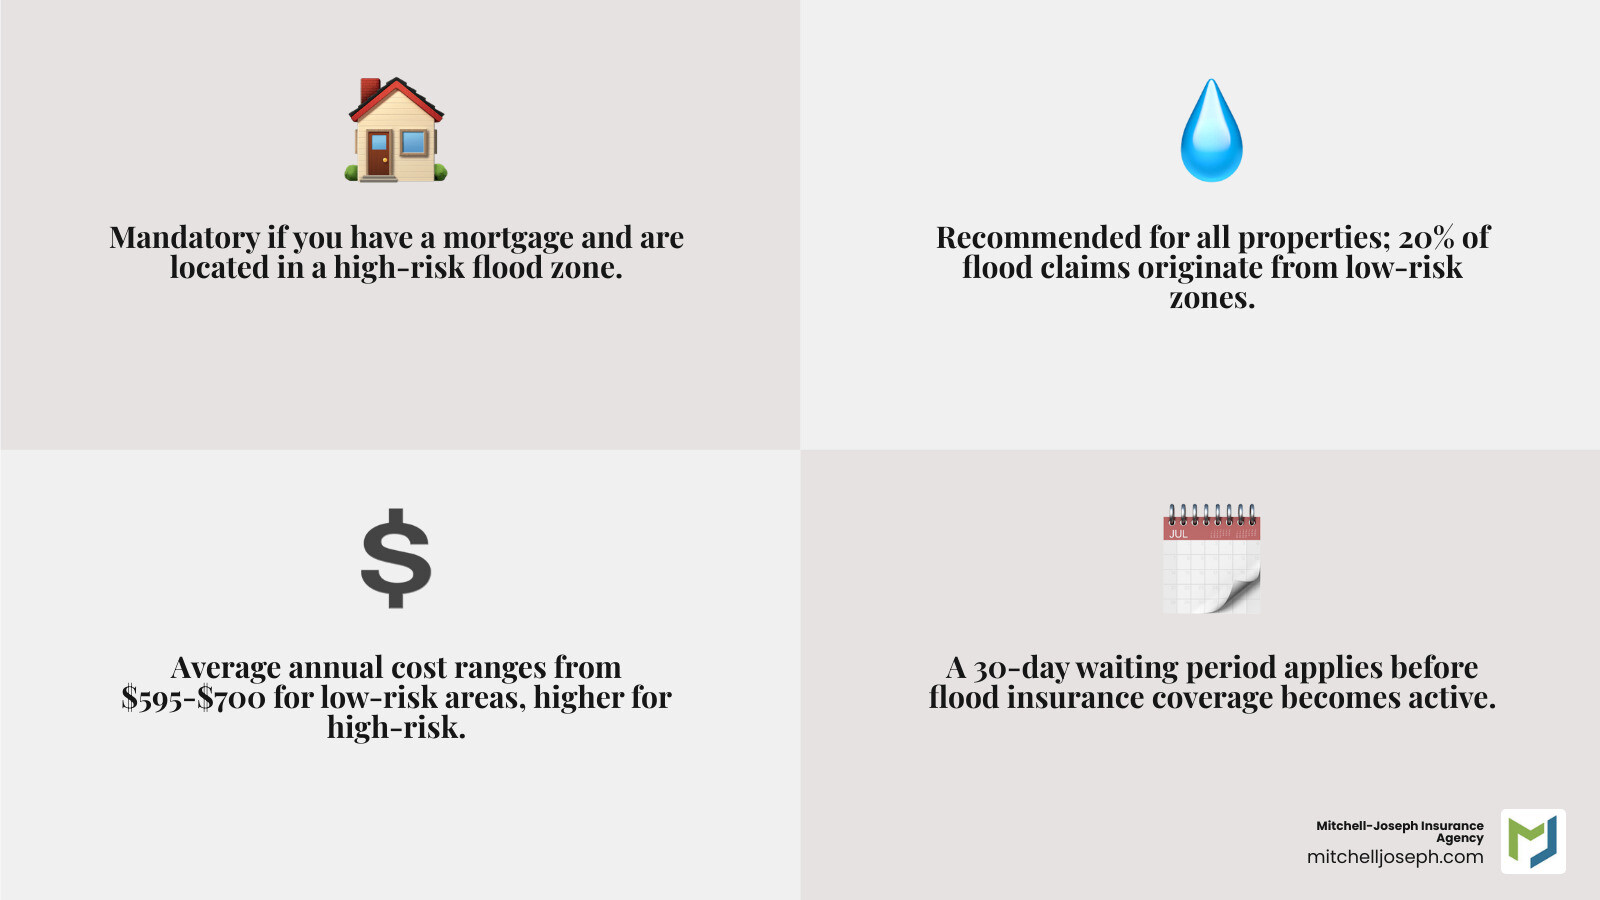
Key Flood Insurance Facts for Rochester:
- Required: If you have a mortgage and live in a high-risk flood zone
- Optional but recommended: For all other areas (20% of floods happen in low-risk zones)
- Cost: Averages $595-$700 annually for low-risk areas, more for high-risk zones
- Waiting period: 30 days before coverage begins
- Where to buy: Through insurance agents or floodsmart.gov
A flood can be devastating, especially when you find your homeowners policy won’t cover the damage. Rochester faces real flood risks from the Genesee River, Lake Ontario, and heavy snowmelt.
The financial impact is staggering. Average government disaster assistance is only about $5,000 (and it’s a loan you must repay), while the average flood damage claim exceeds $38,000. Understanding your flood insurance options is crucial for protecting your home.
I’m Jeffrey Joseph of Mitchell-Joseph Insurance Agency. Since 1999, I’ve helped Rochester-area homeowners steer their flood insurance rochester ny options. Our independent agency works with multiple carriers to find the best protection for your needs and budget.
Flood insurance rochester ny terms simplified:
Understanding Your Flood Risk in Monroe County
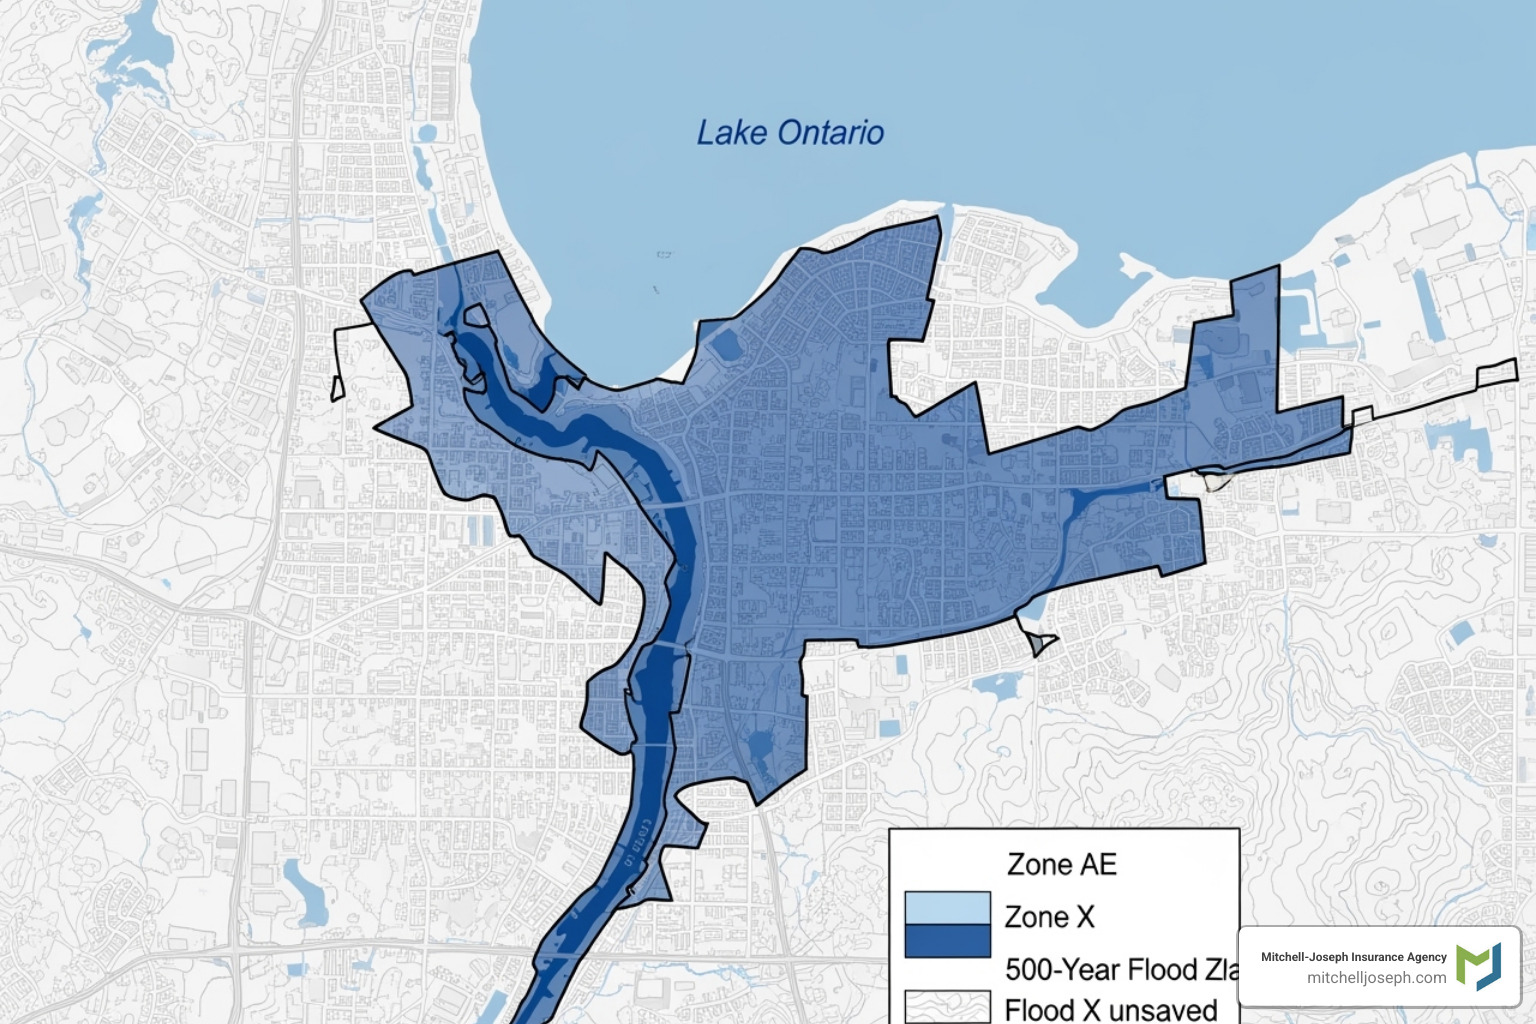
Understanding your home’s flood risk is crucial. In Monroe County, FEMA’s Flood Insurance Rate Maps (FIRMs) are the best tool to assess your property’s vulnerability. These maps divide areas into different flood zones based on risk. If you have a federally backed mortgage and live in a Special Flood Hazard Area (SFHA)—a 100-year floodplain—you’re required to have flood insurance. Properties in these zones have a 1 in 4 chance of flooding during a 30-year mortgage.
FEMA regularly updates these maps. Preliminary FIRMs for parts of Monroe County were released on September 30, 2022, meaning some properties’ risk categories may have changed.
High-risk zones like Zone AE indicate a 1% or greater annual chance of flooding. Low-to-moderate risk zones, often marked as Zone X, are outside high-risk areas but still have flood potential. Surprisingly, 20 percent of all flooding happens in areas considered low-risk. Mother Nature doesn’t always follow the maps.
To stay on top of local changes, resources like FEMA Issues Revised Flood Insurance Rate Maps for Monroe County – Town of Hamlin can help you understand what these updates mean for your property.
Why Every Rochester Homeowner Should Consider Coverage
Even if you’re not in a high-risk zone, every Rochester homeowner should consider flood insurance rochester ny. Changing weather patterns can cause flooding anywhere. Sudden downpours, rapid snowmelt, or an overflowing Genesee River can impact homes throughout our region, regardless of flood zone.
Flood insurance is proactive protection for your peace of mind. Without it, you’d pay for repairs out-of-pocket, a financial gamble most families can’t afford. A sobering statistic: 80 percent of people in low-to-moderate risk areas who flooded lacked coverage.
Government disaster assistance limitations are clear. The average assistance is a $5,000 loan you must repay, while the average flood damage cost is over $38,000. Federal disaster aid isn’t guaranteed; it requires a Presidential disaster declaration. A dedicated flood policy puts you in control of your financial recovery.
Navigating Flood Insurance Policies in Rochester, NY
Navigating flood insurance rochester ny options can feel overwhelming, but you don’t have to do it alone. As an independent agency, Mitchell-Joseph Insurance Agency accesses multiple carriers to find the right fit for your situation and budget.
The National Flood Insurance Program (NFIP) is the foundation of flood insurance in the U.S. It’s managed by FEMA and delivered through insurance companies in the Write-Your-Own (WYO) Program. FEMA sets the rules and backs the coverage, while insurers handle the policies. You can learn more at The NFIP Partnership.
The growing private flood insurance market offers alternatives to the NFIP, sometimes with better coverage or pricing. As your local independent agents, we compare both to find the best option for your Rochester home.
| Policy Type | Coverage Limits | Cost Factors | Flexibility & Features |
|---|---|---|---|
| NFIP Standard Policy | Building: Up to $250,000 Contents: Up to $100,000 |
Based on flood zone, elevation, deductible choice | Government-backed, standardized coverage, accepted by all lenders |
| NFIP Preferred Risk Policy | Same limits as standard | Lower cost for low-risk areas | Simplified application, budget-friendly for Zone X properties |
| Private Flood Insurance | Often higher limits available More flexible coverage options |
Can be competitive, especially in high-risk zones | Customizable features, potential for additional living expenses, broader basement coverage |
National Flood Insurance Program (NFIP) Options
The NFIP offers two main policy types for Rochester homeowners.
The Standard Flood Insurance Policy is available in participating communities like Rochester, Irondequoit, and Brighton. It can cover your building, contents, or both. For a claim to qualify as a “flood,” the water must cover at least two acres or affect two properties. A burst pipe is covered by homeowners insurance, not flood insurance.
For homes in low-to-moderate-risk zones (Zone X), the Preferred Risk Policy (PRP) offers the same protection at a lower cost. Since 20% of flood claims come from these “low-risk” areas, a PRP provides affordable peace of mind.
The NFIP has protected homes since 1968, providing nearly $1.3 trillion in coverage. It’s government-backed, secure, and accepted by all mortgage lenders. For more information, see our An Essential Guide to Flood Insurance FAQs.
Improved Flood Insurance Solutions Through Your Local Agency
While the NFIP is reliable, Mitchell-Joseph Insurance Agency can find additional flood insurance rochester ny solutions. We’re your advocates, finding solutions that fit your unique situation.
As an independent agency representing 24 carriers, we can shop for you. This allows us to find private flood insurance options that often have advantages over NFIP policies.
Private flood insurance can offer broader coverage options beyond NFIP limits, including higher amounts for your building and belongings, and extras like living expenses. Some private insurers also provide more comprehensive basement coverage.
Customization is another big plus. Private insurers are more flexible, tailoring policies to your specific risk profile. Private options can also be more affordable, especially for high-risk properties. We’ve seen NFIP premiums over $3,700 annually while comparable private coverage was under $2,500.
You also get our local expertise. With over 200 years of combined experience in Rochester, we understand the region’s specific challenges. Our job is to ensure you understand what you’re buying. To learn more about our approach, visit our page on Home Insurance Companies Rochester NY.
What’s Covered and What Affects Your Flood Insurance Rochester NY Cost
Purchasing flood insurance rochester ny is a smart investment. Understanding what’s covered and what it costs helps you make informed decisions. Flood insurance has two main parts: building coverage and contents coverage. Knowing the difference can prevent surprises during a claim.
For details on limits and deductibles, see our guides on Flood Insurance Coverage Limits and Flood Insurance Deductible Options.
Building vs. Contents Coverage: A Detailed Look
Building coverage protects your home’s structure, including the foundation, electrical systems, plumbing, and built-in appliances. Walls, floors, central air, and your furnace are also covered. For a primary, single-family home insured to at least 80% of its replacement cost, building coverage pays Replacement Cost Value (RCV), which is the full cost to repair or rebuild with no deduction for depreciation.
Contents coverage protects your personal belongings like furniture, clothing, and electronics. Contents are paid at Actual Cash Value (ACV)—replacement cost minus depreciation. A 10-year-old couch that costs $1,200 to replace might only get you a $400 payout.
Basement coverage has special limitations. Structural elements and essential systems (like a furnace) are typically covered, but personal belongings stored downstairs usually are not. For condo owners, contents coverage is especially important, as explained in our Personal Property Condo Insurance guide.
Key Factors That Determine Your Premium
Several factors determine your flood insurance rochester ny premium.
Flood zone designation is the biggest factor. A high-risk Zone AE costs more than a low-risk Zone X. In high-risk areas, your property’s elevation is also critical; homes above the Base Flood Elevation often get lower rates.
Your deductible amount, the coverage amount you select, and your home’s age and construction also play important roles.
Nationwide, the average premium is about $700 annually. In New York’s low-risk areas, it’s around $595 per year. For high-risk properties, an NFIP policy for $250,000 in building coverage can reach $3,721 annually. An independent agency makes a huge difference here. We often find private options for that same high-risk property for $895 to $2,497 per year—a potential savings of thousands.
Every property is unique, so we recommend a personalized quote. For more on local costs, see our Average Homeowners Insurance Rochester NY page.
How to Secure Your Policy and What to Do After a Flood
Getting flood insurance rochester ny is a proactive step. Knowing how to secure a policy and what to do after a flood can make a huge difference in your recovery.
The Simple Steps to Purchasing Flood Insurance Rochester NY
Securing flood insurance is simple with an experienced professional. At Mitchell-Joseph Insurance Agency, we’ve helped countless Rochester homeowners find the right protection.
- Contact a local independent agent like us. We understand Rochester’s unique flood risks.
- We’ll gather basic property information, explain your coverage options, and use our network of 24 insurers to get you competitive quotes.
- Our independent status allows us to compare options from NFIP and private insurers, explaining the differences in plain English so you can make an informed decision.
Crucially, there’s a 30-day waiting period before most policies take effect. This prevents last-minute purchases when a storm is approaching, so don’t wait. Limited exceptions exist, such as for new mortgages. Learn more about your policy’s start date in our guide on Flood Insurance Effective Date.
For general information, you can visit Find a provider at floodsmart.gov, but calling us is the best way to get personalized service and competitive quotes.
Filing a Claim After a Flood Event
If you need to file a flood claim, knowing the steps will make your recovery smoother.
- Contact us immediately. As soon as it’s safe, call us. We’re your advocates and will guide you through the entire claims process.
- Document everything with photos and videos. Before cleaning, use your phone to take clear pictures from multiple angles showing all damage. This is crucial for your claim.
- Separate damaged and undamaged items. This helps the adjuster assess your loss. Do not throw anything away until the adjuster has seen it or you’re told to do so.
- Create a detailed inventory of damaged items, including descriptions and approximate age and value.
- Work closely with the insurance adjuster assigned to your claim. They will assess the damage and calculate your payout based on your policy.
Our team is here to support you through the entire process, from purchase to claim.
Frequently Asked Questions about Flood Insurance
We get many questions about flood insurance from our Rochester neighbors. Here are answers to some of the most common ones.
Does my standard homeowners policy cover any type of water damage?
A common misconception is that homeowners insurance covers floods. It does not. Your standard homeowners policy specifically excludes flood damage.
Your homeowners policy does cover some water damage, like a burst pipe, a leaking water heater, or rain damage from a hole in your roof caused by a storm. The key difference is the water’s source. Flood insurance rochester ny covers water from outside your home, like an overflowing river or surface water from heavy rains.
There is also water backup insurance, which covers water backing up through drains. It’s usually an add-on to your homeowners policy. Compare them in our guide on Water Backup Insurance vs. Flood Insurance.
To understand your homeowners policy better, see our guide: Homeowners Insurance Rochester NY.
Can I get flood insurance if I’m not in a high-risk zone?
Yes, and every homeowner should consider it, regardless of their flood zone.
A surprising statistic: 20 percent of all flooding occurs in low-risk areas. Changing weather patterns mean heavy downpours can overwhelm drainage systems anywhere. In low- or moderate-risk areas (Zone X), you can get a Preferred Risk Policy. It offers the same solid coverage as a standard policy but at a much lower cost, providing affordable protection.
Remember the 30-day waiting period—it’s too late to buy coverage once a flood is imminent.
How much does flood insurance Rochester NY typically cost?
The cost of flood insurance rochester ny depends on your specific property, but here are some ballpark figures.
For properties in low-risk areas in New York, a Preferred Risk Policy averages around $595 per year—less than $50 a month for serious financial protection.
In a high-risk flood zone, an NFIP policy might cost around $3,721 annually for $250,000 of building coverage. As an independent agency, we can often find private options for the same coverage ranging from $895 to $2,500 per year, potentially saving you thousands.
Your actual cost depends on your flood zone, home elevation, deductible, and coverage amount. The only way to know for sure is to get a personalized quote. Get a quote for an accurate price—it’s fast and there’s no obligation.
Conclusion: Get Your Rochester Home the Protection It Deserves
This guide aimed to clarify flood insurance rochester ny. The key takeaway: standard homeowners insurance does not cover flood damage, and every Rochester home has some level of flood risk.
With average flood damage costing over $38,000 and government assistance being a mere $5,000 loan, the math is clear. Flood insurance rochester ny is essential financial protection.
Proactive risk management is key. The 30-day waiting period means you can’t buy coverage right before a storm, so don’t wait. The peace of mind from proper flood coverage is invaluable, and we want every Rochester family to feel secure during heavy rains.
At Mitchell-Joseph Insurance Agency, we’ve helped neighbors like you with insurance since 1999. We are your local, independent experts who understand Rochester’s unique flood risks, with over 200 years of combined experience.
The importance of local expertise can’t be overstated. We know how Lake Ontario levels, spring snowmelt, and summer storms affect our area.
As an independent agency, Mitchell-Joseph Insurance Agency shops multiple carriers for you. We work with 24 companies, comparing NFIP and private policies to find the best coverage, often saving you thousands while improving protection. We build relationships and are here for you when you have questions or need to file a claim.
Your Rochester home deserves protection that matches its value to you and your family. Don’t leave it vulnerable.

