

Why Protecting Your Business Gear is Crucial
Equipment theft insurance is specialized coverage that protects your business tools and machinery from theft at job sites, in vehicles, or in storage. This policy helps you replace stolen assets quickly, covering everything from hand tools to computers so you can get back to work with minimal disruption.
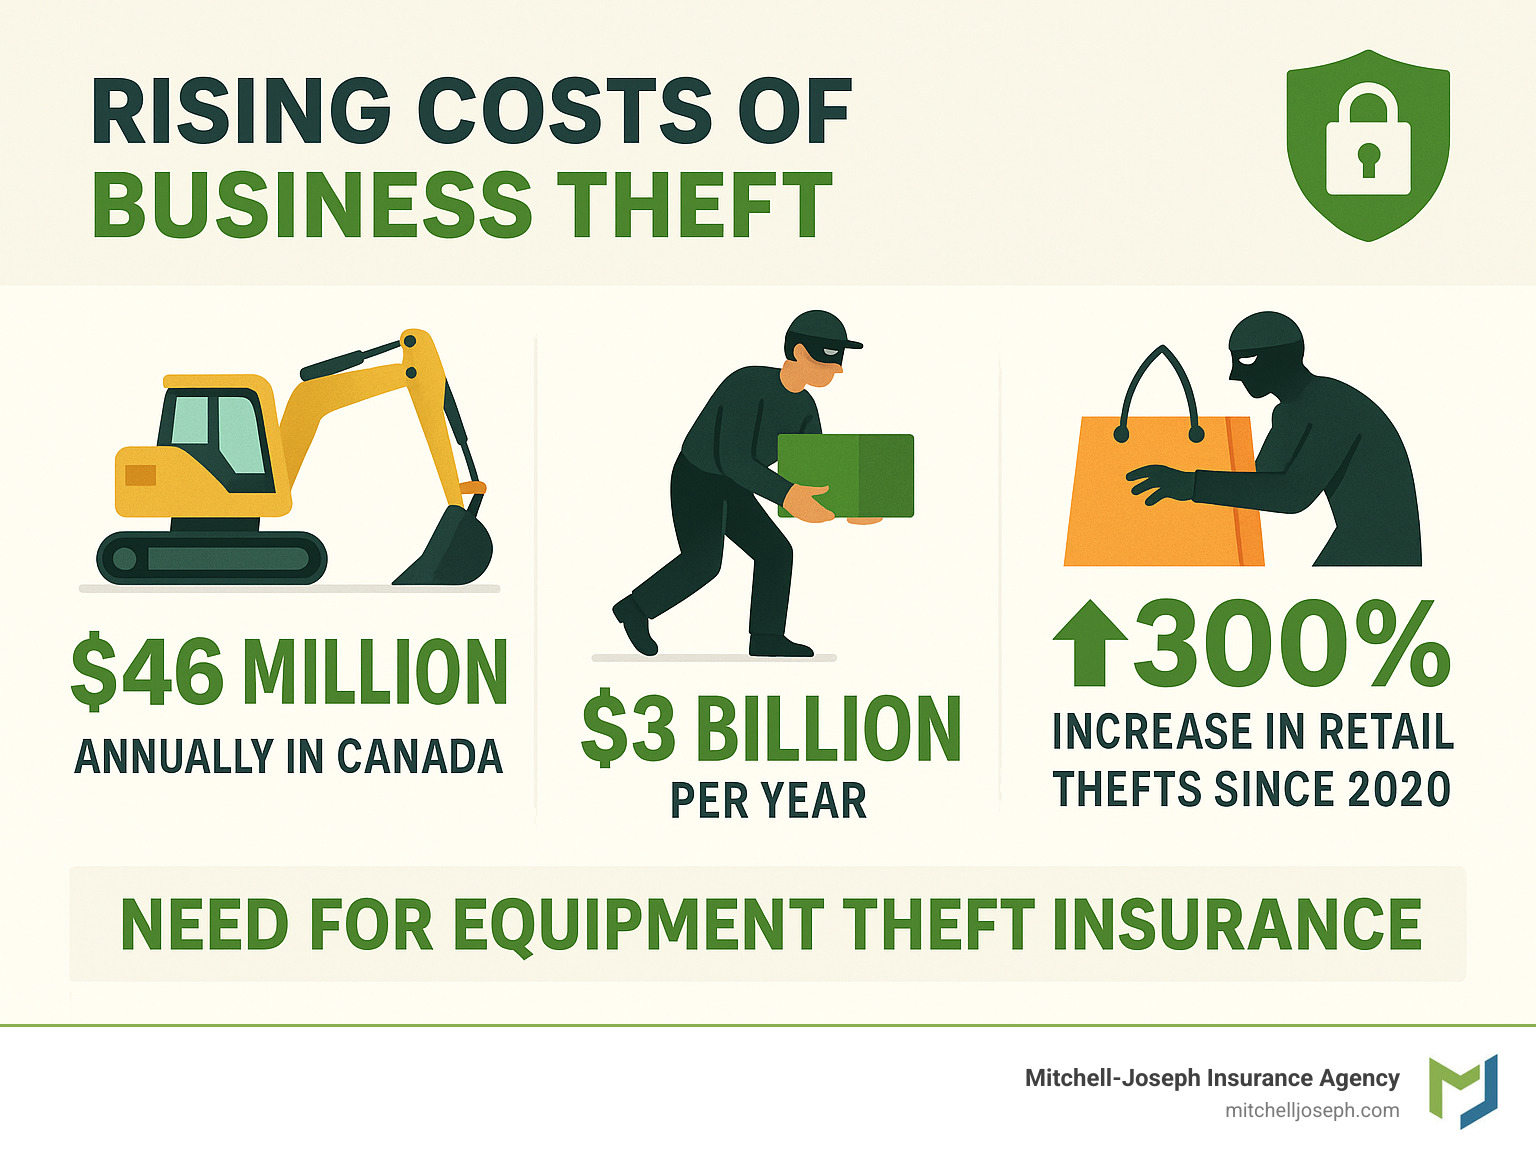
The threat to business equipment is real and, according to Statistics Canada, growing. In Canada, construction theft alone costs businesses an estimated $46 million annually, while employee theft adds another $3 billion in losses. When thieves target your gear, you face not just the loss of assets but also project delays and damaged client relationships.
As your company grows, it becomes a more attractive target. Your equipment is your livelihood, and protecting it is a top priority. Business disruption from theft can be devastating, leading to weeks of lost income and reputational damage if you can’t replace tools quickly.
I’m Jeffrey Joseph of Mitchell-Joseph Insurance Agency, and I’ve helped businesses in the Finger Lakes region protect their assets since 1999. My experience shows that the right equipment theft insurance can be the difference between a minor setback and a business-ending catastrophe.
A Deep Dive into Equipment Theft Insurance
When your business depends on tools and equipment, understanding how equipment theft insurance works can save you from devastating financial losses. You have several options to protect your assets, whether they’re stored at your shop or traveling to job sites.
What Policies Cover Stolen Equipment?
No single policy covers every theft scenario. Instead, smart business owners combine different types of coverage to create a comprehensive safety net.
Commercial property insurance is the foundation, protecting tools and equipment at your main business location or designated storage facility. However, it’s for stationary assets and won’t follow your tools when they leave the premises.
For businesses with mobile equipment, inland marine insurance is essential. This policy is designed for property that moves around, making it perfect for contractors, landscapers, and photographers. It’s often called “Tools & Equipment Insurance” and covers your gear wherever your work takes you.
A Business Owner’s Policy (BOP) bundles commercial property and general liability insurance, often at a competitive price. However, you’ll typically need to add an inland marine endorsement to cover equipment that leaves your primary location.
Commercial auto insurance covers equipment permanently attached to your business vehicles, like a custom tool rack or a vehicle-mounted generator. Tools stored inside the vehicle, however, fall under inland marine insurance.
Finally, consider employee dishonesty insurance. With employee theft costing Canadian businesses billions annually, this specialized coverage protects you from internal threats, a risk standard property policies typically exclude.
| Insurance Type | Primary Coverage Focus | Coverage for Equipment Theft | Best For |
|---|---|---|---|
| Commercial Property Insurance | Buildings, contents at a fixed location | Theft of equipment at the insured premises | Businesses with stationary equipment or equipment stored only at one site |
| Inland Marine Insurance | Property that is mobile, in transit, or off-site | Theft of equipment wherever it is located (job sites, vehicles, etc.) | Contractors, landscapers, mobile service providers, photographers, etc. |
| Business Owner’s Policy (BOP) | Bundled property, liability, business interruption | Theft at premises; often requires inland marine add-on for mobile items | Small businesses seeking broad coverage, with option to add mobile protection |
| Commercial Auto Insurance | Business vehicles and attached equipment | Theft of equipment permanently attached to a commercial vehicle | Businesses with specialized vehicle-mounted equipment |
| Employee Dishonesty Insurance | Financial losses from employee misconduct | Theft of equipment by an employee | Any business with employees handling valuable assets |
What’s Covered and What’s Not?
Understanding your policy’s specifics helps you avoid surprises. Here’s a look at typical coverage and limitations.
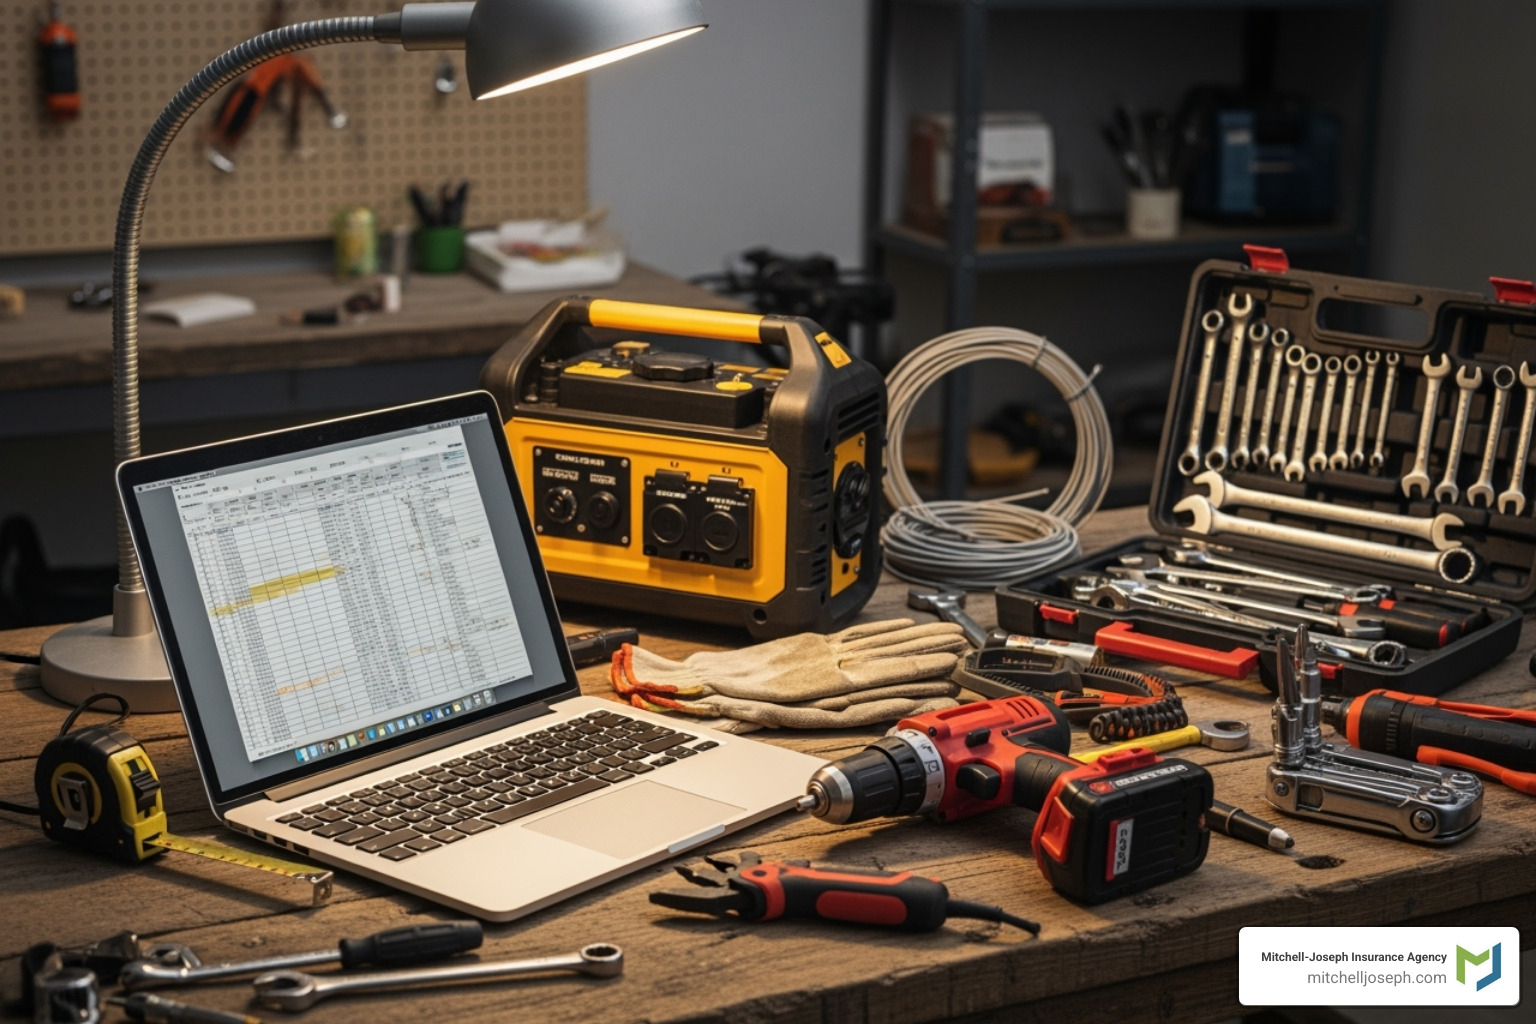
Most policies cover hand and power tools, small machinery like generators, and office equipment like laptops used off-site. Heavy machinery such as excavators requires specialized contractors’ equipment insurance, a form of inland marine coverage for high-value assets. Many policies also extend to leased or rented equipment and even employee tools used for business purposes.
A key benefit is location flexibility; your coverage follows your tools whether they’re stolen from job sites, work vehicles, or client premises.
When insuring equipment, you’ll use scheduled vs. unscheduled property coverage. Unscheduled coverage provides a blanket limit for smaller tools (e.g., under $1,000 per item) without listing them individually. For high-value items, you’ll need scheduled coverage, which means listing each piece with its make, model, and value to ensure precise protection.
However, equipment theft insurance doesn’t cover everything. Common exclusions include:
- Normal wear and tear: Equipment that wears out from regular use.
- Negligent operation: Damage from intentional misuse by workers.
- Age limits: Very old tools might only receive their actual cash value (depreciated worth).
- Mysterious disappearance: Equipment that vanishes without evidence of theft (like forced entry) may not be covered.
Factors That Influence the Cost of Your Policy
Several key factors determine your equipment theft insurance premium:
- Equipment value: The total value of your tools and machinery is a primary cost driver.
- Industry risk profile: High-risk industries like construction typically face higher premiums than office-based businesses.
- Business location: Operating in areas with higher crime rates can increase your premium.
- Claims history: A history of frequent or large claims suggests higher future risk to insurers.
- Coverage limits and deductibles: Higher deductibles lower your premium but increase your out-of-pocket cost per claim.
- Security measures: Implementing GPS tracking, secure storage, and alarms can earn you discounts.
- Valuation method: Replacement cost coverage (to buy new) costs more than actual cash value coverage (which pays a depreciated amount).
Basic coverage can start around $19 monthly, but your final cost depends on these factors. For pricing that reflects your specific situation, contact Mitchell-Joseph Insurance Agency for a personalized quote.
How to Prevent Theft and What to Do If It Happens
While insurance provides a financial safety net, prevention is your best strategy. Smart security practices protect your assets and prevent business disruptions.
- Physical Security: Use secure storage like locked sheds or trailers. Never leave keys in equipment. Ensure storage areas are well-lit.
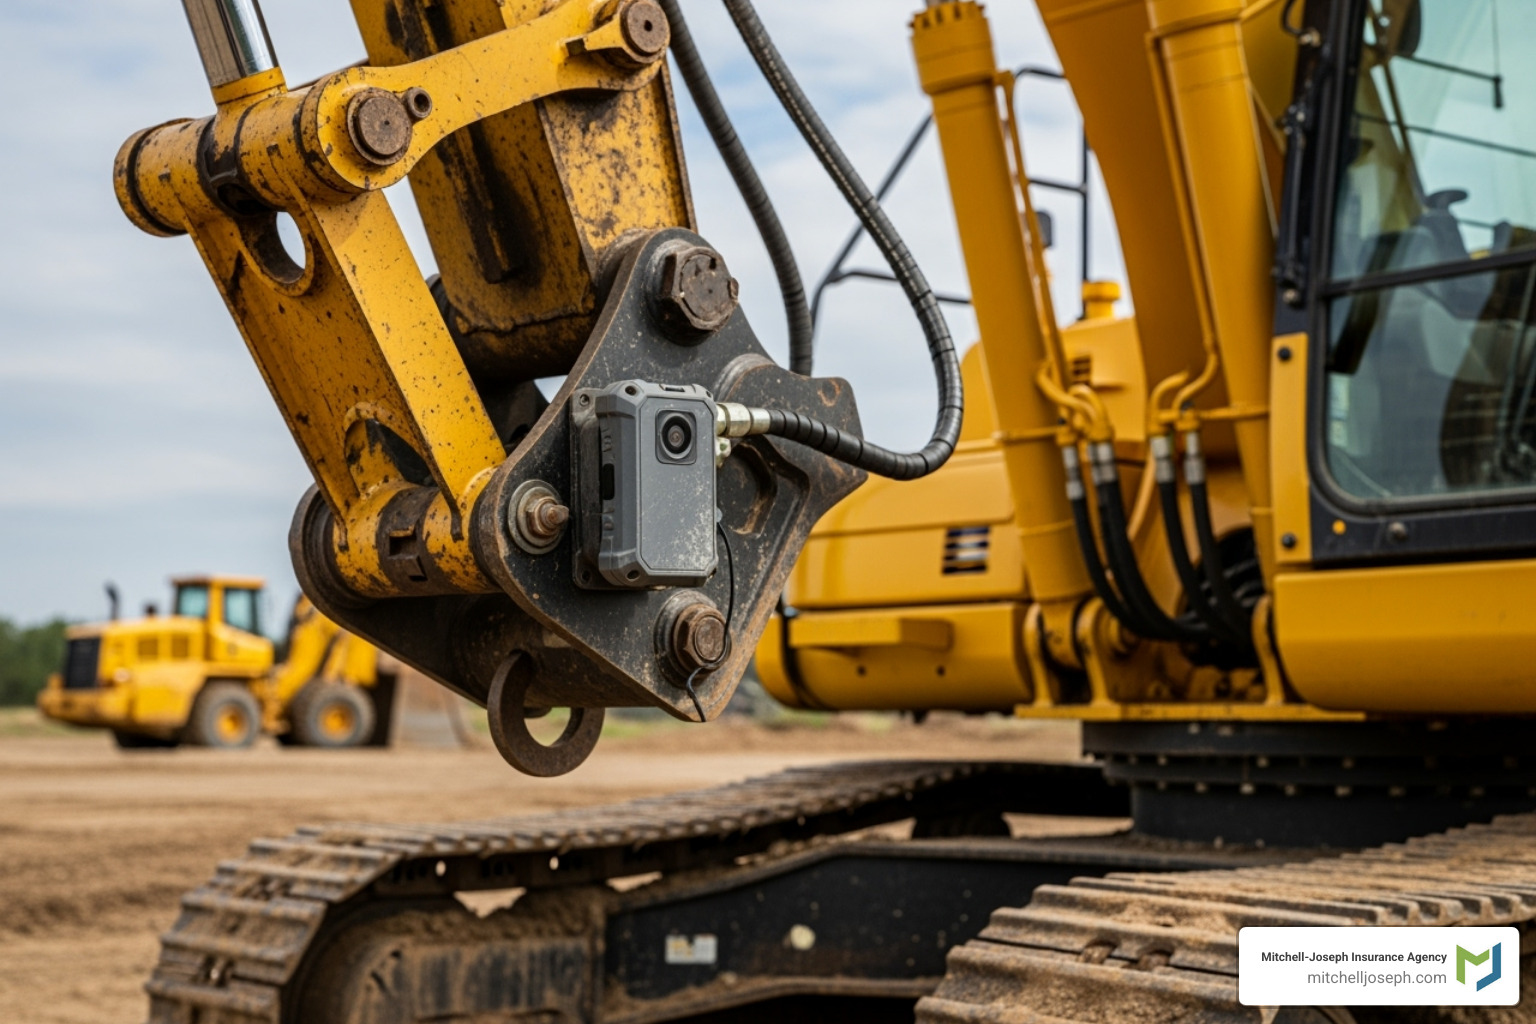
- Technology: Install visible alarms and surveillance cameras. Use GPS tracking systems for real-time location monitoring and recovery assistance.
- Internal Security: Conduct thorough background checks for new hires to help prevent employee theft.
- Record Keeping: Maintain a detailed inventory with make, model, serial numbers, purchase dates, and photos for every piece of equipment.
If a theft occurs, act quickly:
- File a police report immediately. This is essential; your insurer will require the police file number.
- Contact your insurance provider as soon as you’ve notified the police.
- Gather your documentation. Provide the police report number, receipts, serial numbers, and photos of the stolen items.
- Stay responsive to your insurance adjuster and follow their guidance to expedite the claim.
Combining smart prevention with proper insurance and a rapid response offers the strongest protection for your livelihood.
Securing Your Business’s Future
Protecting your livelihood means making smart decisions about equipment theft insurance. After helping businesses in the Finger Lakes region for over two decades, I’ve seen how the right coverage prevents a temporary setback from becoming a business-ending disaster.
When to Choose Specialized Equipment Theft Insurance
Standard commercial property insurance protects assets at your shop but often leaves you vulnerable on the road. You need specialized equipment theft insurance, typically an inland marine policy, in these key situations:
- High-Value Equipment: If your business relies on expensive machinery or high-tech devices, standard policy limits won’t be enough. These assets need to be properly valued and insured.
- Mobile Assets: For contractors, landscapers, photographers, or anyone moving tools between locations, inland marine insurance is essential. It protects your gear wherever it goes.
- Multiple Job Sites: If you work at various construction sites, client homes, or event venues, you need coverage that “floats” with your assets.
- Contractual Requirements: Many large projects or commercial clients require you to carry specific equipment protection before you can bid on a job.
- Homeowner’s Policy Gaps: Your homeowner’s policy offers little to no protection for professional tools. Technicians with thousands of dollars invested in their gear are often surprised to find they have no coverage.
Coverage differs for stolen tools versus heavy machinery. Smaller tools often fall under “unscheduled” or blanket coverage with a per-item limit. Heavy machinery like excavators requires “scheduled” coverage, where each piece is listed individually with its specific value to ensure full replacement cost protection.
Partnering with an Expert for the Right Protection
Navigating equipment theft insurance options can be overwhelming. With so many policies and exclusions, it’s easy to make costly mistakes. That’s where an experienced partner makes all the difference.
At Mitchell-Joseph Insurance Agency, we bring over 200 years of combined experience. As a family-owned, independent agency, we work with 24 different insurers to find you the best coverage at competitive rates. Our deep roots in communities like Honeoye Falls, Pittsford, and Naples give us unique insight into the risks local businesses face.
We provide:
- Custom Coverage: We identify your most vulnerable assets and build a policy that fits your industry and operations, whether you need inland marine coverage for mobile tools or specific scheduling for heavy machinery.
- Clear Explanations: We walk you through your policy without jargon, so you know exactly what’s covered.
- Personalized Service: You’re not dealing with a call center. From your initial quote to filing a claim, we’re here to guide you.
Don’t let equipment theft threaten your business. For insights into how we customize protection, see our business insurance for photographers page. Ready to protect your assets? We’re here to help you find the right solution.

