

Introduction
That sparkling diamond on your finger represents so much more than just a beautiful piece of jewelry. It symbolizes your love, commitment, and the promise of a future together. Yet surprisingly, nearly half of all engagement rings remain uninsured, leaving couples vulnerable to heartbreak beyond just the emotional kind.
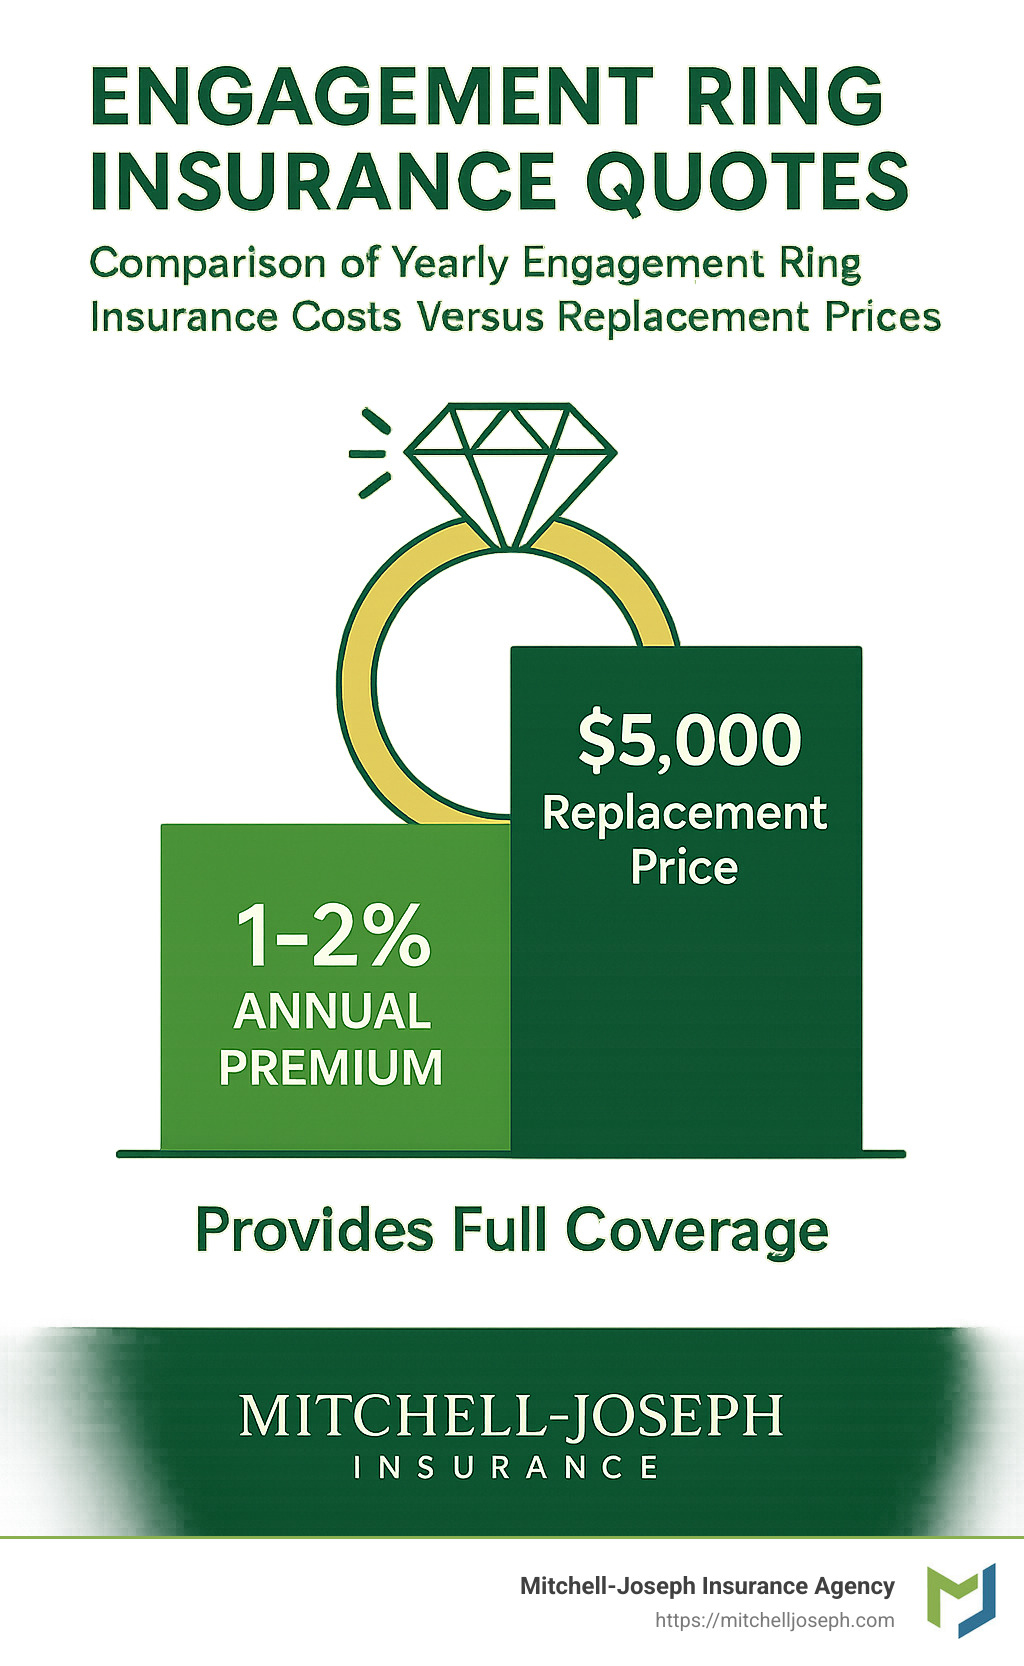
Engagement ring insurance quotes typically cost between 0.5% and 2% of your ring’s appraised value annually. This means protecting that gorgeous $5,000 ring might cost you just $50 a year with specialized coverage. Compare that to the limited protection from standard homeowners insurance, which often caps jewelry coverage at a mere $1,000-$2,000 per item – far below what you’d need to replace your precious symbol of love.
| Quick Facts: Engagement Ring Insurance Quotes |
|---|
| Annual Cost: 0.5-2% of ring’s value |
| Example: $50/year for a $5,000 ring |
| Coverage: Loss, theft, damage, mysterious disappearance |
| Homeowners Coverage Gap: Usually only $1,000-$2,000 per item |
| Where to Get Quotes: Specialized jewelry insurers, independent agents |
With the average engagement ring now valued at $5,900, that coverage gap can leave you facing a significant financial burden should something happen. And let’s face it – rings face countless hazards in daily life. That stone could loosen while gardening, slip off during a beach vacation, or disappear during travel. The financial loss compounds the emotional devastation of losing something so meaningful.
I’m Jeffrey Joseph from Mitchell-Joseph Insurance Agency, and I’ve helped hundreds of couples find peace of mind through personalized engagement ring insurance quotes. After 20 years in this industry, I’ve learned that insuring your ring isn’t just about protecting a possession – it’s about safeguarding a symbol of your love story.
Want to learn more about protecting your precious jewelry? Check out these helpful resources:
– Do people put insurance on expensive jewelry
– Mailing expensive jewelry insurance
– Travel insurance for expensive jewellery
What Is Engagement Ring Insurance & Why You Need It
When you slide that gorgeous symbol of commitment onto your finger, the last thing you want to think about is something happening to it. Yet that’s exactly why engagement ring insurance quotes matter so much. This specialized coverage protects what might be one of your most valuable possessions against the unpredictable moments in life.
Unlike your standard homeowners or renters policy (which typically caps jewelry coverage at disappointing amounts), dedicated ring insurance wraps your precious gem in a comprehensive blanket of protection. It covers not just the obvious threats like theft, but also those heart-stopping moments when you look down and realize your ring is simply… gone.
Did you know that 70% of people rank their engagement ring among their top three most expensive possessions? Even more telling, 72% said they would be “very upset” if something happened to their ring without insurance protection. Despite these numbers, nearly half of all engagement rings remain completely unprotected.
“Losing your jewelry can feel like losing a piece of yourself,” explains Maria, whose ring slipped off while swimming in Canandaigua Lake. Thankfully, her coverage through Mitchell-Joseph meant more than just financial reimbursement. “Having insurance didn’t just replace the financial value—it helped ease the emotional devastation I felt.”
Your ring insurance typically covers:
- Loss when your ring accidentally disappears while gardening or swimming
- Theft whether from your home, car, or while traveling abroad
- Damage like chipped stones or bent prongs from everyday wear
- Mysterious disappearance when you simply can’t explain how it vanished
- Worldwide coverage that travels with you on your honeymoon and beyond
- Natural disasters protecting your ring from floods, fires, and other catastrophes
What you won’t find covered are situations like intentional damage, normal wear and tear over decades, manufacturer defects (which should fall under warranty), war-related incidents, pest damage, or routine maintenance like cleaning and resizing.
The emotional value of your ring often far exceeds what’s on the appraisal. Sean from Rochester finded this after his wife’s ring was stolen. “The insurance couldn’t replace the exact ring I proposed with, but it allowed us to create a new symbol of our commitment without financial strain. That peace of mind was invaluable.”
For something that represents so much more than its monetary value, proper protection isn’t just sensible—it’s essential. Whether your ring cost $2,000 or $20,000, the peace of mind that comes with knowing you’re protected against life’s unpredictable moments is truly priceless.
More info about Insurance Coverage
Getting Accurate Engagement Ring Insurance Quotes: Step-by-Step
Getting the right coverage for your precious symbol of love doesn’t have to be complicated. Let me walk you through how to get accurate engagement ring insurance quotes with a personal touch that ensures your ring is properly protected.
1. Get a Professional Appraisal
Every good insurance policy starts with knowing exactly what you’re protecting. A current professional appraisal from a certified gemologist is your foundation for accurate coverage.
“A proper appraisal isn’t just about determining value,” explains James, our senior jewelry insurance specialist at Mitchell-Joseph. “It documents the specific characteristics of your ring—stone quality, metal composition, unique settings—that ensure you’ll receive a truly equivalent replacement if needed.”
Think of your appraisal as your ring’s identity card. Without it, insurers are just guessing at what they’re covering.
2. Gather Purchase Documentation
Your ring came with paperwork for a reason! Collect your original purchase receipt, warranty information, and any certification papers, especially for diamonds or precious gemstones. These documents help verify your ring’s authenticity and establish its true value when you’re shopping for engagement ring insurance quotes.
3. Take Clear Photographs
They say a picture is worth a thousand words—and in insurance, it might be worth thousands of dollars. Photograph your ring from multiple angles, capturing any unique details or characteristics. These images create a visual record that proves invaluable if you ever need to file a claim.
4. Research Coverage Options
Before diving into quotes, understand what you’re shopping for:
Most couples choose replacement value policies, which cover the full cost to replace your ring with one of similar quality. Actual cash value policies factor in depreciation (not ideal for jewelry), while agreed value policies set a specific payout amount upfront.
5. Request Multiple Quotes
This is where working with Mitchell-Joseph Insurance Agency really shines. We provide quotes from 24 different insurance companies, giving you a comprehensive view of your options. Comparing multiple engagement ring insurance quotes ensures you’re getting the best coverage at the best price.
6. Consider Deductible Options
Your deductible directly affects your premium. Higher deductibles mean lower premiums, but more out-of-pocket costs if something happens.
Danny G., a client from Pittsford, shared: “I was surprised by how affordable a zero-deductible policy was. I paid slightly more in premiums but loved knowing that if anything happened to my wife’s ring, we wouldn’t have to pay anything for the replacement.”
7. Ask About Discounts
Don’t leave money on the table! Many insurers offer discounts for home security systems, safe installation, bundling with other policies, claim-free history, or even Gemprint registration (a laser fingerprint of your diamond). These savings can make comprehensive coverage even more affordable.
8. Review Policy Details Carefully
The fine print matters. Before signing, carefully review coverage details, exclusions, the claims process, and whether you can choose your own jeweler for repairs or replacement. A good policy gives you flexibility when something happens.
Where to Find Engagement Ring Insurance Quotes Online
When searching for engagement ring insurance quotes, you have several reliable options:
Independent Insurance Agencies
At Mitchell-Joseph Insurance Agency, we provide access to quotes from 24 different insurance companies, allowing you to compare coverage options and find the perfect fit for your specific ring. Our agents in Honeoye Falls, Pittsford, and throughout the Rochester area will personally guide you through the process, explaining the nuances of each policy in plain English.
Specialized Jewelry Insurers
Several companies focus exclusively on jewelry insurance with instant online quotes. These specialized providers often understand the intricate details of jewelry valuation that general insurers might miss.
Homeowners or Renters Insurance Providers
Your current home or renters insurance company may offer jewelry riders. While sometimes less comprehensive than standalone policies, they can be convenient and may offer bundling discounts.
Sydney F., a client from Canandaigua, told us: “It was easy to get a quote for my engagement ring through Mitchell-Joseph, and I was surprised by how affordable the policy was. I was able to sign up and get coverage for my new ring right away so I could wear it with confidence!”
More info about How to Insure Expensive Jewelry
What Information You Need for Engagement Ring Insurance Quotes
Getting accurate engagement ring insurance quotes means having your ring’s details ready. Here’s what you’ll need:
Essential Documentation:
| Required Documents | Optional But Helpful |
|---|---|
| Professional appraisal (less than 2 years old) | Original purchase receipt |
| Clear photographs of the ring | Diamond certification (GIA, AGS, etc.) |
| Your home address and ZIP code | Home security details |
| Personal identification | Gemprint registration |
| Insurance claim history | Previous insurance information |
Appraisal Details
Your appraisal isn’t just a price tag—it’s a detailed description of what makes your ring special. A good appraisal includes the 4Cs for diamonds (cut, color, clarity, carat), metal type and purity, setting style, side stone descriptions, current replacement value, and the appraiser’s credentials. This comprehensive document ensures you’re covered for exactly what you have.
Gemstone Grading Reports
If your center stone came with a laboratory grading report from GIA, AGS, or similar organizations, include it! These reports provide independent verification of your stone’s characteristics and quality, which can be crucial for accurate valuation.
Address and ZIP Code Information
Where you live matters in insurance. Rates vary by location due to different risk factors like crime rates and natural disaster probability. Your exact address helps insurers calculate the right premium for your area.
Value Update Schedule
Jewelry values change over time. Most insurance experts recommend updating your appraisal every 2-3 years to account for changing market values and inflation.
“When I first insured my wife’s ring in 2018, gold was around $1,200 an ounce,” shares Michael from Naples. “Three years later, it had jumped to over $1,800. Without an updated appraisal, we would have been significantly underinsured if something had happened.”
More info about Insurance Coverage
Factors That Influence Your Quote (and How to Lower It)
When shopping for engagement ring insurance quotes, several factors will affect your premium. Understanding these can help you not only get a better rate but also ensure you’re properly protected.
1. Ring Value
The appraised value of your ring is the biggest factor in determining your premium. Most policies cost between 0.5% and 2% of your ring’s value annually. This means:
- A $3,000 ring might cost $15-60 per year
- An $8,000 ring might cost $40-160 per year
- A $15,000 ring might cost $75-300 per year
As Jennifer from Pittsford told us after insuring her heirloom ring, “I was surprised how affordable it was to protect something so precious to me. For less than a dollar a day, I have complete peace of mind.”
2. Your Location (ZIP Code)
Where you live significantly impacts your insurance rates. Areas with higher crime rates, denser populations, or greater risk of natural disasters typically have higher premiums. We’ve noticed our clients in Rochester often pay different rates than those in smaller communities like Honeoye Falls or Naples simply due to these different risk profiles.
3. Metal and Gemstone Type
The materials in your ring affect your premium too. Softer gemstones like emeralds or opals may cost more to insure than diamonds because they’re more prone to damage. Similarly, platinum settings might have different rates than gold due to repair costs, and unique or custom designs could affect pricing as well.
4. Claims History
Your personal insurance track record matters. If you’ve filed jewelry claims in the past, you might face higher premiums than someone with a spotless record. Insurance companies view previous claims as an indicator of future risk.
5. Deductible Amount
One of the easiest ways to lower your premium is by choosing a higher deductible. The difference can be substantial:
Sean R., a client from Victor, shared his experience: “I compared quotes with different deductibles and found that raising mine from $0 to $250 saved me almost 20% on my annual premium. Since I’m careful with my wife’s ring, this trade-off made sense for us.”
6. Security Measures
Many insurers reward you for taking steps to protect your ring. Installing a home security system could save you up to 15% on your premium. A home safe might knock off another 5-10%, and keeping your ring in a bank safety deposit box when not worn can lead to additional discounts.
7. Multi-Policy Discounts
If you’re already insuring your home, car, or other valuables, ask about bundling your engagement ring coverage with these policies. This approach often leads to savings of 5-15%, depending on the insurer. At Mitchell-Joseph Insurance Agency, we can compare options across our 24 partner companies to find the best combination for your needs.
8. Gemstone Documentation
Having your diamond or gemstone registered with identification services like Gemprint can sometimes qualify you for additional discounts. This laser “fingerprint” of your stone not only helps with recovery if stolen but may also reduce your premium.
9. Payment Schedule
Don’t overlook how you pay your premium. Many insurers offer discounts—sometimes up to 5%—for paying annually rather than monthly. This small change could save you a meaningful amount over time.
“When I first got my ring insured, I was looking for every possible discount,” says Maria from Canandaigua. “Switching to annual payments and installing a home security system cut my premium by nearly 25%. That’s money back in our wedding fund!”
Latest research on homeowners limits
Stand-Alone Jewelry Policy vs. Home/Renters Rider
When shopping for engagement ring insurance quotes, you’ll need to make a choice between two main options: a specialized standalone jewelry policy or adding a rider to your existing home insurance. This decision can significantly impact your coverage and peace of mind.
Standalone Jewelry Policies
Think of standalone jewelry insurance as a VIP pass for your ring. These policies are crafted specifically with precious jewelry in mind and typically offer much more comprehensive protection.
“I never realized how limited my homeowners policy was until I lost my ring at the beach,” shares Amanda from Pittsford. “My standalone policy replaced it completely with no hassle—best decision I ever made besides saying ‘yes’ to my husband!”
These specialized policies typically include:
Higher coverage limits that match your ring’s full appraised value, without the strict caps found in home policies. Your $10,000 ring gets $10,000 of coverage—simple as that.
Broader protection that covers those head-scratching “mysterious disappearance” situations. You know, when your ring simply vanishes and you have no idea how or where it happened.
Lower or zero deductibles are common with these policies. Many of our clients at Mitchell-Joseph choose the $0 deductible option for complete peace of mind.
Specialized claims handling means working with adjusters who understand the difference between an emerald-cut and cushion-cut diamond, not just general home items.
Choice of jeweler gives you the freedom to work with your trusted local jeweler rather than being forced to use the insurance company’s preferred vendor.
Preventative maintenance coverage is a hidden gem in many standalone policies. Some will even pay for prong retipping or stone tightening before problems occur.
No impact on home insurance means your home premium won’t increase after a jewelry claim—a benefit many don’t consider until it’s too late.
Inflation protection offers up to 150% of the appraised value in some policies, protecting you against rising precious metal and gemstone prices.
Home/Renters Insurance Riders (Personal Articles Floaters)
Adding coverage to your existing home or renters policy through a rider (sometimes called a “floater” or “endorsement”) is another option, but comes with important limitations.
These riders typically offer:
Convenience of having everything under one policy and one payment, which appeals to many homeowners.
Potential bundling discounts of 5-10% on your overall insurance costs, though the savings may be offset by other factors.
Limited coverage is the biggest drawback. Standard home policies typically cap jewelry at $1,000-$2,000 per item without specific additional coverage.
Higher deductibles usually match your home policy’s deductible, which might be $500, $1,000 or even higher.
Rate increase risk is significant—a jewelry claim could raise your entire home insurance premium for years to come.
Limited choice of jewelers might force you to use insurance-approved repair shops rather than your preferred local jeweler.
Less specialized handling means working with adjusters who handle everything from roof damage to stolen TVs, not jewelry experts.
Mark from Honeoye Falls learned this lesson the hard way: “After my wife’s ring was damaged, our homeowners policy applied our $1,000 deductible. Between that and the rate increase that followed, we would have saved money with a standalone policy. Live and learn!”
Cost Comparison
While everyone’s situation is different, here’s a general comparison to consider when reviewing your engagement ring insurance quotes:
| Coverage Type | Typical Annual Cost | Deductible | Impact on Other Insurance |
|---|---|---|---|
| Standalone Policy | 1-2% of value | $0-$500 (your choice) | None |
| Home Insurance Rider | 0.5-1.5% of value | Same as home policy ($500-$2,500) | Claims may increase home premiums |
At Mitchell-Joseph Insurance Agency, we typically recommend standalone policies for rings valued over $3,000. The slightly higher premium is usually offset by better coverage, lower deductibles, and protection from home insurance rate increases.
More info about Expensive Jewelry Insurance
Benefits of Stand-Alone Coverage for Frequent Travelers
If you love to travel (or even just occasionally vacation), standalone engagement ring insurance offers some serious advantages worth considering when comparing engagement ring insurance quotes.
Worldwide Coverage Without Restrictions
True worldwide coverage means your ring is protected whether you’re snorkeling in the Bahamas or skiing in the Alps. There are no geographical limitations or travel duration restrictions to worry about.
“During our honeymoon in Italy, my wife accidentally banged her ring against a stone wall in Tuscany, damaging one of the prongs,” shares Michael from Rochester. “Our standalone policy covered the repair at a local jeweler in Florence, and we didn’t miss a beat on our trip.”
No Travel Notification Requirements
With standalone policies, you don’t need to call your agent before jetting off to paradise. Your ring is automatically covered anywhere you go, without additional paperwork or travel notifications.
Coverage for Common Travel Scenarios
Travel creates unique ring risks that standalone policies handle beautifully:
– That sinking feeling when your ring slips off in ocean waters
– The panic of finding theft from your hotel room
– Damage during trip activities like hiking or snorkeling
– Accidentally leaving your ring at an airport security checkpoint
– The mysterious disappearance while sightseeing in a new city
Choice of International Jewelers
If your ring needs repair while traveling abroad, many standalone policies let you visit local jewelers rather than ruining your trip by rushing home. This flexibility is invaluable for frequent travelers.
No Impact on Home Insurance Premiums
If something happens while traveling, your claim won’t trigger increases in your homeowners insurance—a significant long-term financial benefit that many people overlook.
Simplified Claims Process for Travelers
Specialized jewelry insurers understand travelers’ needs and offer streamlined claims processes that work from anywhere:
– Digital claim filing from your smartphone
– Easy electronic documentation submission
– International claims assistance when you need it most
– Handling of currency conversion without headaches
Jennifer from Canandaigua told us: “When my engagement ring was stolen from our rental in Mexico, I was able to file the entire claim from my phone. The insurance company deposited the money before we even returned home, and we visited our original jeweler to create a replacement ring. It was as stress-free as something like that could possibly be.”
At Mitchell-Joseph Insurance Agency, we’ve helped countless clients from throughout the Rochester area select travel-friendly ring insurance that provides genuine peace of mind during their trips near and far.
More info about Travel Insurance for Expensive Jewellery
Common Mistakes to Avoid When Requesting Engagement Ring Insurance Quotes
We’ve seen it all at Mitchell-Joseph Insurance Agency – the joy of helping clients protect their precious rings, and unfortunately, the heartbreak when things go wrong. When searching for engagement ring insurance quotes, avoiding these seven common mistakes can save you significant money and emotional distress.
1. Postponing Insurance Until “Later”
That beautiful ring is at risk from the moment it leaves the jeweler’s showcase. Many couples tell themselves they’ll get insurance “soon” but life gets busy with wedding planning, and suddenly weeks or months have passed.
I remember a heartbroken couple from Canandaigua who visited our office after losing a $7,500 engagement ring just two weeks after the proposal during a weekend at the lake. They had planned to insure it “after the wedding” but now faced the entire replacement cost out-of-pocket.
Don’t wait – insure your ring immediately after purchase, even before proposing if possible. Some jewelers offer 30-day temporary coverage, but this limited protection isn’t enough for long-term peace of mind.
2. Confusing Warranties with Insurance
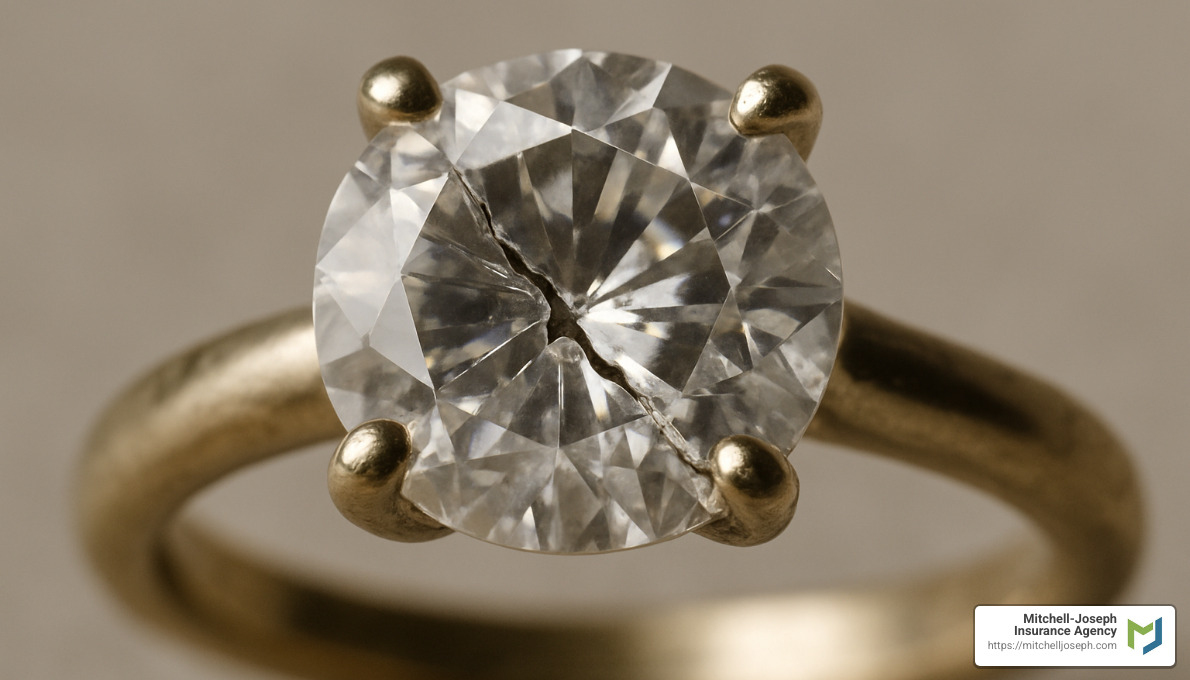
“But my ring came with a warranty!” I hear this often, but warranties typically only cover manufacturing defects and sometimes routine maintenance—not loss, theft, or that heart-stopping moment when you realize your diamond has chipped.
Think of warranties and insurance as complementary protections that serve different purposes. Your warranty might cover a loose prong, but only insurance will help if your ring disappears during a beach vacation.
3. Using Outdated Appraisals
Jewelry values aren’t static. Gold prices have seen dramatic shifts in recent years, and diamond values continue to climb. An appraisal from three years ago likely undervalues your ring significantly today.
Many of our Rochester clients are surprised to find their rings have appreciated 20-30% when they obtain updated appraisals. Without current documentation, you risk being underinsured and unable to fully replace your ring if disaster strikes.
Make a calendar reminder to update your appraisal every 2-3 years to ensure adequate coverage. Your future self will thank you!
4. Choosing Deductibles Without Analysis
“I’ll take the highest deductible to save on premiums,” sounds financially savvy until you’re facing a claim. For many couples, that $1,000 deductible feels very different when you’re already upset about a lost or damaged ring.
Take time to honestly assess your financial situation. Could you comfortably pay your deductible in an emergency? For valuable engagement rings, zero-deductible policies often make more sense despite slightly higher premiums. That small premium difference can feel like a bargain when you’re filing a claim.
5. Ignoring Available Discounts
Insurance companies love responsible owners! Many offer significant discounts that customers simply never ask about. Do you have a home security system? Store your ring in a safe when not wearing it? Have multiple policies with the same company?
When getting engagement ring insurance quotes, always inquire about discounts for security systems, safe installation, bank vault storage, multi-policy bundling, and even gemstone identification registration. These discounts can add up to meaningful savings over time.
6. Forgetting Annual Coverage Reviews
Life changes, and so should your insurance. Moving to a new neighborhood, getting married, renovating your home – these events can all impact your coverage needs and available discounts.
I recommend scheduling an annual insurance review with your agent (we offer these at no charge to our clients) to ensure your coverage still aligns with your current life situation. It’s a quick conversation that often identifies new savings opportunities.
7. Automatically Adding to Homeowners Policy
Adding your ring to your homeowners policy seems convenient, but this approach often provides less comprehensive coverage than a standalone jewelry policy. Plus, if you file a claim for your ring, it could potentially increase your home insurance rates for years to come.
Take the time to compare standalone jewelry insurance with homeowners riders. The small price difference often buys significantly better protection and greater peace of mind, especially for rings valued over $3,000.
At Mitchell-Joseph Insurance Agency, we’ve helped countless couples throughout Honeoye Falls, Canandaigua, Rochester, and beyond find the perfect balance of coverage and value. Our experience with these common pitfalls helps ensure you don’t face avoidable heartache when seeking engagement ring insurance quotes.
Frequently Asked Questions about Engagement Ring Insurance Quotes
How much does engagement ring insurance typically cost per year?
When you’re shopping for engagement ring insurance quotes, you’ll find that most policies cost between 0.5% and 2% of your ring’s appraised value each year. This means your beautiful symbol of commitment might cost less to insure than your monthly coffee budget!
For a clearer picture of what to expect:
- A $5,000 ring typically costs $25-$100 per year
- A $10,000 ring usually runs $50-$200 per year
- A $20,000 ring generally costs $100-$400 per year
Your actual rate will depend on several personal factors. Where you live matters—insurance companies look at your ZIP code to assess theft risk. The deductible you choose significantly impacts your premium (higher deductible = lower premium). Your home’s security features can earn you discounts, and your previous claims history plays a role too. Even your ring’s specific details—like having a fragile gemstone or complex setting—can influence your rate.
Danny G., one of our clients from Victor, recently shared his experience: “The process and application were very easy. For my wife’s $8,000 ring, we pay just $99 annually with a $0 deductible. That’s peace of mind for less than $10 a month.”
Can I choose my own jeweler for repairs or replacement?
This is one of the most important questions to ask when comparing engagement ring insurance quotes! Most standalone jewelry insurance policies allow you to choose your preferred jeweler for repairs or replacement—a huge advantage over typical homeowners insurance riders.
When reviewing policy options, look specifically for phrases like “choice of jeweler,” “return to your jeweler,” or confirm there are no restricted network requirements. This flexibility becomes especially valuable if you have a custom or designer ring, an antique or vintage piece, or if you purchased your ring from a local jeweler you trust.
Michael from Naples shared a story that highlights why this matters: “When my wife’s diamond came loose, we were able to return to the original jeweler in Canandaigua who designed her custom ring. They understood the piece better than anyone else could have, and our insurance covered the repair completely.”
At Mitchell-Joseph Insurance Agency, we prioritize finding policies that offer this flexibility because we understand the importance of working with trusted local jewelers throughout the Rochester area. Your ring isn’t just any possession—it deserves care from someone you trust.
How often should I update my appraisal to keep my quote accurate?
Insurance experts recommend updating your ring appraisal every 2-3 years to ensure your coverage accurately reflects current replacement costs. This might seem frequent, but precious metal and gemstone markets can be surprisingly volatile!
You might need an updated appraisal even sooner if you notice significant increases in gold, platinum, or diamond prices, if you’ve had your ring upgraded or modified, if there are market changes affecting vintage or designer pieces, or if you’ve inherited jewelry with outdated documentation.
Jennifer from Pittsford had quite the surprise after postponing her appraisal update: “I was shocked when I updated my appraisal after five years. My $6,500 ring had appreciated to $9,200 due to rising diamond and platinum prices. Without that update, I would have been significantly underinsured.”
Some insurers offer automatic value adjustments to account for inflation, but these typically don’t capture the full market changes for fine jewelry. When reviewing engagement ring insurance quotes, be sure to ask about automatic inflation protection percentages, appraisal update requirements, coverage limits for appreciated value, and whether there are discounts for appraisal services.
At Mitchell-Joseph Insurance Agency, we can recommend skilled local jewelers throughout Honeoye Falls, Canandaigua, and Rochester who provide thorough, insurance-quality appraisals. These professionals help ensure your coverage remains adequate so you’re never caught underinsured if something happens to your precious ring.
Conclusion
Securing the right insurance for your engagement ring doesn’t need to be complicated or expensive. By understanding what influences engagement ring insurance quotes and following the steps we’ve outlined, you can obtain comprehensive coverage that provides genuine peace of mind for just pennies on the dollar compared to your ring’s value.
Your engagement ring represents one of life’s most meaningful moments—a symbol of commitment that deserves proper protection. Throughout my years helping couples in the Rochester area, I’ve seen how the right insurance policy provides not just financial security, but emotional reassurance as well.
The most important things to remember about protecting your ring include acting quickly after purchase, as many losses happen during those first exciting weeks of engagement. Compare your options thoroughly, as standalone policies typically offer advantages that homeowners riders simply can’t match. Make updating your appraisal a regular part of your financial routine—every 2-3 years ensures your coverage keeps pace with changing market values.
“Having my ring insured gave me a freedom I didn’t expect,” shares Amanda from Pittsford. “I wear it confidently while gardening, swimming, and traveling, knowing that if something happens, we’re covered. That peace of mind is worth every penny of our premium.”
Documentation is another crucial element—maintain detailed records including photographs from multiple angles and professional appraisals. This small effort upfront can make an enormous difference if you ever need to file a claim. And don’t forget to review your coverage annually as your life circumstances change.
At Mitchell-Joseph Insurance Agency, we believe insurance should be personal. Your engagement ring has its own unique story, and your coverage should reflect that. With our team’s 200+ years of combined experience and relationships with 24 different insurance companies, we can find options perfectly custom to your specific needs and budget.
Our local presence throughout Honeoye Falls, Pittsford, Naples, Canandaigua, Rochester, and surrounding communities means we understand the specific concerns of New York residents. We’re your neighbors, committed to protecting what matters most to you with the same care we’d give our own family heirlooms.
Don’t leave your precious symbol of love unprotected. Contact Mitchell-Joseph Insurance Agency today for personalized engagement ring insurance quotes that provide the comprehensive coverage your ring deserves—allowing you to wear your ring with confidence while creating a lifetime of memories together.

