

Why Landlord Insurance is Essential for Protecting Your Rental Property Investment
Cheap rental house insurance—more accurately called landlord insurance—is designed to protect your rental property investment without draining your budget. Unlike a standard homeowners policy, landlord insurance covers the unique risks of rental properties, such as tenant-caused damage, loss of rental income, and liability claims from tenant injuries.
Quick Answer: How to Get Affordable Landlord Insurance
- Compare quotes from multiple providers using identical coverage limits
- Bundle policies (combine with auto or umbrella insurance for discounts)
- Increase your deductible to lower monthly premiums
- Ask about discounts for security systems, claims-free history, or multiple properties
- Maintain your property to reduce risk and keep rates low
- Require tenant renters insurance to protect against liability claims
Many landlords overpay for insurance because they don’t shop around. Costs can vary by hundreds of dollars annually for the same coverage. While a typical policy for a single-family rental might cost $1,500 to $2,500 per year, you have more control over this price than you think.
The key difference is simple: homeowners insurance is for a home you live in, while landlord insurance is for a property you rent to others. A standard homeowners policy will not cover tenant-related risks.
| Coverage Type | Homeowners Insurance | Landlord Insurance |
|---|---|---|
| Who it’s for | Owner-occupied homes | Rental properties |
| Dwelling protection | ✓ | ✓ |
| Personal property | Owner’s belongings | Optional (owner’s items only) |
| Tenant belongings | ✗ | ✗ (tenant needs renters insurance) |
| Loss of rent | ✗ | ✓ |
| Liability for tenant injuries | Limited | Improved coverage |
| Typical cost | Lower | Higher (reflects rental risks) |
I’m Jeffrey Joseph, and I’ve been helping property owners across the Finger Lakes region find affordable cheap rental house insurance solutions since 1999. At Mitchell-Joseph Insurance Agency, we specialize in connecting landlords with comprehensive coverage that protects their investment without unnecessary premium costs.
Your Guide to Finding Cheap Rental House Insurance
Finding cheap rental house insurance is about smart planning, not cutting corners. The goal is to compare quotes effectively, customize your policy, and manage risks to find the best value for your investment.
If you are new to landlord insurance or want a neutral overview of how property insurance works in general, you can also review the Home insurance article for additional background before tailoring coverage to your specific rentals.
Understanding Your Core Landlord Coverages
Landlord policies include key coverages that differ from standard homeowners insurance.
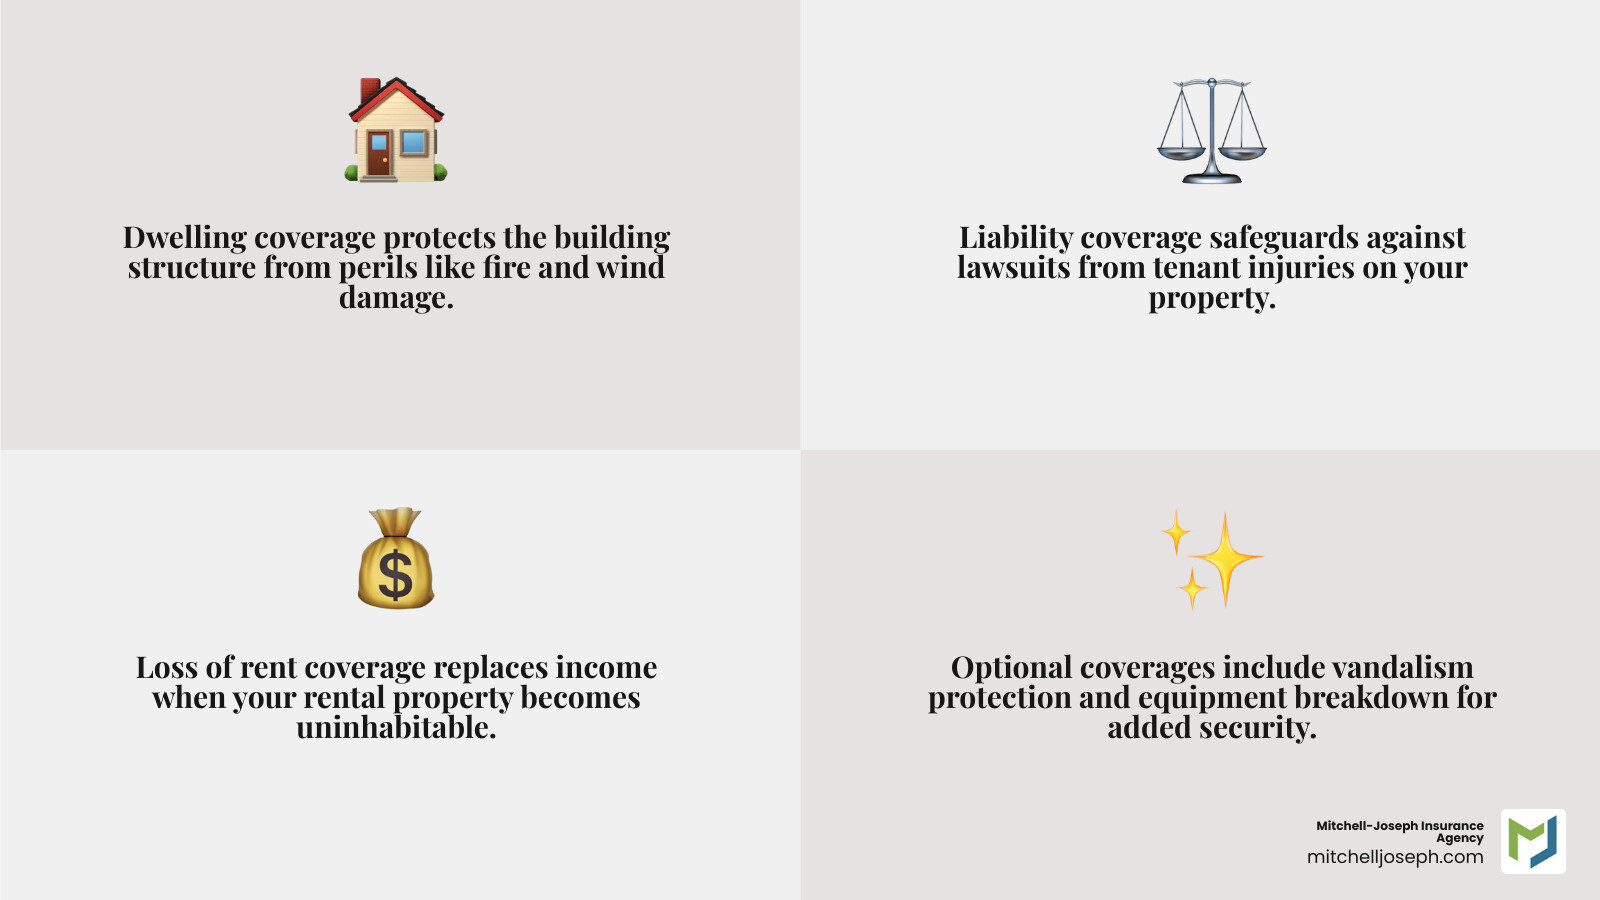
- Dwelling Protection: This is the foundation of your policy, covering the physical structure of your rental property (house, garage, fences) against perils like fire, wind, and hail.
- Liability Coverage: This protects you from financial loss if a tenant or guest is injured on your property and you are found responsible. It helps cover legal fees, medical bills, and settlements. We often recommend higher limits to fully safeguard your assets.
- Loss of Rent (Fair Rental Value) Coverage: If your property becomes uninhabitable due to a covered loss like a fire, this coverage reimburses you for the lost rental income while it’s being repaired, helping maintain your cash flow.
- Medical Payments Coverage: This covers minor medical expenses for guests injured on your property, regardless of who is at fault, which can help prevent small incidents from becoming large lawsuits.
Policies can be named peril (covering only specific, listed events) or open peril (covering all events unless specifically excluded). Open peril offers broader protection but usually costs more. We can help you understand the specifics of your policy. For more details, explore our resources on Insurance Coverage.
Optional coverages to consider include:
- Vandalism Protection: Provides broader coverage, especially for vacant units.
- Landlord’s Personal Property: Covers items you own on the rental premises, like appliances or maintenance equipment.
- Building Code Coverage: Helps pay for required upgrades to meet current building codes after a covered loss.
- Equipment Breakdown: Covers repairs for essential systems like HVAC or water heaters due to mechanical failure.
What Determines the Cost of Cheap Rental House Insurance?
The cost of your insurance is influenced by several factors. Understanding them can help you find ways to lower your premium.
- Property Location: Rates are affected by local risks. Properties in areas with higher rates of crime, severe weather, or older infrastructure (e.g., in Rochester, Honeoye Falls, or Pittsford) may have higher premiums.
- Property Age and Construction: Older homes can be more expensive to insure. Fire-resistant materials like brick may result in lower rates than wood-frame construction.
- Claims History: A history of frequent claims signals higher risk to insurers and can lead to increased premiums.
- Dog Breed Restrictions: Some insurers consider certain dog breeds “high-risk” and may charge more for liability coverage or decline to offer it if your tenant owns one. It’s crucial to know your insurer’s policy on tenant pets.
Other common risk factors include:
- Proximity to fire hydrants and fire stations
- Local crime rates
- Condition of the property (roof, plumbing, electrical)
- Presence of “attractive nuisances” like pools or trampolines
- Heating sources, such as wood-burning stoves
- Number of units in the building
For more on how property traits affect costs, see our Average Home Insurance Cost Guide.
- Security Features: Installing burglar alarms, smoke detectors, sprinkler systems, and deadbolt locks can often earn you significant discounts.
Smart Strategies for Finding Cheap Rental House Insurance
Being strategic is key to finding affordable, high-quality coverage.
- Comparing Quotes: This is the most effective way to save. Rates vary widely, so get quotes from several companies. Ensure you’re comparing identical coverage limits and deductibles for a true apples-to-apples comparison.
- Bundling Policies: Insurers offer large discounts for bundling your landlord policy with other insurance, like your auto or primary home policy.
- Increasing Deductibles: A higher deductible (the amount you pay out-of-pocket on a claim) will lower your premium. Choose a deductible you can comfortably afford.
- Available Discounts: Always ask about discounts. Common ones include being claims-free, having safety features, bundling policies, paying annually, or being a long-term customer. Find more savings tips in our Homeowners Insurance Discounts guide.
- Maintaining the Property: A well-maintained property is less risky. Regular upkeep on the roof, wiring, and plumbing can prevent claims and may lead to better rates.
- Claims-Free History: Think twice before filing small claims. It may be more cost-effective to pay for minor damages yourself to avoid a potential premium increase.
Navigating Special Risks and Requirements
Different rental properties have different insurance needs.
- Single-Family vs. Multi-Family Policies: A single-family home is typically covered by a standard landlord policy. A multi-family property like a duplex may require a commercial policy, which offers broader coverage for business-related risks.
- Condo Landlord Insurance: If you rent out a condo, the association’s policy covers the building exterior and common areas. You need a specific Condo Insurance for Landlords policy to cover your unit’s interior (“walls-in”), your belongings, and your liability.
- Natural Disaster Coverage: Standard policies almost always exclude floods and earthquakes.
- Flood Insurance: If your property is in a flood zone, especially near water in the Finger Lakes region, this is a wise and often required investment.
- Wildfire Risk: While less common in New York, it’s important to confirm your fire coverage is adequate for your area.
- Requiring Tenants to Have Renters Insurance: We strongly recommend this. Landlord insurance does not cover your tenant’s belongings. Requiring renters insurance in your lease protects your tenants and can also reduce your own liability exposure, as their policy may cover accidental damage they cause to your property.
For additional consumer-focused guidance on landlord and renters insurance rights and regulations, you can also review resources from the California Department of Insurance alongside our local expertise.
Making the Final Decision
Choosing the right cheap rental house insurance is about balancing affordability with reliable coverage and service. It’s a critical decision for protecting your financial security as a landlord.
How to Choose a Reliable, Affordable Provider
A great provider offers more than just a low price. Here is what to look for:
- Third-Party Ratings: Check an insurer’s financial health and customer service track record through ratings from firms like AM Best (financial strength) and J.D. Power (customer satisfaction). You can also refer to the National Association of Insurance Commissioners for additional consumer tools and complaint data.
- Customer Satisfaction Reviews: Real-world customer feedback on claims processing and communication can reveal how a company truly performs when you need them most.
- Financial Strength: An insurer must have the financial resources to pay claims. High ratings from agencies like AM Best indicate greater stability.
- Coverage Options vs. Cost: The cheapest policy isn’t best if it leaves you underinsured. We help you compare what’s covered against the cost to find the true value, ensuring you get the protection you need without paying for what you don’t.
For more on tailoring landlord policies to your specific rentals and budget, see our overview of personalized coverage.
Partner with an Expert for the Best Rates and Coverage
Navigating landlord insurance can be complex. Partnering with an independent insurance agent like Mitchell-Joseph Insurance Agency is the simplest way to find comprehensive protection and cheap rental house insurance rates.
- Independent Agent Benefits: Unlike agents who work for a single company, we shop the market for you. We have access to competitive quotes from 24 different insurance companies to find the best fit.
- Personalized Service: We take the time to understand your unique property and goals. Whether you own one rental in Avon or several across the Finger Lakes, we tailor your policy to your needs.
- Expert Guidance: With over 200 years of combined experience, our team can explain complex policies, advise on proper coverage limits, and help you avoid common pitfalls.
- Mitchell-Joseph Insurance Agency: As a family-owned business in Honeoye Falls, NY, we are deeply rooted in the communities we serve, including Pittsford, Naples, Rushville, and Rochester. Our local expertise means we understand the specific risks in our region. We also offer Business Insurance for Landlords with larger portfolios.
- Securing Your Investment: Our mission is to secure your rental property with affordable insurance that doesn’t compromise on quality. By leveraging our expertise and market access, we ensure you get the right coverage, so you can focus on being a successful landlord.

