

The Hidden Expense Lurking Beneath Your Property
Does home insurance cover main sewer line damage? The short answer is: it depends on the cause of the damage and your specific policy.
Quick Coverage Overview:
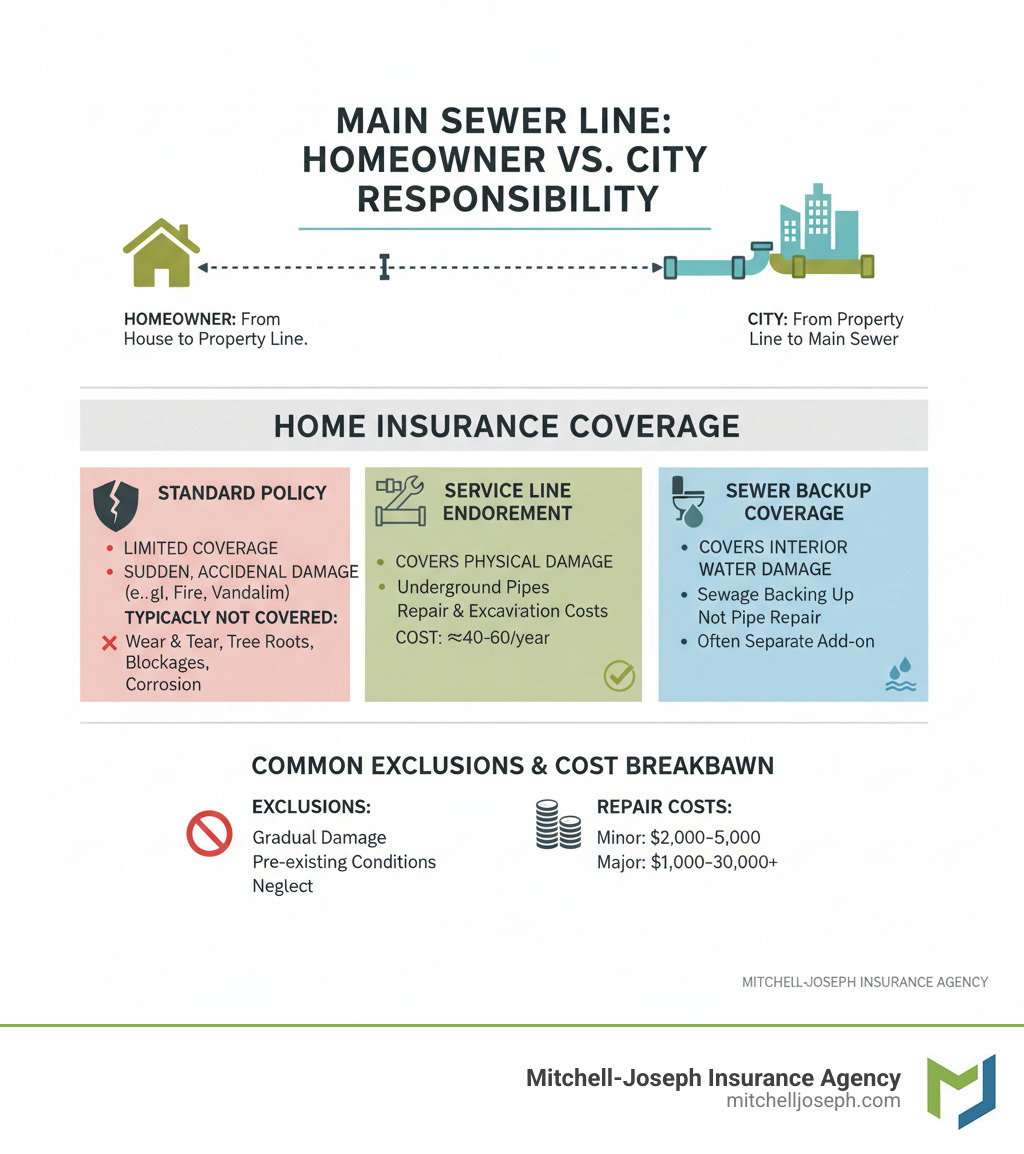
- Standard homeowners insurance: Limited coverage for sudden, accidental damage from covered perils (fire, vandalism, falling objects).
- Typically NOT covered: Wear and tear, tree root intrusion, corrosion, blockages, or gradual deterioration.
- Service line endorsement: Covers physical damage to underground pipes and repair costs.
- Sewer backup coverage: Covers interior water damage from sewage backing up into your home.
- Average cost for endorsements: $40-$60 per year.
Many homeowners are caught off guard by this hidden expense. In fact, a recent survey from Nationwide found that almost one in three homeowners incorrectly believes their standard policy covers service lines. The reality is more complex. While your policy might cover damage from a sudden event like a falling tree, it won’t help with gradual problems like tree roots cracking old pipes or corrosion causing a collapse. These slow-developing issues are the most common cause of sewer line failure, often leaving homeowners with a repair bill from thousands to tens of thousands of dollars.
I’m Jeffrey Joseph, and at Mitchell-Joseph Insurance Agency, I’ve helped homeowners in the Finger Lakes region steer these complex issues since 1999. Too often, clients find their policy’s limitations only after a disaster, facing a massive bill their standard coverage won’t touch.
Does home insurance cover main sewer line terms to remember:
Does Home Insurance Cover Main Sewer Line? A Detailed Breakdown
Here’s where things get tricky. Does home insurance cover main sewer line damage? The honest answer is: sometimes, but probably not when you need it most.
I’ve had countless conversations with homeowners who find this the hard way. They call me after finding sewage in their basement, expecting their insurance to handle everything. That’s when I have to explain that standard homeowners insurance has some pretty specific rules about what it will and won’t cover.
Standard policies focus on what insurance companies call “sudden and accidental damage” from specific covered events. If it’s been slowly deteriorating for years, you’re probably on your own.
Standard Policy Limitations: When Does Home Insurance Cover Main Sewer Line Damage?
A standard homeowners policy may cover your sewer line if it’s damaged by a “covered peril”—a specific, sudden, and accidental event listed in your policy. For example, damage from a fire, vandalism, or a tree falling on the line would likely be covered under your policy’s “other structures” coverage.
However, most sewer line problems aren’t sudden. They develop gradually from wear and tear, corrosion, or poor maintenance, which are almost always excluded. Damage from flooding, earthquakes, tree roots slowly invading pipes, or simple old age is also typically not covered by a standard policy. Understanding these limitations is crucial. For a broader look at what your policy does and doesn’t cover, check out our guide on Home Insurance Coverage Types.
Common Causes of Damage and Typical Exclusions
In the Rochester area and throughout the Finger Lakes, we see several common issues that standard policies exclude:
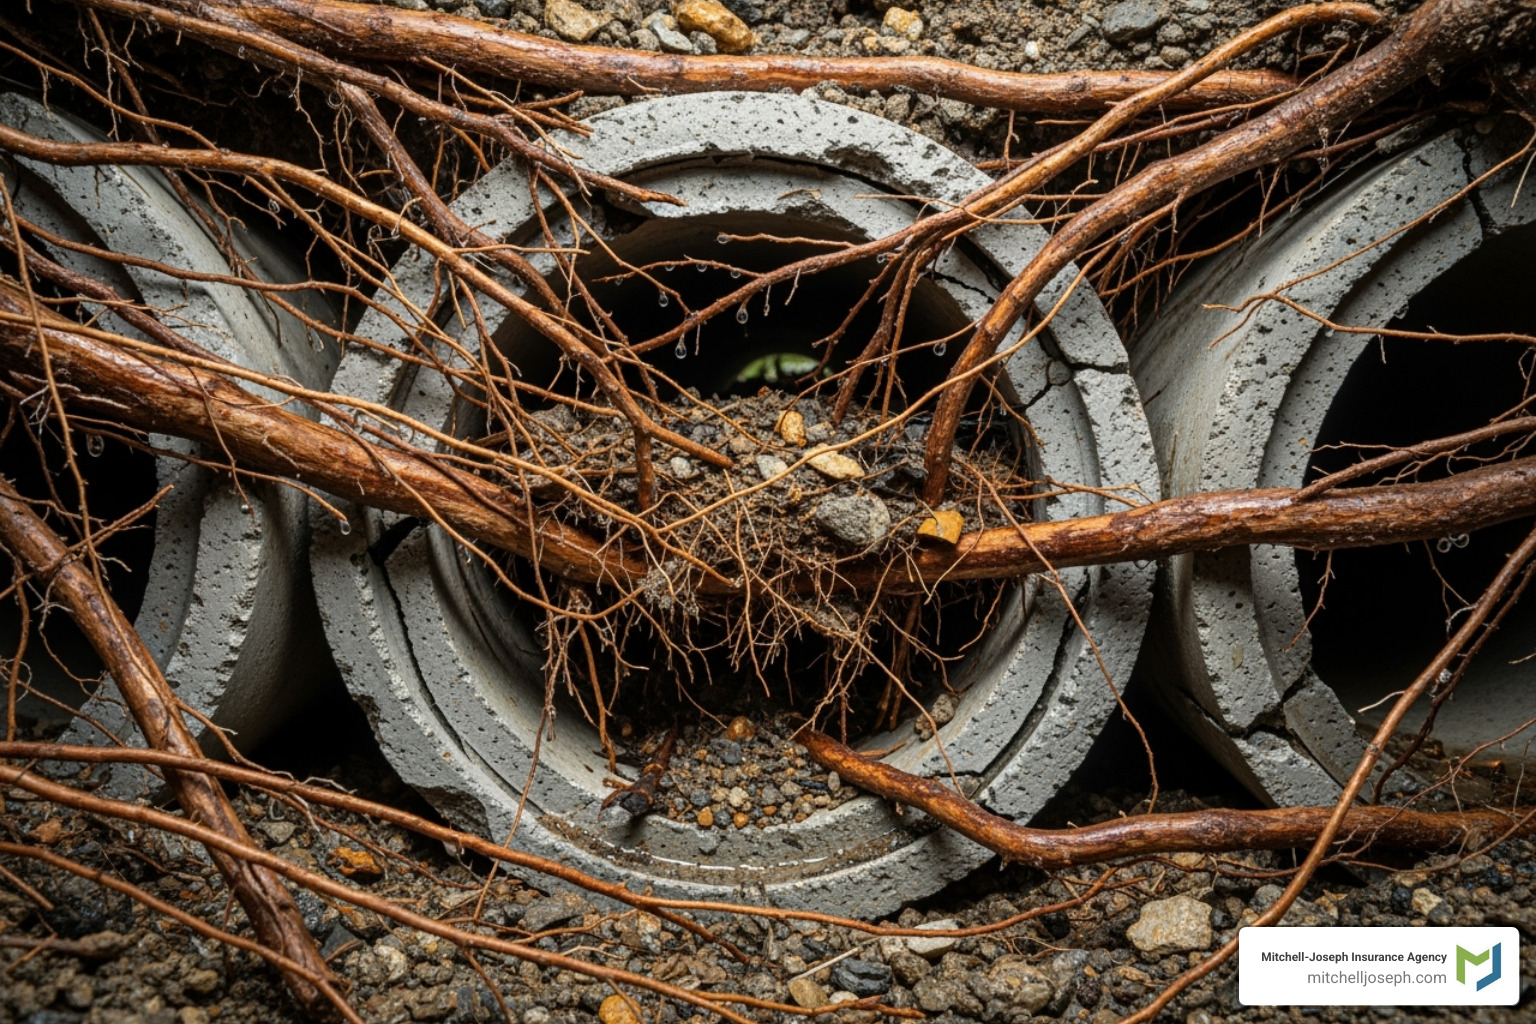
- Tree Root Intrusion: Roots from mature trees seek water, invading and crushing pipes over time. This is considered gradual damage.
- Aging Pipes: Older homes in our communities often have clay, cast iron, or Orangeburg pipes that naturally corrode and crack with age—a clear exclusion for wear and tear.
- Ground Shifting: Soil erosion or natural settling can crack or disconnect pipes. Unless caused by a covered peril, it’s not covered.
- Blockages: Buildup from grease, hair, or “flushable” wipes is considered a maintenance issue, not an insurable event.
- Faulty Construction: Problems from poor installation or materials used when the home was built are typically excluded.
These problems develop slowly, which is why a standard policy won’t cover the repair bills.
The Solution: Understanding Service Line and Sewer Backup Coverage
The good news is that specific endorsements can fill these coverage gaps. For complete protection, you need to understand two key options: service line coverage and sewer backup coverage.
-
Service Line Coverage: This endorsement pays for the physical repair or replacement of your underground utility lines, including the sewer line. Crucially, it covers damage from causes that standard policies exclude, like tree root intrusion, wear and tear, and corrosion. According to the Insurance Information Institute, this also covers excavation and landscape restoration. Coverage typically ranges from $10,000 to $12,000. For more details, visit our page on Sewer Line Insurance Coverage.
-
Sewer Backup Coverage: This protects your home’s interior. If your sewer line fails and sewage backs up into your basement, this coverage helps pay for cleanup, repairs, and replacing damaged belongings. It does not cover fixing the broken pipe itself—that’s what service line coverage is for. Learn more on our page about What Does Water Sewer Backup Insurance Cover?.
For complete protection, we recommend both endorsements. They work together to shield you from both the cost of pipe repairs and the expense of interior water damage.
Your Proactive Guide to Sewer Line Protection
Now that you understand the coverage gaps in standard policies, it’s time to take action. The best defense combines smart prevention with proper coverage. This two-part strategy helps you keep problems from happening and protects you financially when they do.
How to Prevent Costly Sewer Line Damage
An ounce of prevention is worth a pound of cure for your sewer line. Most problems are preventable with these simple steps:
- Dispose of grease properly: Never pour grease down the drain. Let it solidify in a container and throw it in the trash.
- Only flush toilet paper: “Flushable” wipes, paper towels, and other products don’t break down and cause major blockages.
- Get regular inspections: For older homes or properties with mature trees, a professional video inspection every few years can catch problems early.
- Manage tree roots: Have a professional clear roots from your pipes periodically and plant new trees away from the sewer line.
- Consider proactive replacement: If you have old clay or cast iron pipes, replacing them with modern PVC can prevent a future emergency.
- Install a backwater valve: This device prevents sewage from flowing back into your home during backups.
Filing a Claim and Getting the Right Coverage
If a problem occurs, knowing the right steps is key.
- Document everything: Take photos and videos of the damage and keep receipts for emergency repairs.
- Contact us immediately: Call us as soon as you find the problem. We’ll guide you through the next steps and help determine your coverage.
- Prevent further damage: Take reasonable steps to mitigate the damage, like shutting off the water or hiring an emergency plumber for temporary fixes.
Before a crisis, the most important step is to review your current policy. We can help you understand your declaration’s page—the summary of your coverage, limits, and endorsements. As your Home Insurance Agent, we can ensure you have the right protection before you need it.
Does Home Insurance Cover Main Sewer Line Issues in Older Homes?
This question is critical in our region, where many charming older homes have aging infrastructure. The answer to does home insurance cover main sewer line problems in older homes requires special attention.
Older homes face higher risks due to materials like clay or cast iron that are prone to corrosion and root intrusion. Securing coverage can be challenging if problems already exist, so the key is timing. It’s best to add a service line endorsement before issues arise.
The benefits far outweigh the cost. For just $40 to $60 per year, you gain peace of mind and financial protection against repairs that can cost $5,000 to $25,000 or more. This endorsement fills the critical gap left by standard insurance, covering the gradual damage most likely to affect your older home’s sewer line.
At Mitchell-Joseph Insurance Agency, we understand these unique challenges. With our experience and access to 24 insurance companies, we can find the right protection for your home’s specific needs.
Don’t wait for a disaster. Contact us today for a personalized assessment and to Get a quote for Sewer Line Insurance. Let us help you secure the peace of mind you deserve.

