

The Value Beyond Price: Why Jewelry Insurance Matters
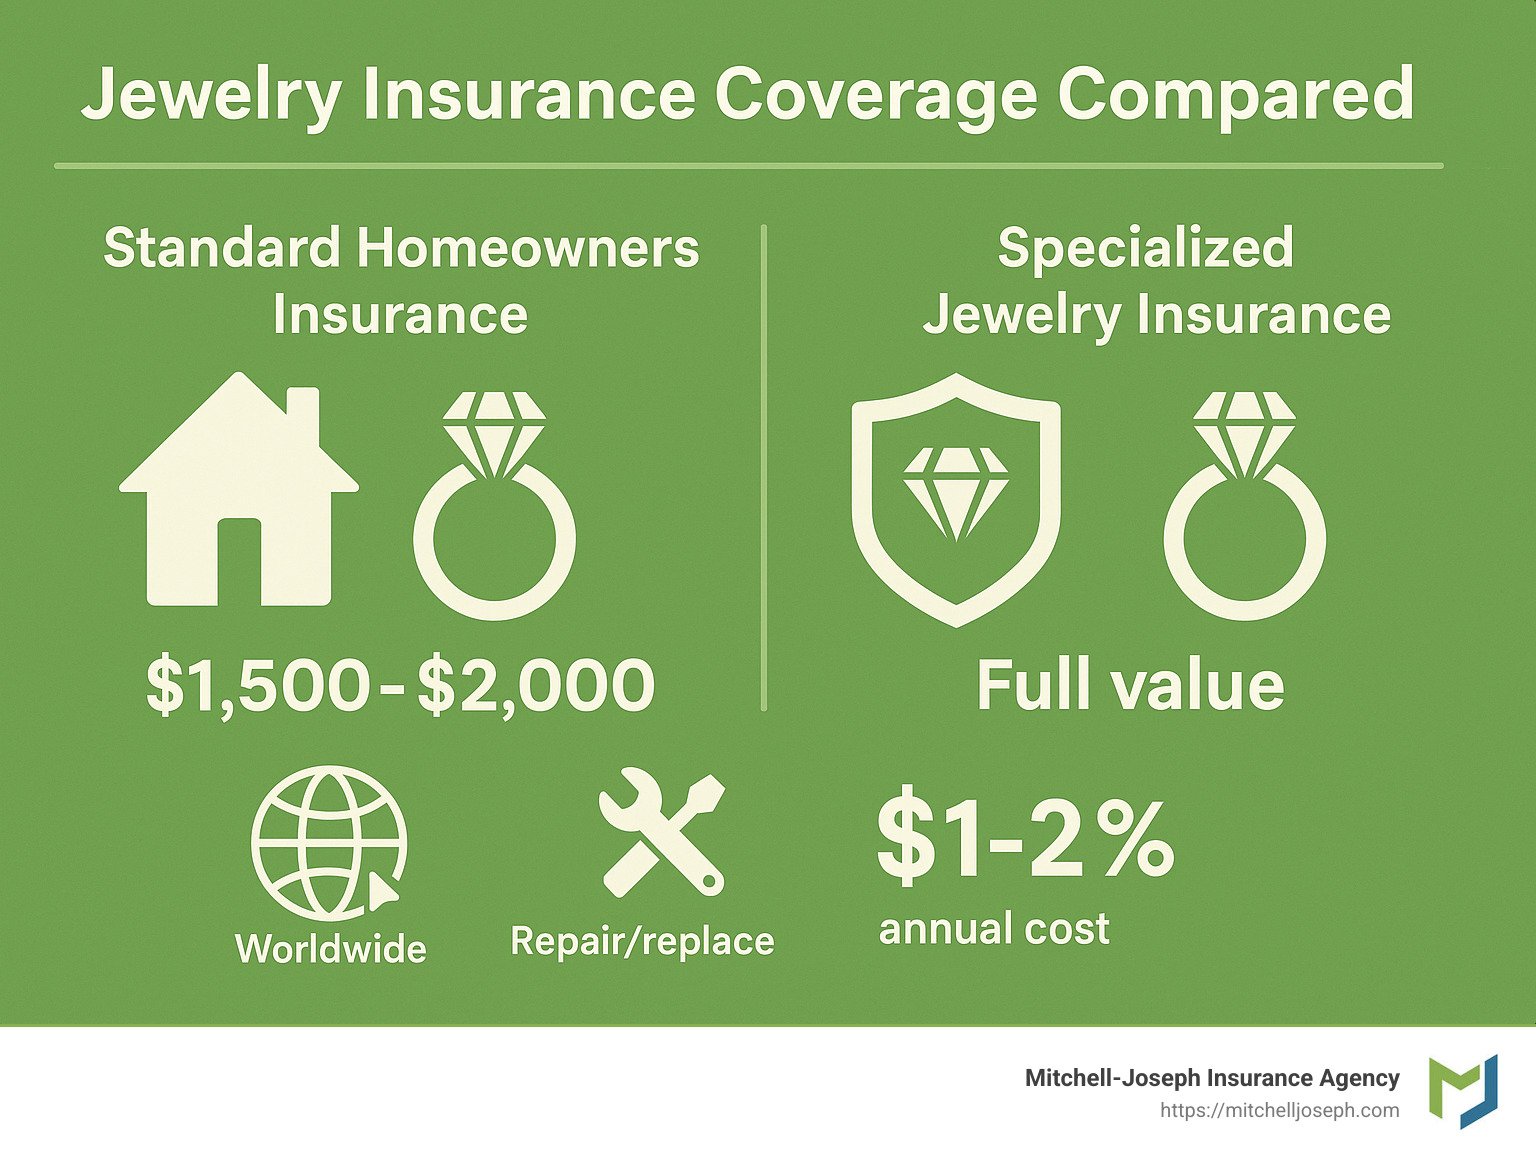
Do people put insurance on expensive jewelry? Yes, many people insure their valuable jewelry, with estimates suggesting that about 40-60% of owners of high-value pieces (over $5,000) obtain specialized jewelry insurance. This insurance typically costs 1-2% of the jewelry’s value annually and provides protection beyond what standard homeowners policies offer.
| Why People Insure Expensive Jewelry | What’s Typically Covered |
|---|---|
| Financial protection for high-value items | Theft, loss, and damage |
| Limited coverage in standard homeowners policies (typically only $1,500-$2,000) | Mysterious disappearance |
| Sentimental value preservation | Worldwide protection |
| Peace of mind during travel or daily wear | Repair or full replacement |
| Protection from a common target of theft | Some policies include preventative maintenance |
Imagine slipping off your grandmother’s diamond ring to wash your hands in a hotel bathroom, only to realize moments later it’s no longer there. Or picture your custom-designed engagement ring damaged beyond repair after an accident. These scenarios aren’t just about financial loss – they represent memories, milestones, and emotional attachments that can’t be quantified.
With over $100 million worth of jewelry stolen annually according to FBI statistics, and countless more pieces damaged or lost, the risk to your precious items is real. Yet many homeowners are shocked to find their standard insurance policies provide minimal coverage for these valuable possessions – often capping benefits at just $1,500 per item.
My name is Jeffrey Joseph, and as the owner of Mitchell-Joseph Insurance Agency since 1999, I’ve helped hundreds of clients steer the complexities of properly insuring their expensive jewelry, and I’ve seen how specialized coverage has saved both the financial and sentimental value of irreplaceable pieces.
Basic do people put insurance on expensive jewelry terms:
- expensive jewelry insurance
- how to insure expensive jewelry
- travel insurance for expensive jewellery
Do People Put Insurance on Expensive Jewelry?
When it comes to protecting those sparkling treasures in your jewelry box, you might wonder: do people put insurance on expensive jewelry? As someone who’s helped countless clients safeguard their precious pieces over my years at Mitchell-Joseph Insurance Agency, I can tell you the answer is absolutely yes.
From our offices serving Rochester to Canandaigua and beyond, we’ve watched more and more jewelry owners seek specialized coverage each year. It’s not just the ultra-wealthy protecting million-dollar necklaces either – everyday people are insuring engagement rings, family heirlooms, and special occasion pieces.
The numbers make sense when you think about it. Industry data shows jewelry insurance typically costs between 1-2% of your item’s appraised value per year. That beautiful $5,000 engagement ring? You might pay just $50-$100 annually for complete protection. When you consider what that ring represents – both financially and emotionally – that’s quite a bargain for peace of mind.
Why Do People Put Insurance on Expensive Jewelry?
There’s something deeply personal about jewelry that sets it apart from other possessions. That’s why protecting these items matters on multiple levels.
Financial protection is the obvious first reason. With today’s engagement rings averaging around $5,500, replacing one without insurance would be a serious financial setback for most households. But the value goes beyond dollars and cents.
The sentimental value often far outweighs the price tag. I’ll never forget when one of our clients, Sarah, called after we helped replace her stolen anniversary pendant. “The insurance couldn’t replace the exact memories,” she told me, “but it allowed me to create a new piece that honored those memories.” That’s what this coverage is really about.
Risk mitigation is another practical factor. Jewelry is portable, valuable, and unfortunately, easily targeted by thieves. Even the most careful owners face risks of accidental damage, mysterious disappearance, or theft.
Perhaps most valuable of all is the peace of mind that comes with proper coverage. Jewelry should be worn and enjoyed, not locked away out of fear. As one jewelry industry expert perfectly put it, “Losing a unique piece can be emotionally and financially devastating.” With the right insurance, you can wear your treasures confidently wherever life takes you.
What Types of Expensive Jewelry Are Commonly Insured?
While insurance makes sense for any valuable jewelry, certain types appear on policies more frequently than others.
Engagement rings and wedding bands top the list, and it’s easy to understand why. Beyond their financial value (which often exceeds standard homeowners policy limits), these symbols of commitment carry immeasurable emotional significance.
Heirloom pieces passed through generations often combine historical significance, family connection, and substantial monetary value. I’ve helped clients insure everything from Victorian brooches to mid-century cocktail rings – each with its own unique story.
Luxury watches represent significant investments that deserve protection. Whether it’s a classic Rolex passed down from father to son or a newly purchased Patek Philippe, these precision timepieces often warrant specialized coverage.
Custom jewelry created by designers or local artisans holds special importance because these one-of-a-kind pieces simply cannot be replaced with an off-the-shelf alternative. The uniqueness makes proper valuation and coverage essential.
High-value collections often need specialized attention. I’ve worked with clients who collect specific types of jewelry – vintage Art Deco pieces, colored gemstones, or designer signed jewelry – and helped them develop appropriate coverage strategies for their entire collections.
From our offices in Honeoye Falls and throughout New York, we’ve helped protect everything from modest family treasures to six-figure diamond necklaces. The common thread? Each piece matters deeply to its owner, and that’s what makes proper insurance so important.
The Benefits of Insuring Expensive Jewelry
When you invest in a beautiful piece of jewelry, you’re not just buying a shiny object – you’re investing in something that often carries deep personal meaning. That’s why so many of our clients at Mitchell-Joseph ask us: “do people put insurance on expensive jewelry?” After helping hundreds of clients protect their treasured pieces over the years, I’ve seen how jewelry insurance provides both practical protection and emotional reassurance.
Financial Protection Against Loss, Theft, and Damage
Standard homeowners insurance just doesn’t cut it when it comes to your valuable jewelry. Those policies typically cap coverage at around $1,500-$2,000 per item – far below the value of many engagement rings, heirloom pieces, or luxury watches.
Specialized jewelry insurance, on the other hand, wraps your precious items in a comprehensive blanket of protection. Your diamond pendant remains covered whether it’s stolen from your bedside table in Honeoye Falls or accidentally dropped down a drain while traveling abroad. This “all-risk” approach means you’re protected against theft, accidental damage, and even what insurers call “mysterious disappearance” – that frustrating situation where you simply can’t pinpoint when or how your item went missing.
I remember helping a client from Rochester who traveled to Paris for business and finded the center stone of her engagement ring had fallen out somewhere between meetings. She was devastated, assuming replacement would be complicated since she couldn’t say exactly when it happened. But her specialized jewelry policy covered the entire replacement with minimal hassle – something her homeowners policy would never have done.
The worldwide coverage aspect is particularly valuable. Whether you’re at home in Canandaigua or vacationing in the Caribbean, your protection travels with you. This gives you the freedom to actually wear and enjoy your jewelry rather than leaving it locked away at home out of fear.
Preserving Sentimental Value
The emotional aspect of jewelry insurance is something many people don’t consider until they need it. A good policy doesn’t just cut you a check – it helps preserve the meaning behind your pieces.
When my client Sarah from Victor had her 25th anniversary ring damaged beyond repair, she was heartbroken. The ring represented a quarter-century of marriage, and no amount of money could replace those memories. Her specialized jewelry policy understood this dimension, working with her preferred local jeweler to create an identical replacement using the same quality materials and craftsmanship. As she told me afterward, “It’s not the original, but having something that looks and feels exactly the same helps keep those memories alive.”
Many quality policies offer “like kind and quality” replacement, which means they’ll ensure your replacement piece matches the original in terms of materials, design, and workmanship. They’ll often work with your preferred jeweler and even replace entire sets if one piece is lost (imagine losing one earring from your grandmother’s pair – getting a perfect match for the remaining one would be nearly impossible without proper insurance).
What surprises many of our clients across the Rochester area is just how affordable this comprehensive protection can be. Typically, jewelry insurance costs between 1-2% of the item’s value annually. That means a $5,000 engagement ring might cost just $50-$100 per year to insure – about the price of a nice dinner out to protect something irreplaceable. When you break it down, that’s roughly $4-$8 per month for both financial security and peace of mind.
The relief I see on clients’ faces when they know they can freely wear and enjoy their special pieces without constant worry is perhaps the greatest benefit of all. After all, jewelry is meant to be worn and cherished, not hidden away in fear of loss.
Understanding Jewelry Insurance Options
When I sit down with clients at our Honeoye Falls office to discuss protecting their precious jewelry, I often see the same look of surprise when I explain their current coverage. Most people assume their beautiful pieces are fully protected, but the reality is quite different. Let’s clear up the confusion about your options.
How Does Jewelry Insurance Differ from Homeowners or Renters Insurance?
Here’s the truth that catches many people off guard: your standard homeowners or renters policy probably isn’t giving your jewelry the protection it deserves.
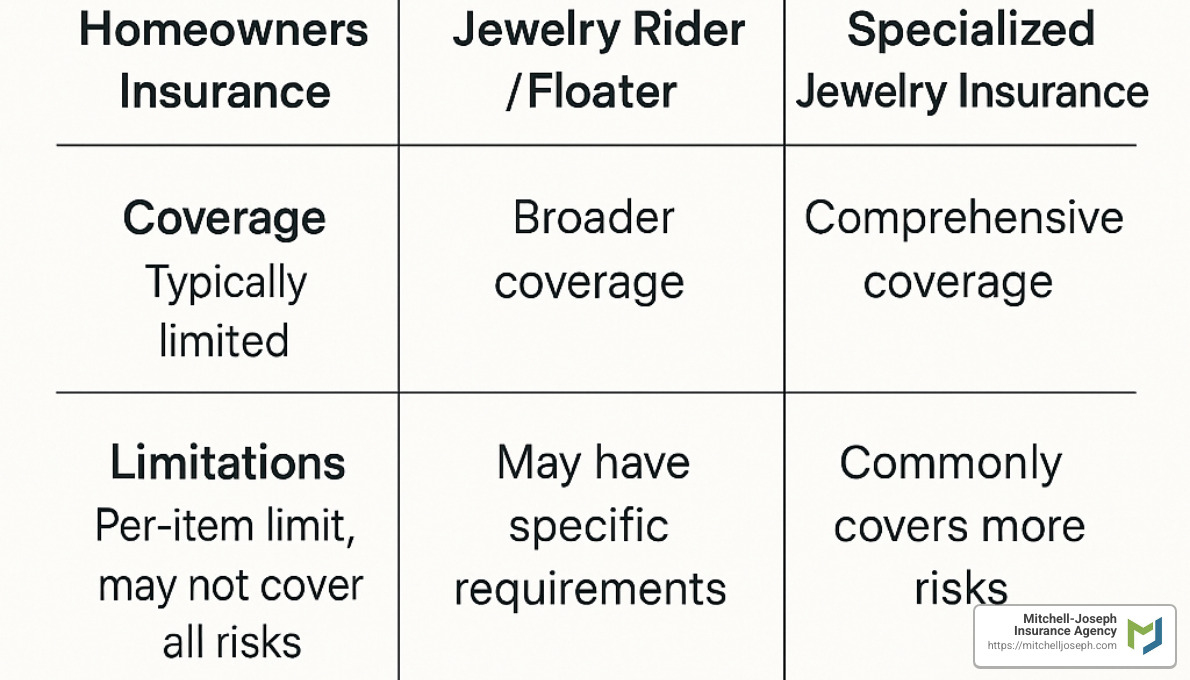
Most standard policies cap jewelry coverage at just $1,500 to $2,000 per item. That vintage diamond necklace worth $10,000? Your policy might only cover a fraction of its value if it’s stolen or damaged. Even worse, many policies have a collective limit for all jewelry—typically around $5,000 to $10,000 total.
Beyond these low limits, standard policies often restrict what types of losses they’ll cover. Your engagement ring damaged while gardening? Your earring that mysteriously disappeared during your vacation? These common scenarios might leave you paying out of pocket.
One of our clients from Brighton learned this lesson the hard way. She lost a diamond from her engagement ring while swimming at Canandaigua Lake. Her homeowners policy denied the claim because it wasn’t considered “theft” or a covered peril. Had she secured proper jewelry insurance, the $3,500 replacement cost would have been covered.
Another critical difference is that filing a jewelry claim on your homeowners policy could impact your future rates or even your insurability for all your home coverage—something many homeowners don’t realize until it’s too late.
Coverage Options Available for Insuring Jewelry
You have three main paths to properly protecting your precious pieces:
Scheduled Personal Property Endorsement (Rider)
This is essentially an add-on to your existing homeowners or renters policy. We help many clients in Rochester and surrounding areas add these riders to provide fuller protection for specific pieces.
With this option, we’ll list (or “schedule”) each valuable item individually on your policy. You’ll need an appraisal that documents not just the value but also provides a detailed description of each piece. As one appraiser told me, “An appraisal states not only the value for the jewelry but also a thorough description of the jewelry.”
The advantage? Coverage up to the full appraised value and broader protection than your base policy offers. The downside? Claims still affect your homeowners insurance rates.
Blanket Coverage Endorsement
If you have several moderately valuable pieces rather than one or two high-value items, this might be your best option. Rather than scheduling each piece, we add a higher overall limit for all your jewelry to your homeowners policy.
This approach is simpler and often doesn’t require individual appraisals for each item, though there’s usually still a per-item limit. Many of our clients in communities like Victor and Pittsford find this works well for their collection of nice but not extremely valuable pieces.
Standalone Jewelry Insurance Policy
For truly valuable pieces, this specialized coverage often provides the most comprehensive protection. It’s a separate policy designed specifically for jewelry, with “all-risk” coverage including that troublesome mysterious disappearance scenario that standard policies exclude.
These policies typically offer worldwide protection, zero-deductible options, and will work with your preferred jeweler for repairs or replacements. One major benefit? Claims don’t affect your homeowners insurance rates.
A client from Mendon who travels frequently for work chose this option for her anniversary diamond. When the center stone was damaged during a business trip to Chicago, her standalone policy covered the full replacement with her favorite local jeweler in Canandaigua—no questions asked.
Finding the right coverage depends on your specific jewelry collection and needs. At Mitchell-Joseph Insurance Agency, we pride ourselves on taking the time to understand both your treasured pieces and your concerns, then matching you with the perfect protection option.
If you’re wondering whether your valuable jewelry has the protection it deserves, I recommend visiting the American Gem Society to find a professional appraiser as your first step. With an accurate, current appraisal in hand, we can help you explore all your coverage options.
How to Insure Your Expensive Jewelry
Getting your precious jewelry properly insured doesn’t need to be complicated, but it does require some attention to detail. After helping hundreds of clients protect their valuable pieces over the years, I’ve seen how following the right steps can make all the difference when the unthinkable happens.
Determining the Value of Your Jewelry for Insurance Purposes
The cornerstone of proper jewelry insurance is knowing exactly what your pieces are worth. Think of it as the foundation upon which your entire protection plan is built.
Professional appraisals are absolutely essential for any piece worth over $1,000. Just last month, I worked with a client from Honeoye Falls who thought her grandmother’s sapphire ring was worth maybe $2,000—the professional appraisal revealed it was closer to $8,500! Without that appraisal, she would have been severely underinsured.
A good appraisal isn’t just about putting a price tag on your jewelry. It should include detailed descriptions of the metals, gemstones, craftsmanship, and distinctive features. Photographs should accompany the written details, capturing the piece from multiple angles. As one jewelry expert told me, “An appraisal states not only the value for the jewelry but also a thorough description of the jewelry.” This comprehensive documentation becomes your proof of what you owned if you ever need to file a claim.
I recommend my clients get their valuable jewelry reappraised every 2-3 years. Gold and diamond prices fluctuate significantly, and you don’t want to be caught with outdated values. You can Find a Professional Appraiser with the American Gem Society to ensure you’re working with a qualified professional.
For recently purchased items, your original receipt can be sufficient temporarily, especially for pieces bought within the past couple of years. However, even with new purchases, I suggest getting a formal appraisal for anything worth over $3,000.
Beyond appraisals, maintaining your own detailed documentation creates an extra layer of protection. Take clear photographs showing any unique characteristics, record any identifying marks or inscriptions, and safely store certificates like GIA reports for diamonds. I always tell clients to keep this information in a secure location separate from the jewelry itself—perhaps in a digital cloud storage or a safe deposit box.
Steps to Take to Insure a New Piece of Jewelry
When that beautiful new piece of jewelry comes into your life—whether it’s an engagement ring, anniversary gift, or family heirloom—taking prompt action to protect it is crucial.
Start by reviewing your current coverage situation. Most standard homeowners or renters policies have surprisingly low sublimits for jewelry—typically around $1,500 to $2,000 per item. One of my Rochester clients was shocked to find her $9,000 engagement ring had only $1,500 of coverage under her existing policy!
Based on your jewelry’s value and significance, you’ll need to choose between adding a rider to your existing homeowners policy or obtaining a standalone jewelry policy. For particularly valuable or irreplaceable items (typically those over $5,000), I usually recommend standalone coverage to my clients. These specialized policies offer broader protection and don’t affect your homeowners insurance rates if you need to file a claim.
When requesting a quote, be prepared to share detailed information about the piece. Insurance companies need to understand exactly what they’re covering, so your appraisal documents, photographs, and any certificates are essential. They’ll also want to know about security measures in your home—do you have a safe? An alarm system? These factors can actually help reduce your premium.
After providing all necessary documentation and completing the application, take time to thoroughly review the policy before finalizing it. Understand exactly what is and isn’t covered, note any special requirements (like storing items in a safe when not worn), and set a reminder to review your coverage periodically as values change.
A client from Canandaigua recently told me: “When my husband surprised me with a diamond bracelet for our anniversary, I had no idea how to insure it properly. Mitchell-Joseph walked me through everything—from getting it appraised to finding the right coverage. Now I wear it confidently knowing it’s protected, and the peace of mind only costs about $7 a month!”
For more detailed guidance on the process, you can visit our guide on How to Insure Expensive Jewelry.
Do people put insurance on expensive jewelry? The smartest ones certainly do—especially when they understand how affordable proper protection can be compared to the alternative of losing something precious forever.
Potential Drawbacks of Not Insuring Expensive Jewelry

I’ve seen it happen too many times in my years at Mitchell-Joseph Insurance. A client walks in, devastated after losing a precious piece of jewelry, only to find they have inadequate coverage. While jewelry insurance costs just pennies on the dollar compared to the value of your treasured pieces, going without it can leave lasting financial and emotional scars.
Risks of Underinsurance or No Insurance
The moment you realize your grandmother’s diamond pendant is missing from your jewelry box or watch in horror as your engagement ring slips down a drain can be heart-stopping. These moments happen more often than you might think – with the FBI reporting over $100 million of jewelry stolen every year.
Financial devastation is the most immediate consequence. When that average $5,500 engagement ring disappears, most standard homeowners policies will only cover a fraction of its value – typically $1,500 to $2,000 at most. I’ve had to deliver this news to tearful clients who assumed their homeowners policy had them fully covered. One Rochester client put it bluntly: “It felt like losing the ring twice – once when it was stolen, and again when I found out I’d have to pay thousands out-of-pocket to replace it.”
Beyond the money, there’s the emotional toll that’s impossible to quantify. A client from Canandaigua shared with me how burglars took her mother’s wedding ring during a break-in. “The $8,000 value was significant,” she told me, “but what really broke my heart was losing that connection to my mom and the family history that went with it.” Without insurance, she not only lost the physical ring but also the ability to pass that legacy to her daughter.
The replacement challenges add another layer of stress. When you’re uninsured, you’re often forced to compromise – settling for a lower quality replacement, waiting months or years to save up, or simply accepting that a custom or antique piece is gone forever. One client described it as “settling for a photocopy when you’ve lost an original masterpiece.”
There’s also the ripple effect on your other insurance. Many people don’t realize that filing jewelry claims on a homeowners policy can trigger rate increases across all your home coverage. A Rochester client learned this the hard way: “After filing a claim for my stolen watch, my homeowners premium jumped 18%. Had I known, I would have gotten a separate jewelry policy that wouldn’t have affected my home insurance.”
Travel presents special risks that many don’t consider until it’s too late. Jewelry often gets removed for swimming, stored in hotel rooms, or worn in unfamiliar places – all increasing the likelihood of loss. Standard policies may have geographic limitations or exclusions for travel-related losses, leaving you especially vulnerable when you’re away from home. I’ll never forget the client who lost her tennis bracelet on her honeymoon in Hawaii – a bitter start to married life that could have been prevented with proper coverage.
When you weigh these potential consequences against the modest cost of dedicated jewelry insurance – typically just 1-2% of an item’s value annually – the decision becomes much clearer. That beautiful $5,000 ring can be fully protected for about the same monthly cost as a couple of coffee shop visits.
As I often tell my clients here in Honeoye Falls and the surrounding communities: insurance isn’t just about protecting things – it’s about protecting the memories, milestones, and moments those things represent. And some things, once lost, simply can’t be replaced at any price.
Frequently Asked Questions about Insuring Expensive Jewelry
After helping countless clients in Rochester, Canandaigua, and surrounding areas protect their precious jewelry over the years, I’ve noticed certain questions come up time and again. Let me share straightforward answers to what people most want to know:
Is Jewelry Insurance Worth It?
When clients ask me this question, I always share a simple truth: peace of mind is priceless.
For most jewelry owners, specialized insurance offers exceptional value. The annual premium typically runs just 1-2% of your item’s value – a small price compared to the potential financial and emotional cost of losing something precious.
This coverage goes beyond what standard policies offer, protecting against virtually all risks, including that dreaded “mysterious disappearance” scenario (like when your ring somehow vanishes while gardening).
I remember a client from Victor who insures her $12,000 custom anniversary ring for about $180 yearly. As she told me, “It’s the best money I spend each year. I never worry about wearing my ring, even when traveling or swimming.”
The value becomes even more apparent for pieces with deep sentimental value, items worth more than $1,500 (which exceeds typical homeowners policy limits), antique or custom jewelry that would be nearly impossible to replicate, or collections representing significant investment.
How Much Does Jewelry Insurance Cost?
Good news – protecting your precious gems and metals won’t break the bank. Most policies cost between 1-2% of the item’s appraised value annually. This means:
- That $5,000 engagement ring? About $50-$100 per year
- A $10,000 luxury watch? Roughly $100-$200 annually
- A $25,000 collection? Approximately $250-$500 yearly
Several factors can nudge your premium up or down. Your location matters (some ZIP codes have higher theft rates), as do security measures like home alarms or safes (which often earn you discounts). Your deductible choice and any additional coverage options will also influence pricing.
I recently helped a client from Pittsford find standalone coverage for her $20,000 jewelry collection for just $285 annually – actually less than adding a rider to her homeowners policy would have cost, while providing much broader protection. She was delighted!
Does Homeowners Insurance Cover Expensive Jewelry?
This question often leads to surprised faces when I explain the reality. Yes, standard homeowners and renters policies do include some jewelry coverage – but with significant limitations that many people find too late.
Most policies cap jewelry coverage at just $1,500 to $2,000 per item, with a collective limit (typically $5,000-$10,000) for all jewelry. That beautiful engagement ring or luxury watch? Likely not fully covered.
Even more concerning, standard coverage might only apply to certain causes of loss like fire or theft, excluding accidental damage or that mysterious disappearance I mentioned earlier. Plus, your regular policy deductible (often $500-$1,000) applies to jewelry claims, further reducing any potential payout.
A Rochester client learned this lesson the hard way when her $3,000 pendant was stolen during a break-in. Her homeowners policy had a $1,500 sublimit for jewelry and a $1,000 deductible, resulting in just a $500 payout – nowhere near enough for replacement.
There’s also the ripple effect to consider: filing a jewelry claim on your homeowners policy could affect your overall insurance rates or even your policy’s renewability. That’s why for truly valuable pieces, either scheduling them specifically on your homeowners policy or getting a standalone jewelry policy is almost always the wiser choice.
For do people put insurance on expensive jewelry, the answer is clear – those who understand the limitations of standard policies and value both financial protection and peace of mind certainly do.
Conclusion
Do people put insurance on expensive jewelry? Absolutely—and for good reason. Throughout our years serving communities across the Rochester area, we’ve seen how specialized jewelry insurance has protected countless clients from both financial loss and heartbreak when treasured pieces were damaged, lost, or stolen.
The decision to insure your valuable jewelry ultimately comes down to answering a simple question: Could you comfortably absorb the financial and emotional impact of losing or damaging your most precious pieces? For most owners of high-value jewelry, the answer is no—making specialized coverage an essential part of a comprehensive financial protection plan.
With premiums typically costing just 1-2% of an item’s value annually, jewelry insurance represents a modest investment compared to the comprehensive protection it provides. A $5,000 engagement ring can be fully insured for as little as $50-$100 per year—about the cost of a nice dinner out to protect a symbol of your commitment and love.
I remember helping a client from Canandaigua who had hesitated to insure her grandmother’s sapphire necklace. “It’s just another bill,” she had told me. Six months later, when that necklace slipped off during a vacation, she called me in tears—not just about the financial loss, but about losing that connection to her grandmother. That’s when the true value of jewelry insurance becomes crystal clear.
At Mitchell-Joseph Insurance Agency, we understand that every piece of jewelry tells a story—whether it’s an engagement ring representing the start of a life together, a family heirloom connecting generations, or a special gift commemorating an important achievement. Our team of experienced agents across our Honeoye Falls, Pittsford, Naples, and other New York locations is dedicated to helping you find the right coverage to protect both the financial and sentimental value of your precious jewelry.
Think of jewelry insurance as protection for the moments and memories your pieces represent. That diamond necklace isn’t just platinum and stones—it’s your 25th anniversary celebration. That vintage watch isn’t just gears and hands—it’s your father’s legacy. These stories deserve protection just as much as the physical items themselves.
Don’t wait until after a loss to find the limitations of your current coverage. Contact us today for a personalized consultation and quote to ensure your valuable jewelry receives the protection it deserves. For more information, visit Is Your Expensive Jewelry Insured?
Remember: The true value of jewelry insurance isn’t just measured in dollars and cents—it’s measured in preserved memories, continued traditions, and the confidence to wear and enjoy your most treasured pieces without worry.

