

When That Underground Pipe Becomes Your Problem
Do I need exterior water line insurance? Here’s the quick answer: Yes, if your home is over 30 years old, you have large trees, or you lack $3,000-$5,000 in emergency savings. Maybe not, if your home is new, you have a robust emergency fund, and your area has no history of water line issues. The average water line replacement costs $3,750, but can reach $22,500—and your standard homeowners policy won’t cover it.
Most homeowners are surprised to learn they are responsible for the underground pipe bringing water to their home. When that line breaks, it can become a budget-breaking emergency fast.
Here’s the catch: your standard homeowners insurance almost never covers these repairs. Policies typically exclude damage from wear and tear, gradual deterioration, and pipe aging—the exact reasons most exterior water lines fail.
Key risk factors include:
- Home age: Pipes over 50 years old are at highest risk.
- Pipe material: Cast iron and lead fail more often than PVC or copper.
- Location: Freeze-thaw cycles in upstate New York stress pipes.
- Tree roots: Large trees can crush buried lines.
- Financial cushion: Can you afford a major unexpected repair?
As Jeffrey Joseph from Mitchell-Joseph Insurance Agency, I’ve helped homeowners across the Finger Lakes region answer this question for over two decades. I’ve seen who benefits from this coverage and who wishes they had it when a 60-year-old pipe gives out.
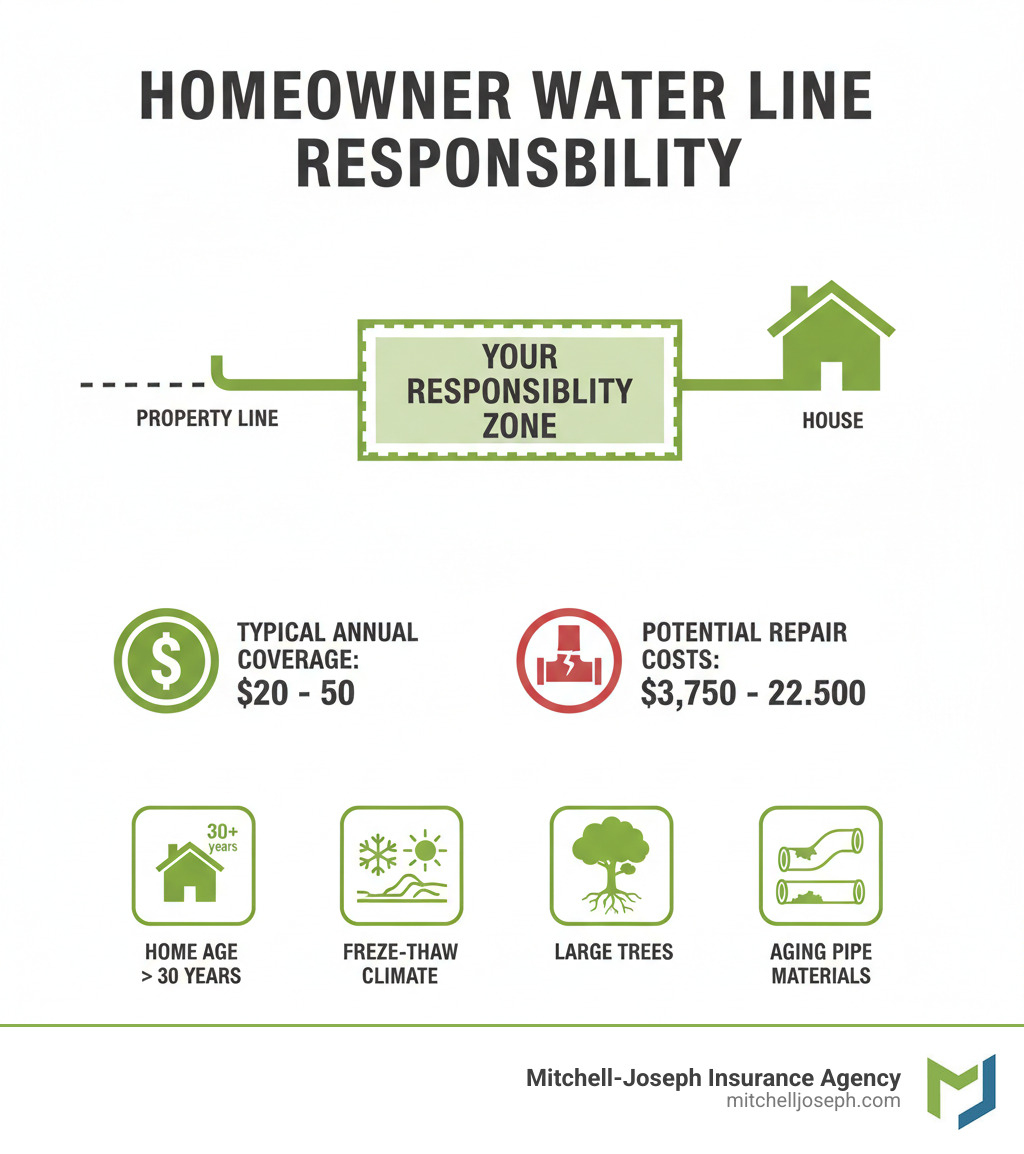
Do i need exterior water line insurance terms at a glance:
The Big Question: Do I Need Exterior Water Line Insurance?
Deciding if you need exterior water line insurance requires understanding why your current policy won’t help, the actual repair costs, and what the right coverage includes.
Why Your Standard Homeowners Policy Falls Short
Most homeowners are shocked to learn their regular insurance won’t cover a broken exterior water line. Standard policies are for sudden, unexpected disasters, not problems that develop over time.
Insurance companies view a pipe corroding for 40 years as wear and tear or gradual deterioration, which are standard exclusions. Pipes don’t last forever; they are constantly exposed to moisture, soil, and temperature changes. Insurers see their eventual failure as predictable maintenance, not a covered event. A homeowner in Pittsford with a premium policy learned this the hard way, paying $4,200 out-of-pocket when her claim was denied for gradual deterioration.
Another key issue is service line ownership. Your local utility maintains the main lines under the street, but the pipe from the property line to your house is yours. You own it, you maintain it, and you pay to fix it. This distinction between utility vs. homeowner responsibility catches people off guard. Don’t assume your Insurance Coverage/Home Insurance policy covers you; check the exclusions section or call us for a plain-English explanation.
The Shocking Cost of a Water Line Break
When an exterior water line breaks, you’re paying for a major operation. Costs include:
- Excavation: Digging a trench to access the pipe, which can mean tearing up your lawn, driveway, or patio.
- Pipe & Labor: Materials like copper can cost $20-$30 per foot, plus skilled labor. In upstate New York, lines are buried deep to avoid frost, increasing labor costs.
- Restoration: Refilling the trench, re-sodding your lawn, and replanting landscaping.
The average cost to replace your main water line is $3,750, according to Fixr.com. A simple repair might be around $1,215, but a complex 100-foot replacement could cost $22,500. We’ve seen bills across this range in Rochester and Naples. Without dedicated coverage, an unexpected $3,750 bill is difficult for most families; a $10,000+ bill can be devastating.

What Does Exterior Water Line Insurance Actually Cover?
This specialized coverage, often called service line coverage, is designed to fill the gap. A solid policy covers the repair and replacement of your damaged exterior water line.
What’s typically covered:
- Excavation costs to access the pipe.
- Backfilling and restoration of your lawn, landscaping, driveway, and walkways.
- Additional living expenses if the break makes your home unlivable.
- Damage from perils like: corrosion, wear and tear, tree root invasion, freezing, ground shifting, and accidental breakage.
What’s typically not covered:
- Pre-existing conditions (damage that existed before the policy started).
- Interior plumbing issues.
- Blockages without physical damage to the pipe.
- Wells, septic systems, and irrigation lines.
Coverage is often available for your incoming water line, outgoing sewer line, or a combined plan. The combo plan is usually the most comprehensive. For more details, see our pages on Service Line Insurance and Sewer Line Insurance.
So, Do I Need Exterior Water Line Insurance? A Self-Assessment
The answer depends on your home, finances, and risk tolerance. Ask yourself these questions:
- How old is my home? If it was built before 1970, your pipes are likely past their expected 50-year lifespan. This is a key consideration for those with Home Insurance for Old Homes.
- What are my pipes made of? Cast iron or lead pipes are high-risk and prone to corrosion. Copper and PVC are more durable but still vulnerable.
- Does my climate pose a risk? In the Finger Lakes region, harsh freeze-thaw cycles put enormous pressure on underground pipes.
- Are there large trees nearby? Mature tree roots are notorious for crushing water lines. This is a common issue in established neighborhoods like Pittsford and Honeoye Falls.
- What’s my financial situation? Could you comfortably absorb a surprise repair bill of $3,000 to $22,500? If not, the modest annual premium for coverage is a smart financial safeguard.
- Has my neighborhood had issues? If neighbors are replacing their lines, yours could be next.
For many homeowners in our area, especially in older developments where infrastructure is aging, water line insurance provides essential financial protection and peace of mind.
Making the Final Decision: Is It Right for You?
You understand the risks and costs. Now it’s time to make a decision that protects your home and your budget.
Weighing the Cost vs. the Benefit
The math for exterior water line insurance is compelling. You can spend $20-$50 annually to protect against repair bills that average $3,750 and can exceed $22,500.
- Endorsements vs. Standalone Plans: Adding coverage as an endorsement to your homeowners policy is often the best value, costing $20-$50/year for high limits ($10,000-$25,000). Standalone plans from utility companies may cost more ($60-$96/year) and often have lower coverage caps.
- Deductibles & Limits: Pay attention to the deductible (usually $500-$1,000) and ensure the coverage limit is high enough for a worst-case scenario in your area.
- The Cost of Inaction: Skipping a $35 annual premium could leave you facing a $5,000 repair bill out-of-pocket. One claim can pay for decades of premiums.
At Mitchell-Joseph Insurance Agency, we’ve seen this coverage save clients from financial stress time and again. It’s about the peace of mind that comes from knowing a broken pipe won’t derail your finances.
How to Get Covered and File a Claim
If you’ve decided you need coverage, getting it is straightforward.
Getting Started:
Start by contacting your current homeowners insurance provider to ask about adding a service line endorsement. As an independent agency working with 24 different carriers, Mitchell-Joseph can shop on your behalf to find the best coverage and price for homeowners in the Finger Lakes region.
When adding coverage, ask about:
- Coverage limits: Are they high enough for a major repair?
- Deductible: What is your out-of-pocket cost?
- Waiting period: Most policies have a 30-day wait before coverage begins.
- Exclusions: What isn’t covered?
Filing a Claim:
- Identify the problem: Look for signs like a high water bill, low pressure, or soggy spots in your yard.
- Shut off the water: Turn off your main water valve to prevent further damage.
- Document everything: Take photos or videos of the evidence.
- Call your provider: Contact your insurance company’s 24/7 hotline. An agent can guide you through the process.
- Get professional help: Your insurer will dispatch a pre-screened, licensed contractor to diagnose and handle the repair.
- Restore your property: After the repair, the insurer oversees and pays for the restoration of your lawn, landscaping, and driveway, minus your deductible.
Choosing a provider is about more than price. Consider their reputation, contractor network, and experience with local conditions. We’ve made it easy to learn more on our water line insurance services page, or you can reach out via our contact page.
Exterior water line insurance is a smart financial decision for many homeowners. For a few dollars a month, you buy priceless peace of mind, knowing a broken pipe won’t become a financial catastrophe.

