

Why Smart Condo Insurance is a Must-Have in Rochester
Condominium insurance Rochester owners need protects your personal belongings and covers gaps in your association’s master policy. With many condo owners facing potential financial risks, having the right HO-6 policy is essential for protecting your investment and peace of mind.
Quick Answer for Rochester Condo Insurance:
- Average Cost: Around $26 per month (similar to Minnesota averages)
- Coverage Type: HO-6 policy for personal property, liability, and interior structure
- What’s Covered: Personal belongings, liability protection, additional living expenses, loss assessment
- What’s NOT Covered: Building exterior, common areas (covered by HOA master policy)
- Key Need: Fills gaps between your association’s master policy and your personal protection
Condo living means sharing walls, common areas, and responsibility. While your condominium association has a master policy for the building and shared spaces, you’re responsible for everything inside your unit—from your furniture and electronics to potential liability claims.
Many condo owners mistakenly assume their association’s policy covers their personal property and interior damage. The truth is more complex. Your association’s master policy might be “bare walls” (covering only the basic structure) or “all-in” (including some fixtures), but either way, significant gaps exist that only your personal condo insurance can fill.
Without proper coverage, you could face thousands in out-of-pocket costs for replacing belongings, liability claims, or special assessments when the association’s policy falls short.
I’m Jeffrey Joseph, and I’ve helped Rochester area residents with insurance decisions since 1999 at Mitchell-Joseph Insurance Agency. My experience with condominium insurance Rochester policies has shown me how crucial it is to understand what protection you need and where to find competitive rates.
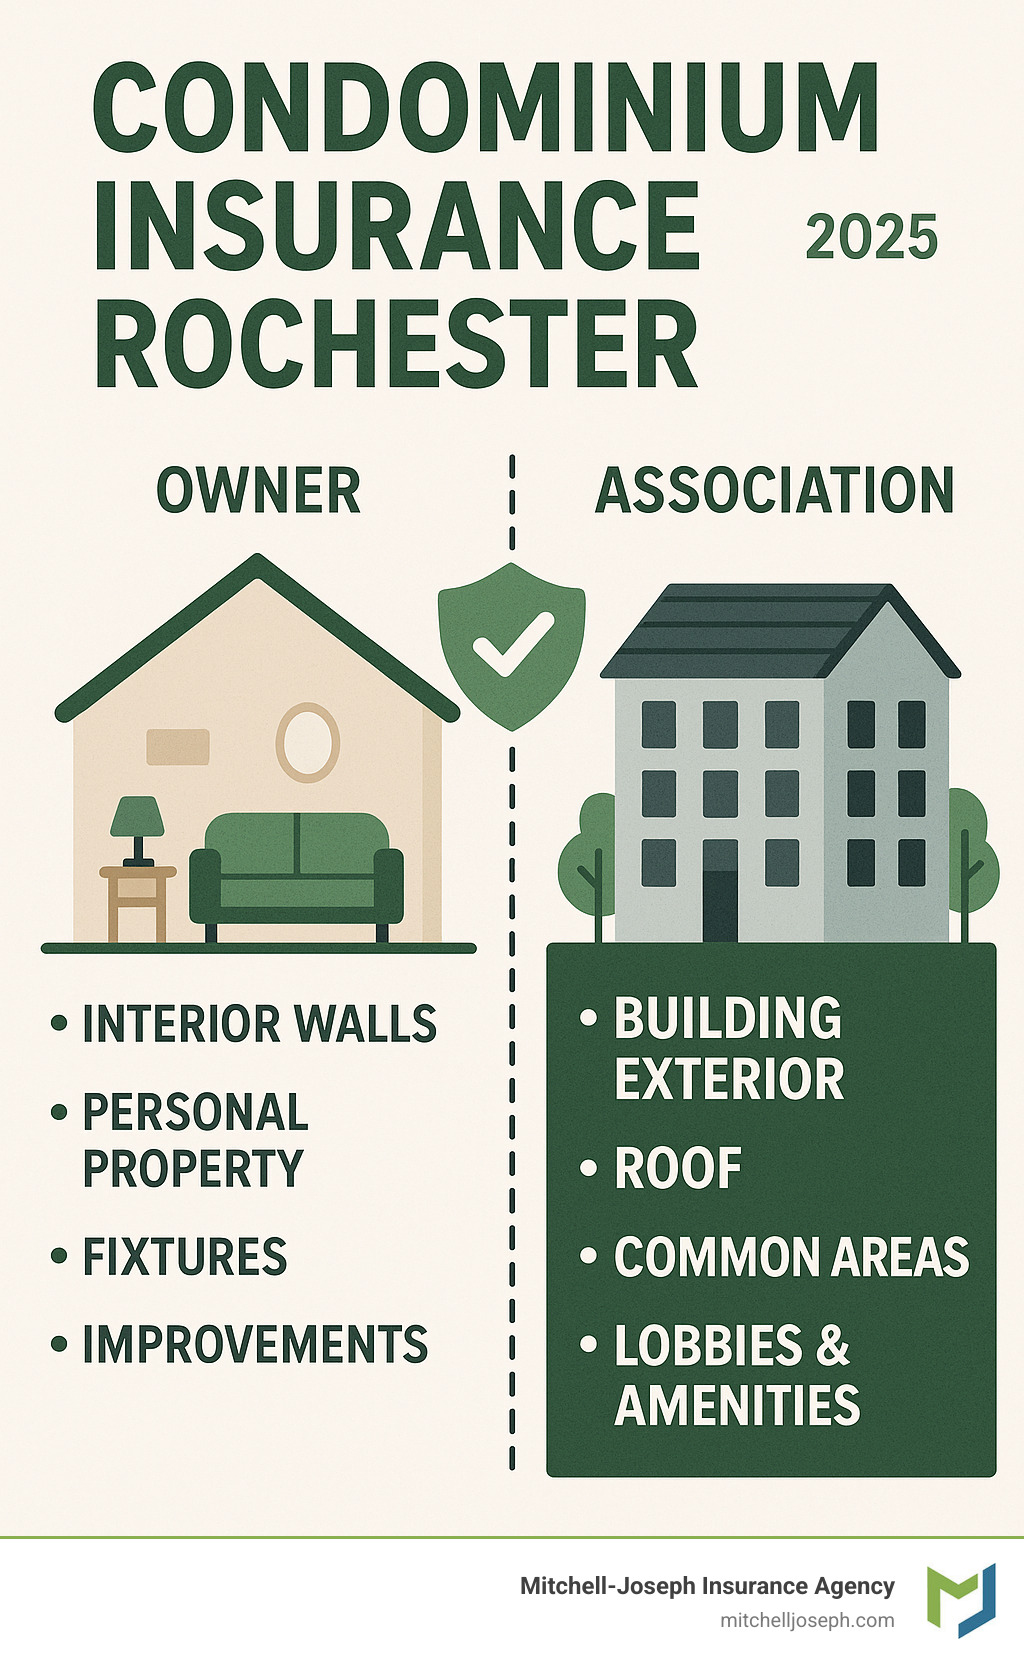
Key condominium insurance Rochester vocabulary:
Decoding Your Policy: A Guide to Condominium Insurance in Rochester
Understanding condo insurance can feel like solving a puzzle, but it’s simple once you see how the pieces fit. The key to condominium insurance Rochester coverage is knowing you’re in a team effort with your condo association.
The Master Policy vs. Your Personal HO-6 Policy
Your condo association buys a master policy to protect the building and shared spaces. This policy is the foundation, but it often has gaps you need to fill with your own insurance.
Knowing which of the two main types of master policy your association has is critical.
“Bare walls” policies cover the basic structure—the exterior walls, roof, and common areas. Inside your unit, you’re responsible for everything. If a pipe bursts, the association might fix the pipe, but you’re on the hook for your floors, furniture, and custom cabinets.
“All-in” policies are more generous, typically covering permanent fixtures like the original cabinets and appliances. The catch is they only cover builder-grade items. Your upgrades and personal belongings are still your responsibility.
This is where your personal HO-6 condominium insurance Rochester policy is essential. It picks up where the association’s coverage stops, protecting everything from your walls inward.
The smartest thing you can do is get a copy of your HOA’s master policy. Spending 10 minutes understanding what it covers could save you thousands. For more details, check out our guide on Insurance for Condo Associations.
Key Coverages for Your Rochester Condo Insurance Policy
These four coverage types are the backbone of any solid condominium insurance Rochester policy.
Personal property coverage protects all your belongings: furniture, electronics, clothes, and more. This coverage often follows you outside your condo. We always recommend replacement cost coverage over actual cash value. Replacement cost buys you a new couch, while actual cash value gives you what your old one was worth.
Liability protection is your financial safety net. If a guest is injured in your unit or you cause damage to a neighbor’s property, this coverage handles medical bills, legal fees, and judgments against you. Liability coverage is crucial, as lawsuits can be expensive.
Loss of use coverage applies when your condo is unlivable due to a covered event. It pays for temporary housing, meals, and other extra expenses while repairs are made.
Building property coverage protects the interior structure of your unit—your walls, floors, and fixtures. This is where your policy steps up if the master policy is “bare walls.” It also covers improvements you’ve made, from custom tile to upgraded appliances.
One more vital coverage is loss assessment coverage. If a major event affects a common area and the master policy is insufficient, the association may issue a special assessment to all owners. Condominium Loss Assessment Coverage helps pay your share, protecting you from surprise expenses.
Optional Protections for Improved Peace of Mind
You can customize your policy with add-ons for specific risks.
Water backup coverage protects against damage from backed-up drains or overflowing sump pumps. Standard policies often exclude this, making it a worthy consideration in Rochester. Learn more about Sewer and Water Backup Insurance to see if it makes sense for you.
Service line coverage handles repairs to buried utility lines running to your unit. These repairs, which can include excavation, can be surprisingly expensive.
Scheduled personal property coverage is for high-value items like jewelry or art that exceed standard policy limits. Scheduling them individually provides broader protection than the standard $1,500 jewelry limit, for example.
Identity theft protection helps you recover if your identity is stolen, covering legal fees and other restoration expenses. It’s affordable protection against a common headache.
These optional coverages ensure your condominium insurance Rochester policy fits your life, not the other way around.
Finding the Best and Most Affordable Coverage
Now that you understand what condo insurance covers, you’re probably wondering about the bottom line: “How much will this cost me, and how can I get the best deal?” The good news is that condominium insurance Rochester policies are typically quite affordable, averaging around $26 per month. But your actual premium depends on several factors, and there are plenty of smart ways to save.
Factors That Affect Your Rochester Condo Insurance Premium
Insurance companies use specific factors to calculate your condominium insurance Rochester premium. Understanding them helps you make smarter coverage decisions.
Location matters. Your specific Rochester neighborhood influences rates. Areas with lower crime, proximity to fire stations, and fewer weather claims typically have lower premiums.
Your claims history—both personal and for the building—is important. Multiple recent claims can signal higher risk to insurers. This is why it’s smart to only file claims for significant losses.
The coverage limits you choose directly impact your premium. Higher limits cost more, but being underinsured can be far more expensive long-term. We help you find the sweet spot between comprehensive coverage and affordability.
Your deductible choice is a balancing act. A higher deductible lowers your premium, but ensure you can afford it if you need to file a claim. Many Rochester condo owners choose a $1,000 or $2,500 deductible.
Building construction and age are key. Newer buildings with modern, updated systems often get better rates. If your building is well-maintained, that’s another plus.
Safety features save you money. Security systems, sprinklers, controlled access, smoke detectors, and fire extinguishers can all lead to discounts.
For a deeper dive into how different coverage types work together, check out our guide on Home Insurance Coverage Types.
Smart Ways to Save: Discounts and Tips
Here are the most effective strategies to reduce your premium without sacrificing protection.
Bundling your policies is the biggest money-saver. Combining your condo insurance with your auto insurance from the same carrier can often save 15-25% on both policies and simplifies your life. If you need Auto Insurance Rochester coverage, we can show you how much bundling could save you.
Protective devices earn discounts. Insurers reward safety measures like monitored security systems, smoke detectors, fire extinguishers, and sprinklers. Mention building features like controlled access or 24/7 security for more savings.
A claims-free history earns a discount. Going three to five years without a claim often results in savings. This is why it’s wise to pay for minor repairs out-of-pocket.
Higher deductibles mean lower premiums. Increasing your deductible from $500 to $1,000 or more can significantly reduce your premium. Just be sure you have that amount readily available for a claim.
Good credit helps. In New York, insurers can use your credit score to help determine your premium. Maintaining good credit can lower your insurance costs.
Small discounts add up. Look for modest discounts for paperless billing, automatic payments, or being a new homeowner. They add up over time.
If you’re bundling policies, you might also benefit from defensive driving course discounts on your auto insurance. New York offers a defensive driving program that can reduce your auto rates, making your bundled savings even better.
How to Get a Quote and Choose Your Policy
Getting the right condominium insurance Rochester policy doesn’t have to be overwhelming. Here’s a simple process.
Start by taking inventory of your belongings. It adds up faster than you think. Many people are surprised to find they have $50,000 or more in personal property. Taking photos or videos now will also help if you ever need to file a claim.
Get a copy of your HOA’s master policy. This crucial step is often overlooked. You must know what your association covers to properly insure your unit. Your HOA board can provide this. Knowing if it’s a “bare walls” or “all-in” policy determines how much dwelling coverage you need.
Compare quotes. Rates vary significantly between companies. Working with an independent agency like ours pays off, as we do the shopping for you across our 24 different insurance companies.
Work with an expert. Condominium insurance Rochester policies are complex. The relationship between your policy and the master policy, loss assessment, and dwelling coverage details all matter. Our team has steerd these complexities for Rochester condo owners for over 38 years.
At Mitchell-Joseph Insurance Agency, we educate our clients. We’ll explain your options and the trade-offs between coverage and cost so you can feel confident. Our goal is to find you the right protection at a price that fits your budget.
Ready to get started? Contact us for a personalized quote today. We’ll review your specific situation, explain your options, and help you secure the condominium insurance Rochester coverage that gives you true peace of mind.

