

Why New York Condo Owners Need Specialized Protection
Condominium insurance ny is a specialized HO-6 policy that protects your unit’s interior, personal belongings, and provides liability coverage beyond what your condo association’s master policy covers. Here’s what you need to know:
Quick Answer for NY Condo Insurance:
- Average Cost: $656 per year ($55/month) in New York state
- NYC Average: $790 per year
- Coverage Includes: Personal property, unit interior, liability protection, loss assessment
- Not Required by Law: But often required by mortgage lenders and condo associations
Many condo owners mistakenly believe their association’s insurance covers everything. As one insurance expert notes: “Many people assume their condo association will cover claims for personal property and interior damage. The truth is, every condo owner should understand the importance of reliable condominium insurance.”
The reality is that your HOA’s master policy typically covers only the building structure and common areas. Your personal belongings, interior fixtures, and liability for incidents inside your unit remain your responsibility.
In New York, condo insurance averages $656 annually but can vary by location, from $456 in some areas to over $743 in expensive NYC zip codes. Understanding your coverage is crucial for protecting your investment.
I’m Jeffrey Joseph of Mitchell-Joseph Insurance Agency. Since 1999, I’ve helped New Yorkers with their insurance decisions. My experience with condominium insurance ny has shown me how critical it is to have the right coverage to complement your HOA’s master policy and protect your personal assets.
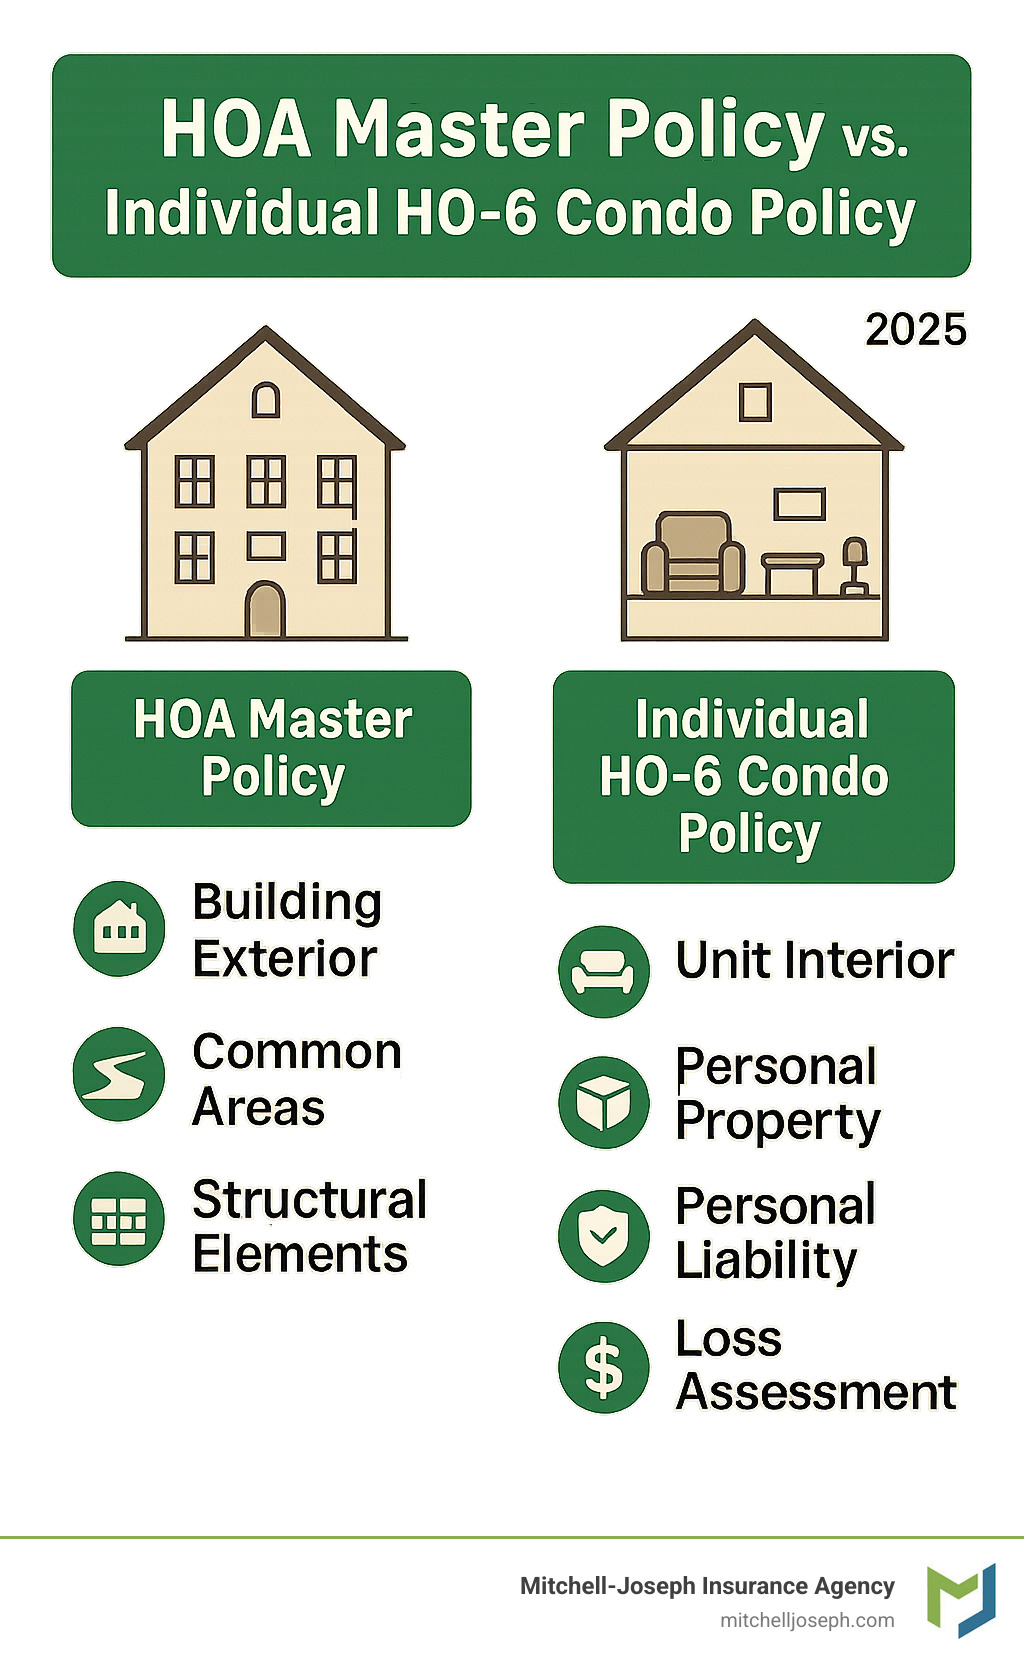
Common condominium insurance ny vocab:
Understanding the Basics of Condo Insurance (HO-6 Policy)
When you buy a condo, you own the space inside your unit’s walls, while the condo association is responsible for the building’s exterior and common areas. This shared ownership model is why condominium insurance ny is so important.
An HO-6 policy is your financial safety net, designed to work with your association’s master policy. While the HOA’s insurance covers the building structure, roof, and shared spaces like the lobby or gym, your HO-6 policy covers your personal belongings, interior improvements, and liability if someone is hurt in your unit. For New York condo owners, an HO-6 policy is essential for protecting your personal investment. We offer comprehensive Insurance for Condominium Owners and Homeowners Insurance NY for all residential properties.
Your Policy vs. The HOA Master Policy: What’s the Difference?
Understanding the difference between your policy and the HOA’s master policy can save you thousands. The HOA master policy covers the building’s exterior, structural elements, and shared spaces like hallways and elevators. However, these master policies vary in how much they cover inside your unit.
- Bare walls-in coverage is the most basic type. The HOA covers the unit down to the bare walls, leaving you responsible for flooring, interior walls, cabinets, fixtures, and all your personal property.
- All-in coverage is more comprehensive, covering the building structure plus fixtures and improvements inside your unit. Even with this policy, you still need your own insurance for personal belongings and liability.
Your individual HO-6 policy provides the walls-in protection for everything the master policy doesn’t, including your furniture, electronics, and clothing. It also provides liability coverage. We help associations understand their needs with our Insurance for Condo Associations services.
Is Condo Insurance Required in New York?
While New York state doesn’t legally require HO-6 insurance, it’s practically mandatory for two main reasons:
- Mortgage lender requirements: If you have a mortgage, your lender will almost certainly require you to carry condo insurance to protect their investment in your unit.
- Condo association bylaws: Most associations have legally binding bylaws that require unit owners to maintain individual insurance, often specifying minimum coverage amounts for property and liability.
Beyond these requirements, condominium insurance ny provides crucial financial security. It protects your assets from lawsuits and ensures you can rebuild after a disaster. Having an HO-6 policy provides invaluable peace of mind, protecting both your investment and your financial future.
What a New York Condo Insurance Policy Covers

An HO-6 policy is a comprehensive safety net designed to protect everything inside your unit. It includes several layers of protection: dwelling coverage for the physical structure, personal property coverage for your belongings, and liability protection against lawsuits, along with other essential coverages.
Standard Coverage Types
-
Dwelling coverage: This protects the interior of your unit, including walls, flooring, cabinets, built-in appliances, and any renovations or improvements you’ve made. The amount you need depends on your HOA’s master policy; if it’s a “bare walls” policy, you’ll need more dwelling coverage.
-
Personal property coverage: This covers all your belongings, such as furniture, electronics, clothing, and artwork. This coverage typically extends to your possessions even when they are outside your home. We can help you understand the details of Personal Property Condo Insurance to ensure you have adequate limits.
-
Personal liability protection: This is one of the most critical parts of your policy. It covers legal and medical costs if someone is injured in your unit and you are found responsible. It also covers damage you might accidentally cause to someone else’s property. Most policies offer between $100,000 and $500,000 in protection.
-
Additional Living Expenses (ALE): If your condo becomes uninhabitable due to a covered event like a fire, ALE pays for temporary housing, meals, and other extra costs while your unit is being repaired.
-
Medical payments coverage: This provides a small amount of coverage for minor medical expenses if a guest is injured in your condo, regardless of who is at fault. It can help prevent larger liability claims.
-
Loss assessment coverage: This is crucial for condo owners. If common areas are damaged and the HOA’s insurance is insufficient, the association may charge each owner a special assessment. This coverage helps pay your share of that cost, which can be thousands of dollars.
Common Exclusions and Optional Add-Ons
Standard condominium insurance ny policies have exclusions. Damage from flooding requires a separate policy, often through the National Flood Insurance Program (NFIP), and earthquakes are also typically excluded. Policies do not cover general wear and tear, poor maintenance, or intentional acts.
You can improve your policy with optional endorsements:
- Water backup coverage: Protects against damage from backed-up sewers, drains, or sump pumps, which is a common exclusion on standard policies.
- Scheduled personal property coverage: Provides higher, specific coverage for valuable items like jewelry, fine art, or collectibles, insuring them for their full appraised value.
- Identity theft protection: Helps with expenses and services needed to restore your identity if you become a victim of fraud.
The Cost of Condominium Insurance NY: Rates and Savings
One of the first questions condo owners ask is about the cost of condominium insurance ny. The good news is that it’s generally more affordable than homeowners insurance because you aren’t insuring the entire building. As an agency working with 24 different insurance companies, we can shop around to find you the best rates.
What is the Average Cost for Condominium Insurance NY?
In New York state, the average condominium insurance ny premium is about $656 per year, or roughly $55 per month. This is for a typical policy with $60,000 in personal property coverage, $300,000 in liability protection, and a $1,000 deductible.
Location within New York makes a significant difference. The average New York City condo owner pays around $790 annually. Rates in Manhattan’s priciest zip codes can average $743 per year, while premiums in smaller communities like East Rochester could be as low as $456.
Here’s how your personal property coverage level can affect your premium:
| Personal Property Coverage | Average Annual Rate |
|---|---|
| $40,000 | $440 |
| $60,000 | $510 |
| $80,000 | $567 |
| $100,000 | $631 |
These rates assume $300,000 in liability protection and a $1,000 deductible.
Notice that substantially increasing your coverage often results in a relatively small premium increase, adding significant protection for a modest cost.
Factors That Influence Your Premium
Your premium is based on several factors specific to you and your condo:
- Location: Your zip code informs insurers about local risks like crime rates, weather patterns, and proximity to a fire department.
- Your coverage choices: Higher limits for personal property, dwelling, and liability coverage will result in higher premiums.
- Your deductible: Choosing a higher deductible lowers your premium. Ensure you can comfortably pay this amount out-of-pocket if you file a claim.
- Your building’s characteristics: Newer buildings with modern safety features and certain construction materials often qualify for lower rates.
- Your claims history: A clean claims record can help keep your rates down, while multiple recent claims may increase your premium.
How to Find Discounts and Save Money
There are many ways to save on your condominium insurance ny premium:
- Bundling your policies: Insuring your condo and auto with the same company can lead to savings of 15-20% on both policies.
- Installing protective devices: Smoke detectors, security systems, and smart home devices can earn you discounts.
- Maintaining a claim-free record: Insurers often reward policyholders who have been claim-free for several years.
- Choosing a higher deductible: Opting for a $2,500 deductible instead of $1,000 can significantly lower your annual premium.
- Building security features: On-site managers, controlled entry, or 24/7 security can also lead to discounts.
We specialize in finding every discount you qualify for. To see what options are available, check out our guide to the Cheapest Home Insurance New York.
How to Get the Right Condo Insurance Policy in New York
Finding the right condominium insurance ny policy means matching coverage to your specific needs and budget. The process is straightforward when broken down into two key steps. With our access to 24 insurance companies, we can help you find coverage that fully protects your investment.
Step 1: Determine How Much Coverage You Need
Before shopping for quotes, assess what you need to protect and its value.
-
Create a home inventory: Document all your personal belongings, including furniture, electronics, clothing, and valuables. This helps determine your personal property coverage limit. Opt for replacement cost coverage to ensure you can buy new items, not just receive their depreciated value.
-
Estimate interior rebuilding costs: You are responsible for the cost of rebuilding everything inside your unit, from walls and flooring to fixtures and custom upgrades. These costs can vary significantly depending on your finishes and location in New York.
-
Assess your liability needs: Most experts recommend at least $300,000 in liability coverage. If you have significant assets, you may want higher limits to protect you from lawsuits.
-
Review your HOA bylaws: Your condo association’s documents specify what their master policy covers (bare walls-in, all-in, etc.) and any minimum insurance requirements for unit owners. This is crucial for avoiding coverage gaps. Our Home Insurance Coverage options are designed to complement your HOA’s policy.
Step 2: Gather Information and Get a Quote for Condominium Insurance NY
Once you know your coverage needs, gathering the right information will ensure you get accurate quotes for condominium insurance ny.
Be prepared to provide:
- Personal information: Your name, date of birth, and the condo’s full address.
- Condo details: The square footage, year of construction, and building materials (e.g., brick, frame).
- Safety features: Information on any smoke detectors, fire alarms, sprinkler systems, or security systems.
- Desired coverage limits: Your chosen limits for dwelling, personal property, and liability coverage, plus your preferred deductible.
- Insurance history: Details about any claims filed in the past five years and your previous insurance carrier.
With this information, we can quickly access quotes from our network of insurers. We’ll compare options, explain the differences, and help you choose the policy that offers the best value and protection for your New York condo.
Frequently Asked Questions about NY Condo Insurance
Insurance can be complex, and certain questions about condominium insurance ny come up frequently. Here are answers to the most common ones.
Does my condo insurance cover water damage to my neighbor’s unit?
Yes, in many cases. Your policy’s personal liability coverage is designed for this situation. If water damage originates in your unit due to your negligence (e.g., an overflowing bathtub or a burst washing machine hose) and damages a neighbor’s property, your liability coverage typically pays for their repairs. However, if the damage comes from shared building infrastructure, like a common pipe in the wall, the HOA’s master policy would likely be responsible.
What is loss assessment coverage and do I really need it?
Yes, you absolutely need loss assessment coverage. It protects you if your condo association levies a special assessment on all owners to cover costs that exceed the master policy’s limits. This can happen after a major event damages a common area, like the roof or lobby, and the repair bill is higher than the HOA’s coverage. An assessment can cost thousands of dollars out-of-pocket, making this inexpensive add-on a vital part of your policy.
I rent out my condo. Do I need a different type of insurance?
Yes, this is a critical distinction. A standard HO-6 policy is for owner-occupied units. If you rent out your condo, you need a landlord insurance policy (sometimes called a dwelling fire policy). This policy is designed for the unique risks of being a landlord and includes:
- Property protection for the unit itself.
- Landlord liability coverage for claims related to your role as a property owner.
- Lost rental income coverage to replace income if the unit becomes uninhabitable after a covered loss.
Your tenants will need their own renters insurance to cover their belongings. We specialize in Condo Insurance for Landlords to ensure you have the correct protection.
Conclusion
Choosing the right condominium insurance ny is about building a protective shield around your home and financial well-being. Your HO-6 policy works with your HOA’s master policy to fill critical coverage gaps, protecting your belongings, renovations, and assets from the unexpected.
Your condo insurance is your financial lifeline. Whether it’s a burst pipe, a kitchen fire, or a liability claim, the right policy ensures these events don’t become financial disasters. Your condo is a significant investment; it deserves proper protection.
At Mitchell-Joseph Insurance Agency, we’ve been helping New York families protect what matters most for decades. As an independent, family-owned business with over 200 years of combined experience, we understand that every condo owner’s situation is unique. We work with 24 insurance companies to find the perfect fit for your needs and budget.
We’re your neighbors in Honeoye Falls, and we provide personalized service that treats you like family. We deliver competitive quotes and expert guidance to ensure nothing is overlooked. Don’t wait for a disaster to find out if you’re properly covered. Learn more about our comprehensive home and condo insurance options today, and let’s build a plan that gives you complete confidence.

