

Why Finding the Right Condominium Insurance Near You Matters
Searching for condominium insurance near me reveals a common challenge: condo owners need specialized HO-6 coverage that complements their HOA’s master policy, and finding the right local provider can be overwhelming.
Quick Answer for Local Condo Insurance:
- HO-6 Policy Required: Your personal condo insurance covers what the HOA master policy doesn’t.
- Coverage Includes: Your unit’s interior, personal belongings, liability, and loss assessment.
- Average Cost: $100-$400 annually, or as low as $35-$40 per month.
- Local Agents: Independent agents compare multiple carriers for personalized service.
- Quote Requirements: Address, unit details, coverage needs, and claims history.
Your condo association’s master policy covers the building exterior and common areas. However, you’re responsible for everything “from the walls in”—your cabinets, flooring, personal belongings, and liability protection. Without an HO-6 policy, you could face thousands in out-of-pocket costs after a covered loss.
Fortunately, condo insurance is typically more affordable than standard homeowners insurance because you’re only insuring the interior of your unit. With average costs from $100-$400 per year, it’s a small price for significant protection. The key is finding a knowledgeable local agent who understands your HOA’s master policy and your personal coverage needs.
I’m Jeffrey Joseph of Mitchell-Joseph Insurance Agency. Since 1999, I’ve helped condo owners in the Finger Lakes region with their insurance decisions. Our team understands the unique challenges of condo ownership and works with multiple carriers to find coverage that fits your situation and budget.
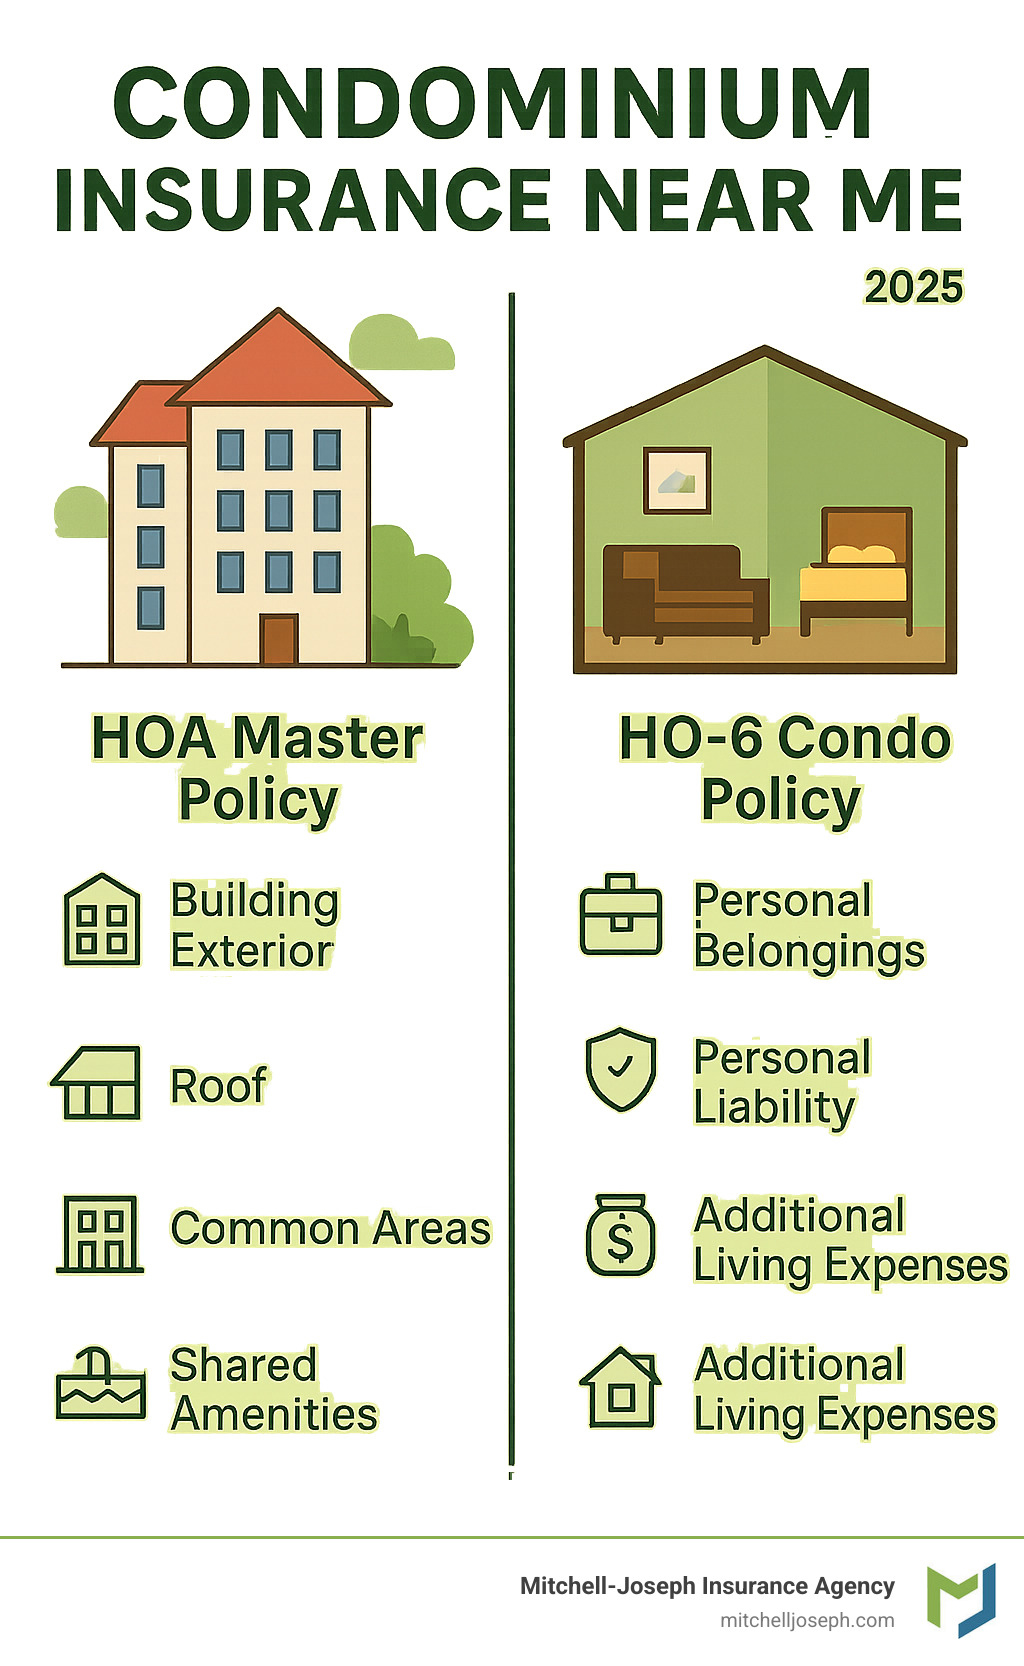
Understanding Condo Insurance: Your HO-6 Policy and the HOA Master Policy
When you search for condominium insurance near me, you’re looking for a specialized product. Condo ownership involves a unique insurance setup with two main parts: your personal HO-6 policy and the HOA master policy.
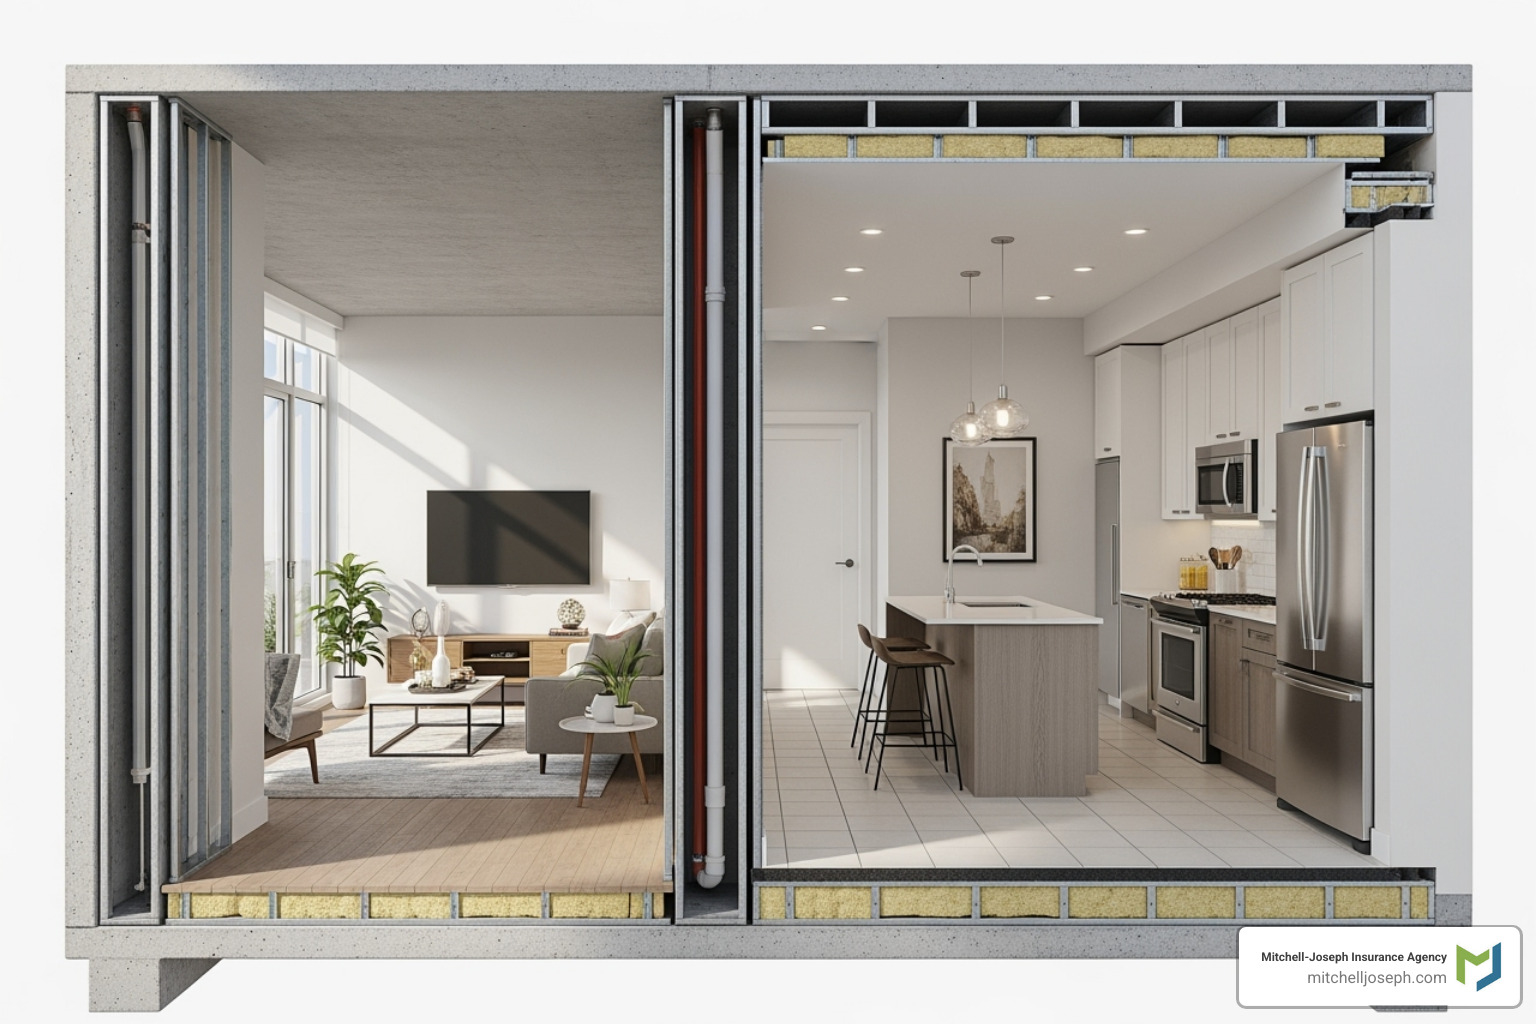
Your HO-6 policy is your personal coverage, protecting everything inside your unit and your personal liability. The HOA master policy is the shared coverage for the building structure and common areas. Unlike a traditional homeowners policy (HO-3) that covers an entire house, an HO-6 policy is designed to work with the master policy, filling in gaps to provide complete protection.
Even if your HOA doesn’t require you to carry condo insurance, your mortgage lender almost certainly will. They want to protect their investment, and so should you. Without an HO-6 policy, you could face significant out-of-pocket expenses.
We also help HOAs themselves with specialized Insurance for Condo Associations to ensure common areas are properly protected.
What Your HOA’s Master Policy Typically Covers
Your HOA’s master policy is the umbrella covering shared elements of your condo community. This includes:
- Building Structure: The exterior walls, roof, and foundation.
- Common Areas: Hallways, elevators, lobbies, fitness centers, pools, and clubhouses.
- Shared Systems: Main plumbing, electrical, and heating systems serving multiple units.
- Association Liability: Protects the HOA from claims if someone is injured in a common area.
However, not all master policies are the same. Some HOAs have “bare walls” coverage, which only covers the basic structure, leaving everything inside your unit as your responsibility. Others have “all-in coverage”, which is more comprehensive and includes original fixtures. Still, this won’t cover your personal belongings or any upgrades you’ve made.
It’s crucial to review your HOA bylaws and master policy documents so we can help you get the right personal coverage to fill any gaps.
Why Your Personal HO-6 Policy is Essential
Even with a comprehensive master policy, your personal HO-6 policy is critical. It’s your financial safety net for everything the master policy doesn’t cover.
- Interior Structure: Your HO-6 policy provides “walls-in coverage.” If a fire damages your condo, your policy replaces your cabinets, flooring, fixtures, and other interior details.
- Personal Belongings: Your furniture, clothes, electronics, and appliances are not covered by the HOA’s policy. Your HO-6 policy protects these items from damage or theft.
- Liability Protection: If someone is hurt inside your unit or you cause damage to a neighbor’s property, your HO-6 policy’s liability coverage helps pay for medical bills, legal fees, and damages.
- Loss Assessments: Master policies often have high deductibles. If there’s a major claim, the HOA may charge unit owners a special assessment to cover costs. Loss assessment coverage helps pay your share.
- Additional Living Expenses: If your condo becomes unlivable due to a covered loss, your policy helps cover temporary rent, hotel bills, and meals.
We’ve helped countless condo owners find comprehensive Insurance for Condominium Owners that protects them from these financial gaps.
What Your Personal Condo Policy Protects
Your personal HO-6 policy is customized for condo living. While the HOA’s master policy handles the building, your personal coverage focuses on your space, your belongings, and your financial well-being. If disaster strikes, your HOA might rebuild the shell of your unit, but your personal policy is what restores your home.
Here are the key protections you get when you find the right condominium insurance near me:
-
Dwelling Coverage: This protects everything “walls-in”—the paint, flooring, kitchen cabinets, and any upgrades you’ve made. If a pipe bursts and ruins your unit’s interior, this coverage helps you rebuild.
-
Personal Property Coverage: This covers your furniture, electronics, clothing, and kitchenware. We recommend creating a home inventory to understand how much coverage you need; it adds up quickly. This protection from Personal Property Condo Insurance often applies even when your belongings are outside your unit, such as a laptop stolen from your car.
-
Personal Liability Coverage: This is your financial shield against accidents. If someone is injured in your unit or you damage a neighbor’s property, this covers medical bills, legal defense costs, and settlements. We typically recommend at least $100,000 in coverage, but higher limits may be appropriate depending on your assets.
-
Additional Living Expenses: This coverage is a lifesaver if your condo becomes uninhabitable after a covered loss. It pays for hotel bills, temporary rent, and meals while your unit is being repaired.
-
Guest Medical Payments: This provides immediate coverage for medical expenses if a guest is accidentally injured in your unit, regardless of fault.
-
Loss Assessment Coverage: This is a critical but often overlooked protection. If the HOA faces a large claim that exceeds its policy limits or deductible, it can charge all unit owners a special assessment. This coverage helps pay your share of these unexpected bills.
Common Exclusions and Optional Add-ons
Understanding what your policy excludes helps you make informed decisions about optional coverages.
Standard Exclusions typically include:
- Flooding: Damage from water entering from the ground is not covered. Separate flood insurance through the National Flood Insurance Program (NFIP) is essential in flood-prone areas.
- Earthquake Damage: This requires a separate policy or endorsement.
- Wear and Tear: Insurance covers sudden, accidental losses, not gradual deterioration.
- Intentional Damage & Pest Infestations.
Optional Add-ons can fill these gaps:
- Scheduled Personal Property: Provides higher, broader coverage for valuables like jewelry, art, or collectibles.
- Water Backup Coverage: Protects against sewer and drain backups.
- Identity Theft Expense Coverage: Helps with restoration costs if your identity is stolen.
- Replacement Cost Coverage: Pays to buy new replacements for your damaged items, rather than their depreciated value. This is highly recommended.
At Mitchell-Joseph Insurance Agency, we work with 24 different insurance companies to find the right combination of standard and optional coverages for your specific needs and budget.
Decoding the Cost of Condo Insurance
When clients search for condominium insurance near me, one of their first questions is about cost. The good news is that condo insurance is typically much more affordable than regular homeowners insurance because you’re only insuring the interior of your unit.
We’ve seen policies as low as $35-$40 per month. Industry averages typically fall between $100 and $400 annually, though your actual cost will depend on several factors. For perspective, a $75,000 condo might average around $540 per year, while a $400,000 unit could be about $1,350 annually. These are just ballpark figures.
There’s a trade-off between your premium (what you pay regularly) and your deductible (what you pay out-of-pocket on a claim). A higher deductible leads to a lower premium, while a lower deductible means a higher premium. It’s about finding a balance that fits your budget and risk tolerance.
Factors Influencing Your ‘Condominium Insurance Near Me’ Premium
Several key factors will shape your premium:
- Location: Your neighborhood’s crime rates, proximity to fire departments, and local weather risks all play a role. Fortunately, the Finger Lakes region avoids many natural disasters that increase costs elsewhere.
- Coverage Limits: The more protection you choose for your dwelling, personal property, and liability, the higher your premium will be.
- Deductible Amount: Choosing a $1,000 deductible instead of $500 can meaningfully reduce your premium.
- Claims History: A clean record can qualify you for discounts, while recent claims may increase your rates.
- Building Construction: Newer construction with modern safety features and fire-resistant materials typically costs less to insure.
- Protective Devices: Smoke detectors, security systems, and deadbolt locks can earn you discounts by showing insurers you’re proactive about preventing losses.
How to Save Money on Your Policy
We’re always looking for ways to help clients save money without compromising protection.
- Bundling Policies: Combining your condo and auto insurance with the same carrier is often the easiest way to save, potentially up to 15% or more.
- Increasing Your Deductible: If you have a solid emergency fund, a higher deductible can significantly lower your premium.
- Safety Discounts: Ensure your agent knows about all protective devices in your unit, including smoke detectors, fire extinguishers, and security systems.
- Maintaining a Claims-Free History: Insurers often reward clients who go several years without filing a claim.
- Shopping with an Independent Agent: As an independent agency, we represent 24 different carriers. We compare options to find you the best combination of coverage and price, saving you the time and effort of shopping around.
How to Find the Best Condominium Insurance Near Me
Finding the right condominium insurance near me is about securing the best value—the right coverage at a fair price. This is where working with a local, independent agent makes a significant difference.
At Mitchell-Joseph Insurance Agency, we’ve been helping our neighbors with insurance since 1999. With over 200 years of combined experience, we are invested in our community and understand the local market, including risks specific to our area.
Our independence sets us apart. We aren’t tied to one insurance company; we work with 24 different carriers. This allows us to shop for you and find the coverage that best fits your situation and budget. We act as your personal insurance advocates.
When comparing quotes, compare them apples-to-apples, ensuring each has the same coverage limits and deductibles. We make this process transparent and easy to understand.
If you’re in the Rochester area, you can learn more about our local expertise through our Rochester NY Insurance Agencies services.
Information Needed to Get a Quote
Having this information ready will ensure a smooth and accurate quoting process:
- Your Address & Unit Details: The location, square footage, and number of rooms.
- Construction Details: The building materials, year built, and any major renovations.
- Safety Features: Smoke detectors, security systems, deadbolt locks, and sprinkler systems can all lead to discounts.
- Desired Coverage Amounts: An estimate of what your personal belongings are worth and the liability limit you’re comfortable with.
- Personal Information & Claims History: Your name, date of birth, and claims history from the past five years.
Steps to Get a Quote for Condominium Insurance Near Me
Getting your quote is straightforward. A little homework first will yield the best results.
- Gather Your Documents: If you have a current policy, have it handy as a baseline.
- Review Your HOA Master Policy: This is a crucial step. Understanding whether your HOA has “bare walls-in” or “all-in” coverage directly impacts what you need in your personal policy. We can help you decode the documents.
- Inventory Your Belongings: Walk through your condo and create a list or video of your possessions, noting high-value items. This ensures you get adequate coverage and simplifies any future claims.
- Contact Us: Call, visit our office, or use our online quote request. We’ll ask thoughtful questions to understand your specific needs.
- Review Your Options: We’ll present you with clear, easy-to-understand options from our network of carriers, explaining the differences in coverage and cost. Our goal is to find the right fit for you.
Frequently Asked Questions about Local Condo Insurance
These are the most common questions we hear from people searching for condominium insurance near me. Every condo owner should ask them.
Do I really need condo insurance if my HOA has a policy?
Yes, absolutely. Your HOA’s master policy covers the building’s exterior and common areas, but it leaves significant gaps in your personal protection.
Your personal HO-6 policy is needed to cover:
- Personal Property: The HOA policy does not cover your furniture, electronics, clothing, or other belongings. If there’s a fire, you would have to replace everything out-of-pocket.
- Interior Structure: You are responsible for what’s inside your unit, from the drywall and flooring to cabinets and fixtures. Your policy pays to repair or replace these items.
- Personal Liability: If a guest is injured in your unit or you accidentally damage a neighbor’s property, the HOA’s liability coverage will not protect you from a lawsuit. Your personal policy will.
- Loss Assessment: HOA master policies often have high deductibles (e.g., $10,000+). If there’s a claim for a common area, the HOA can assess all unit owners to cover the cost. Loss assessment coverage on your policy pays your share.
How much liability coverage should I get?
The general rule is that your liability coverage should at least equal your net worth. This protects your assets—savings, investments, and condo equity—in the event of a lawsuit.
Most policies start with limits of $100,000 to $300,000, but this may not be enough. If you have significant assets, you should consider an umbrella policy, which provides an extra layer of liability protection (often $1 million or more) over your condo and auto policies.
Adequate coverage provides peace of mind, as legal defense costs alone can be substantial. We can help you determine the right coverage level, and consulting a financial advisor is also a wise step.
What is the difference between ‘replacement cost’ and ‘actual cash value’?
This distinction is critical for your financial recovery after a claim. It determines how you are reimbursed for your lost or damaged belongings.
-
Replacement Cost (RC): This is the superior option. It pays you enough to buy a new item of similar kind and quality. If your five-year-old TV is destroyed, you get enough money to buy a new, comparable TV today. There is no deduction for depreciation.
-
Actual Cash Value (ACV): This coverage pays you the replacement cost minus depreciation. For that same five-year-old TV, you would receive what it was worth right before it was destroyed, which is significantly less than the cost of a new one. You would have to cover the difference yourself.
When we conduct a policy review, we almost always recommend replacement cost coverage for personal property. The small additional premium is well worth the financial security it provides during a stressful time.
Conclusion: Secure Your Peace of Mind with the Right Local Partner
Protecting your condo investment doesn’t have to be complicated. The path forward is clear: understand your unique coverage needs, identify gaps in your HOA’s master policy, and partner with an experienced local agent to guide you.
Your HOA’s policy is just the foundation. It leaves you responsible for your personal belongings, interior improvements, and liability. A personal HO-6 policy is essential to protect you from thousands of dollars in out-of-pocket expenses after a loss. The good news is that this vital protection is affordable, often costing less than a monthly coffee budget.
The value of expert advice cannot be overstated when making condominium insurance near me decisions. Cookie-cutter online solutions can’t match the personalized guidance of a local agent who understands your community.
At Mitchell-Joseph Insurance Agency, we’ve helped families in our community since 1999. As an independent, family-owned business, we work with 24 different carriers to find coverage that truly fits your situation and budget. Our team brings over 200 years of combined experience and a deep understanding of the local market. We’re your neighbors first and your insurance agents second.
Don’t leave your investment vulnerable. Let us help you get the right protection in place so you can focus on enjoying your home.
Ready to get started? Find out more about Insurance for Condominium Owners and find how easy it can be to secure your peace of mind with the right local partner.

