

Finding Affordable Home Protection in the Empire State
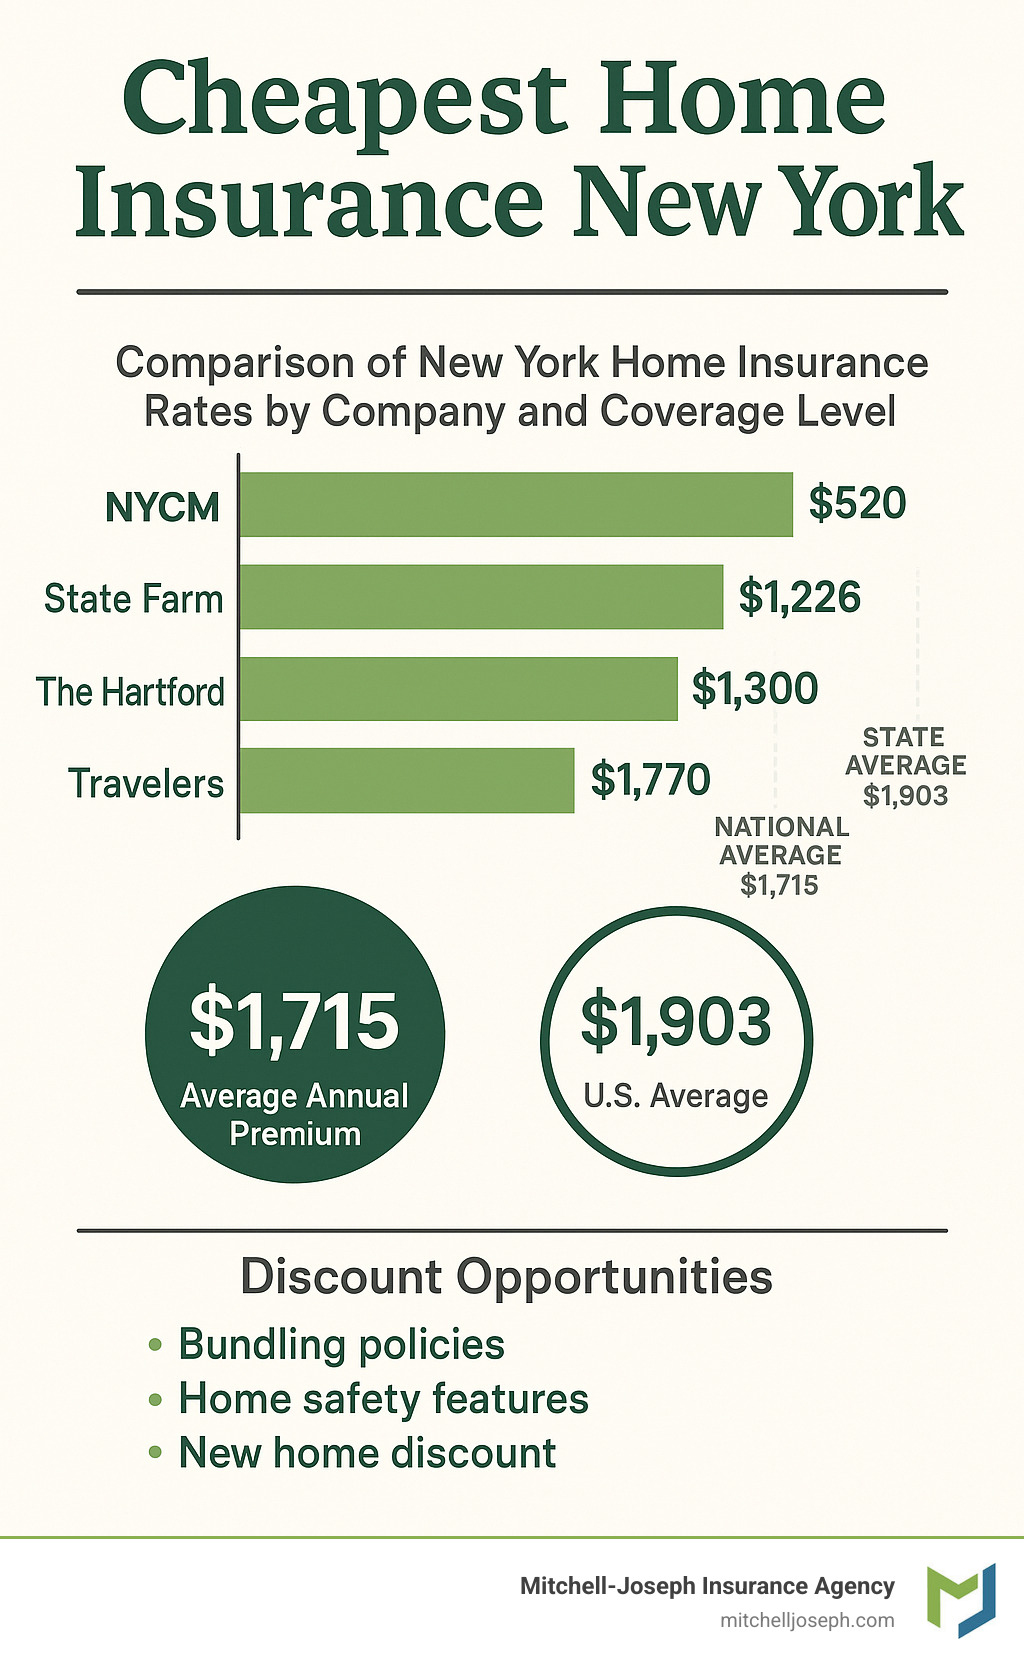
Cheapest home insurance New York snapshot for 2024 (sample premiums):
| Carrier Type | Typical Annual Rate* | % Below State Average | Common Discount Opportunities |
|---|---|---|---|
| Regional Mutual Insurer | $520 | 60% | Up to 35% for bundling |
| Large National Brand | $1,220 | 8–12% | Multi-policy savings, home safety features |
| Specialty Senior Program | $1,300 | 3% | Membership & age-based credits |
| Technology-Focused Carrier | $1,170 | 13% | Smart-home device discounts |
| New-Home Preferred Carrier | Variable | Up to 25% | Newly built or renovated homes |
*Rates shown are illustrative, based on a 2,000-sq-ft frame home with $300,000 dwelling coverage and a $1,000 deductible. Your rate will vary by location, home features, and underwriting factors.
The average cost of homeowners insurance in New York is about $1,715 per year, roughly 10% lower than the national average. Rates vary significantly depending on whether you live upstate or downstate, the age of your home, and the coverage options you choose.
New York homeowners can markedly reduce their premiums by comparing quotes, bundling policies, improving home security, and maintaining solid credit. In our internal quote comparisons, we routinely see premiums that are 40–60% lower than the statewide average for similar coverage—proof that shopping around pays off.
Expect to pay more in higher-cost areas such as NYC (average: $1,986/year) or on the coast, where hurricane risk drives up rates. Upstate cities like Buffalo or Rochester often come in closer to $1,200/year. Most insurers reward customers with generous discounts—up to 25% for bundling home and auto policies, plus additional savings for security systems, newer roofs, and claims-free histories.
I’m Jeffrey Joseph, and as the owner of Mitchell-Joseph Insurance Agency serving the Finger Lakes Region since 1999, I’ve helped thousands of New York homeowners find the cheapest home insurance New York policies without sacrificing essential protection. Our independent agency model lets us compare rates across 24 different carriers to secure the best value for you.
Basic cheapest home insurance new york vocab:
– Home Insurance Rochester
– homeowners insurance ny
Why This Guide Matters
For most New Yorkers, their home represents their largest investment. Whether you’re in a cozy bungalow in Honeoye Falls, a historic colonial in Canandaigua, or a modern ranch in Victor, protecting that investment shouldn’t break the bank.
At Mitchell-Joseph Insurance Agency, we understand the balance between adequate protection and affordable premiums. As an independent agency with access to 24 different insurance companies, we’re uniquely positioned to help you find peace of mind without emptying your wallet.
This guide matters because:
- The difference between the cheapest and most expensive home insurance options in New York can exceed $2,000 annually
- Many homeowners overpay simply because they don’t know what discounts they qualify for
- Understanding coverage basics helps you avoid paying for protection you don’t need while ensuring you have what matters most
As one client recently told us, “I was paying nearly double with my previous insurer for less coverage. I wish I’d known sooner that shopping around could save me so much.”
Cheapest Home Insurance New York: 5 Cost-Saving Fundamentals
When it comes to protecting your home in the Empire State, understanding what drives your premium costs is the first step toward savings. As I’ve helped hundreds of New York homeowners find affordable coverage over the years, I’ve noticed that many are surprised by what actually affects their rates.
Your home’s age, construction materials, and special features all play major roles in determining your premium. Here in New York, our housing stock tends to be about 63 years old on average—significantly older than many other states. This often means higher insurance costs due to aging electrical systems and plumbing. But there’s good news too!
Despite our older homes, New York residents typically pay around $1,450 annually for home insurance—well below the national average of $2,400. Why? We’re fortunate to experience fewer catastrophic natural disasters than many other regions. While coastal areas face hurricane risks and we all deal with winter storms, we don’t have the tornado frequency of the Midwest or the wildfire exposure out West.
Your credit score, claims history, and even how long you’ve maintained continuous insurance coverage all factor into your rates. Understanding the various Home Insurance Coverage Types and qualifying for Homeowners Insurance Discounts can dramatically reduce your costs.
Compare Quotes Early to Find the Cheapest Home Insurance New York Homeowners Want
I can’t stress this enough: shopping around is your most powerful money-saving tool. At Mitchell-Joseph, we’ve seen dramatic price differences between carriers for identical coverage. Just last year, we helped a family in Mendon save over $850 annually by switching carriers—with absolutely no reduction in their protection.
The beauty of working with an independent agency like ours is that we do the comparison shopping for you. Instead of spending your weekend filling out dozens of online forms or making endless phone calls, we can access quotes from multiple carriers with a single application.
My advice? Start shopping for cheapest home insurance New York options as soon as you have a signed purchase agreement on a new home. This gives you breathing room to compare options thoughtfully rather than rushing into a decision at the closing table.
Bundle Policies: A Shortcut to the Cheapest Home Insurance New York Residents Can Get
If there’s one consistent money-saver across nearly all insurance companies, it’s bundling your policies. New York homeowners typically save between 15-25% on their premiums through multi-policy discounts.
Many insurance providers offer particularly impressive bundling discounts—up to 35% when you combine home, auto, and umbrella policies. Policyholders often save an average of $1,000+ annually through bundling.
I remember a client from Canandaigua who was skeptical about bundling until we showed her the numbers. By combining her home and two cars with one company, her total insurance bill dropped by almost $1,200 a year. Plus, as she later told me, “Having everything with one company makes managing my policies so much easier.”
Beyond the obvious financial benefits, bundling simplifies your life with one renewal date, coordinated coverage that eliminates gaps, a single point of contact for claims, and one convenient bill.
Raise Your Deductible—But Keep It Affordable
Your deductible—what you’ll pay out-of-pocket before insurance kicks in—has a direct impact on your premium. Higher deductibles mean lower premiums, but there’s a sweet spot to find.
From my experience helping New York homeowners, increasing a deductible from $500 to $1,000 typically saves about 10-15% on annual premiums. Going from $1,000 to $2,500 might save another 15-20%.
However, I always have a heart-to-heart with clients about what they can actually afford in an emergency. A $2,500 deductible isn’t a bargain if you’d have to put it on a high-interest credit card after a loss.
Consider setting aside your deductible amount in an emergency fund. This gives you the confidence to select a higher deductible (enjoying those lower premiums) while knowing you’re financially prepared if disaster strikes.
Strengthen Your Home’s Defenses
Insurance is all about risk, and companies reward homeowners who take steps to minimize it. Making your home more resistant to common perils can lead to substantial discounts on your cheapest home insurance New York policy.
A new, impact-resistant roof can reduce premiums by 5-25%, particularly in areas prone to hail or high winds. Monitored security systems typically earn discounts of 5-20%, while even simple measures like deadbolts and smoke detectors can save 2-5%.
Water leak detection systems have become increasingly popular, potentially saving 3-15% while preventing catastrophic damage. And updating old electrical and plumbing systems reduces fire and water damage risk, sometimes saving 5-15%.
I remember helping a Rochester family who installed a comprehensive security system with water leak detection for approximately $1,200. Their annual insurance premium dropped by $320—meaning the system will pay for itself in less than four years while providing valuable protection and peace of mind.
Keep Your Credit Healthy and Claims History Clean
Many homeowners are surprised to learn that their credit score affects their insurance rates. In New York, homeowners with poor credit pay an average of 47% more than those with excellent credit—a difference that can exceed $800 annually.
Your claims history also impacts future premiums. While you should absolutely file claims for significant losses, consider paying for minor damage out-of-pocket if it’s only slightly above your deductible.
For example, if you have a $1,000 deductible and suffer $1,200 in damage, you might receive only $200 from your insurer—but the claim could raise your premiums by hundreds of dollars over several years.
To maintain insurance-friendly credit, pay bills on time, keep credit card balances low, don’t close old accounts in good standing, and check your credit report annually for errors. These simple habits can pay dividends in lower insurance costs year after year.
For more scientific research on average costs, check out the Insurance Information Institute’s report on homeowners insurance.
Top Budget Policy Pick #1: Basic Value Coverage
When you’re just starting out as a homeowner or working with a tight budget, you need protection that doesn’t break the bank. Our Basic Value Coverage is perfect for first-time buyers, young families, or anyone with a starter home who wants solid protection at the lowest possible price.
Think of Basic Value Coverage as the “essentials only” approach to home insurance. We focus on protecting what matters most—your home’s structure at replacement cost—while trimming optional coverages that can drive up your premium. You’ll still sleep soundly knowing your biggest investment is protected, but you won’t be paying for bells and whistles you might not need right now.
This affordable option is particularly well-suited for homes valued under $300,000, properties in lower-risk areas away from coastal regions, and homeowners who have some emergency savings set aside for smaller issues.
What makes Basic Value Coverage so budget-friendly? It’s all about focusing on the fundamentals. You’ll get all six standard coverage types: dwelling protection for your home’s structure, coverage for other structures like sheds or detached garages (typically 10% of your dwelling limit), personal property coverage for your belongings (usually 50% of dwelling coverage), loss of use funds if your home becomes uninhabitable, personal liability protection (typically $100,000), and medical payments coverage for minor injuries on your property.
The real money-saving magic happens when you choose a higher deductible—somewhere between $1,000 and $2,500—and focus on replacement cost coverage for your dwelling rather than actual cash value. This approach significantly lowers your premium while still protecting you from major losses.
Comparison of Basic Value Coverage Costs by Dwelling Limit:
| Dwelling Limit | Average Annual Premium | Monthly Cost | With Multi-Policy Discount |
|---|---|---|---|
| $200,000 | $780 | $65 | $624 |
| $250,000 | $925 | $77 | $740 |
| $300,000 | $1,070 | $89 | $856 |
| $350,000 | $1,215 | $101 | $972 |
Rates are approximate and may vary based on location, home characteristics, and other factors
I recently helped Sarah, a first-time homebuyer in Lima, find the perfect Basic Value policy. She was worried about stretching her budget too thin with another monthly bill. “Mitchell-Joseph helped me find coverage that protects my investment without straining my finances,” she told me. “The higher deductible lowered my premium, and I’m now building my emergency fund to cover that deductible if needed.”
That’s exactly the approach I recommend—choose a deductible you can manage, then gradually save that amount in an emergency fund. This strategy gives you the cheapest home insurance New York has to offer while maintaining financial security.
Want to explore more coverage options beyond the basics? Visit our Insurance Coverage: Home Insurance page for a deeper dive into what’s available as your needs and budget evolve.
Top Budget Policy Pick #2: Senior Saver Coverage
New York’s aging housing stock often aligns with an aging population. For retirees and seniors, we’ve crafted the Senior Saver Coverage—a policy package that leverages age-related discounts while providing the specific protections older homeowners need.
Many insurance companies offer excellent options for senior homeowners, with exclusive discounts available through various programs. Through Mitchell-Joseph Insurance Agency, we can access senior-specific discounts across multiple carriers to find you the best possible rate.
When we develop Senior Saver Coverage for our clients, we focus on what matters most to homeowners in their golden years. Age-based discounts typically range from 5-15% for homeowners over 55, putting real money back in your pocket each month. If you’re fully retired, you qualify for additional retiree credits with many insurers, who recognize that you’re home more often (which means you’re likely to spot problems before they become disasters).
One of our clients, a retired teacher from Fairport, was delighted to find her premium dropped by nearly $300 annually just because she was home during the day. “I had no idea being retired could save me money on insurance,” she told us. “It makes perfect sense, but no one ever mentioned it to my husband and me before.”
We also build in claims-free rewards that increase the longer you go without filing a claim. Many of our senior clients have maintained their homes for decades with minimal insurance claims, making them extremely attractive to insurance companies. This clean history translates directly into lower premiums.
Protection against inflation is particularly important for those on fixed incomes. That’s why our Senior Saver Coverage includes inflation guard protection that automatically adjusts your coverage limits to keep pace with rising rebuilding costs. You’ll never find yourself underinsured just because construction prices increased.
For seniors who’ve invested in quality appliances and systems, our equipment breakdown coverage provides peace of mind. This affordable add-on protects your HVAC systems, water heaters, and major appliances—often at a fraction of what a home warranty would cost.
A retired couple in Pittsford shared their experience: “After 40 years in the same home with only one minor claim, we were surprised to learn how much our clean record was worth to insurance companies. Mitchell-Joseph found us a policy that recognized our responsible homeownership with a premium nearly 30% below what we’d been paying.”
The cheapest home insurance New York seniors can find doesn’t mean skimping on coverage. Instead, it means taking advantage of the discounts you’ve earned through years of responsible homeownership. Our Senior Saver Coverage is particularly valuable if you:
- Are aged 55 or older
- Have lived in your home for 10+ years
- Spend most of your time at home as a retiree
- Have maintained few or no prior insurance claims
For seniors in the Rochester area curious about typical costs, our Average Homeowners Insurance Rochester NY resource provides detailed information custom to our local market.
When you’ve spent decades creating a comfortable home, you deserve insurance that respects both your experience and your budget. That’s exactly what our Senior Saver Coverage delivers.
For more information about senior-specific insurance considerations, visit the National Council on Aging’s financial security resources.
Top Budget Policy Pick #3: Bundle & Save Package
For most New York homeowners, the Bundle & Save Package offers the perfect balance between solid coverage and affordable rates. By combining your home and auto insurance—and possibly adding umbrella liability—you’ll open up the deepest discounts available in today’s market.

The numbers tell a compelling story. Many insurance providers offer bundling discounts up to 25% on home insurance with an additional 10% off your auto policy. Customers often save an average of $1,000+ each year through bundling. When you add umbrella liability protection to this combination, your savings can climb even higher.
I recently helped a family in Victor switch to our Bundle & Save Package, and their reaction says it all: “We had been paying separate companies for our home, auto, and umbrella coverage for years. After consolidating everything through Mitchell-Joseph, we’re saving over $1,100 annually—and we actually have better coverage limits now. The transition was completely seamless, and we love having one agent handling all our insurance needs.”
When you choose the Bundle & Save Package, you typically receive:
Homeowners insurance with coverage limits custom to your specific needs
Auto insurance protecting all vehicles in your household
Optional umbrella liability that extends protection beyond standard policy limits
Single-bill convenience with aligned policy periods
Unified claims process with one dedicated point of contact
The benefits go beyond just saving money. Imagine you’re in an auto accident that damages both your car and garage. With bundled policies, a single adjuster can handle your entire claim rather than forcing you to coordinate between different companies during an already stressful time.
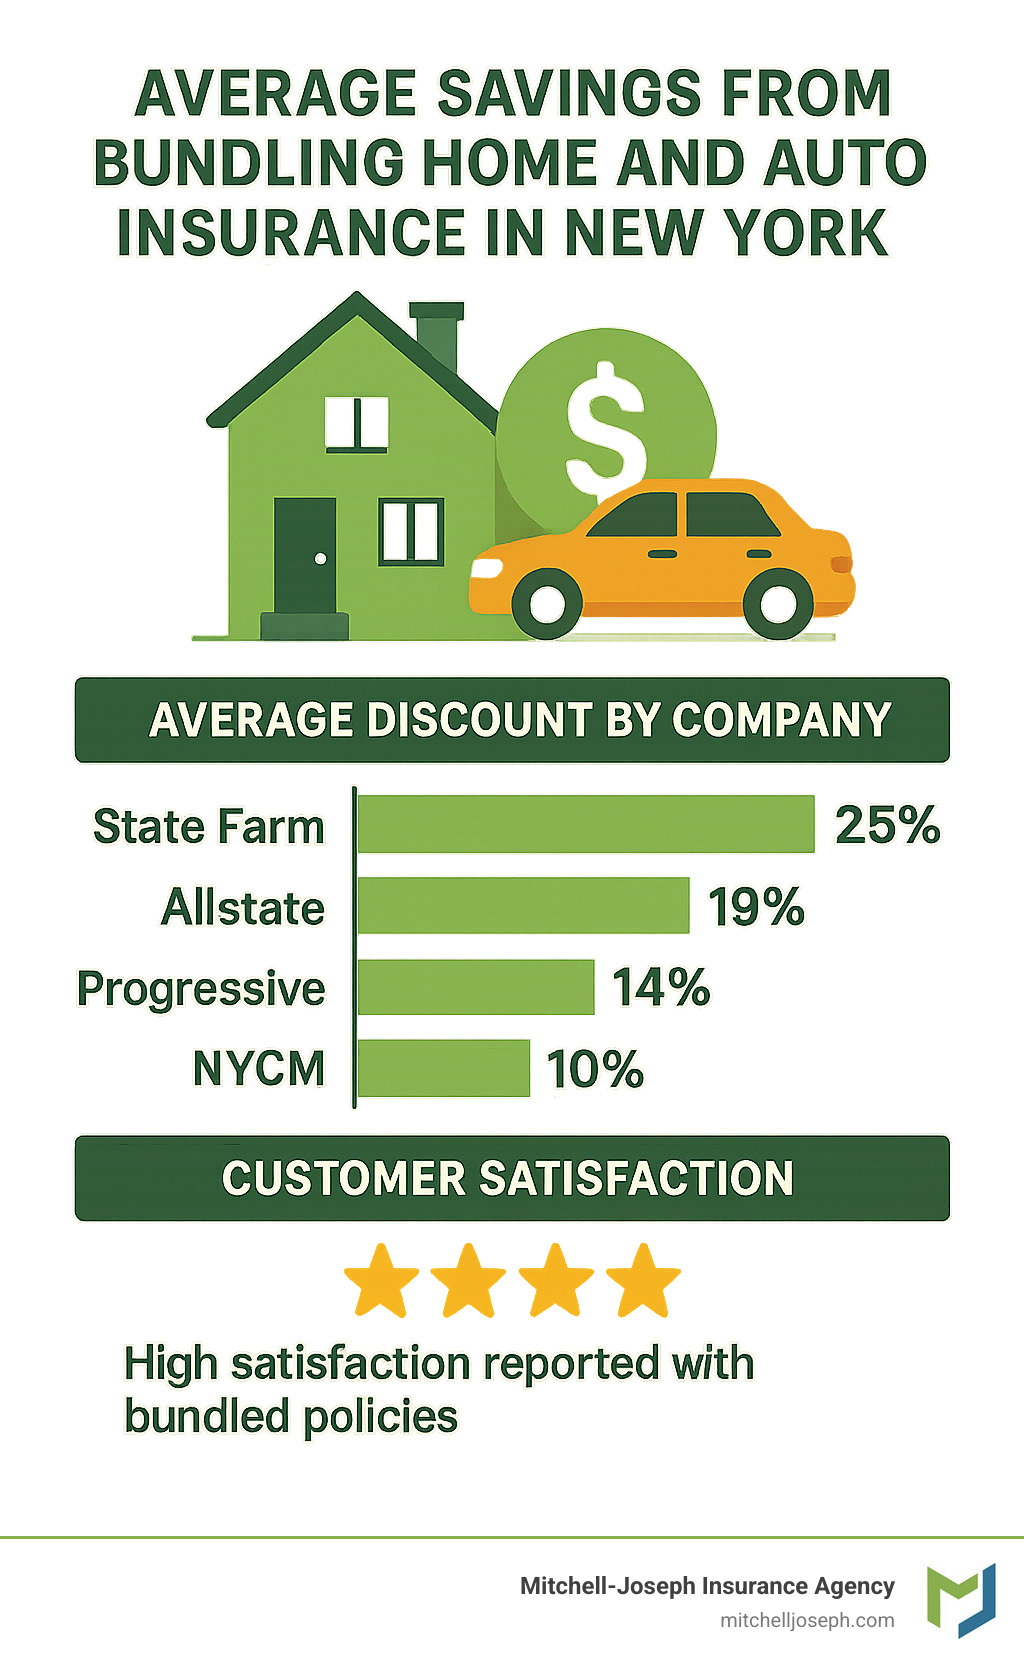
The convenience factor can’t be overstated. One renewal date to remember. One premium payment (or payment plan). One phone number to call with questions or concerns. Many of our clients tell us this simplicity is worth almost as much as the financial savings.
For homeowners in the Rochester area specifically, you’ll find additional information about local bundling opportunities on our Home Insurance Rochester resource page. We’ve compiled data specific to our region so you can see realistic savings examples from other local families.
When searching for the cheapest home insurance New York options, bundling consistently delivers the most dramatic savings for the average homeowner. As an independent agency with access to 24 different insurance companies, we can shop your bundle across multiple carriers to find the perfect combination of coverage and price.
For more information about the benefits of bundling insurance policies, check out the Consumer Financial Protection Bureau’s insurance resources.
Frequently Asked Questions about Saving on NY Home Insurance
Over the past 25+ years of helping New York homeowners find affordable coverage, we’ve heard the same questions pop up time and again. Let me share some straight-talking answers to what folks are most curious about.
Is homeowners insurance required by law in New York?
No, homeowners insurance is not legally required by New York State law. That said, if you have a mortgage (and most of us do), your lender will absolutely insist on it. They want to protect their investment in your home—which makes perfect sense.
Even if you’ve paid off your mortgage, going without insurance is like driving without a seatbelt. It’s technically allowed, but it leaves you completely exposed. Without coverage, you’d be facing the full cost of rebuilding after a fire, paying out-of-pocket for liability claims if someone gets hurt on your property, or replacing everything you own after a theft.
One client from Honeoye Falls told me: “I considered dropping my insurance after paying off my mortgage last year. After our conversation about what that would actually mean for my retirement savings if something happened, I realized it would be the most expensive ‘savings’ I’d ever make.”
What risks lead to the most claims for NY homeowners?
Understanding what actually causes most New York homeowners to file claims can help you focus your risk-prevention efforts where they matter most.
Water damage from inside sources tops the list, accounting for nearly 29% of all homeowners claims across the state. This includes burst pipes, washing machine failures, and leaky plumbing—not external flooding. Standard policies typically cover this sudden, accidental water damage, but not flooding from external sources.
Wind and hail damage comes in second at about 25% of New York claims. If you live in coastal areas or regions prone to severe thunderstorms, your roof and siding are particularly vulnerable.
Winter weather causes roughly 15% of claims across the state, with frozen pipes, ice dams on roofs, and damage from snow and ice being common culprits. Here in the Finger Lakes region, we see these claims spike every January and February.
Fire and lightning may be less common (about 10% of claims), but they’re usually the most devastating—often resulting in total losses requiring complete rebuilding.
Theft rounds out the top five at approximately 8% of claims, with urban areas naturally seeing higher rates than our rural communities.
One of our clients in Rushville shared a sobering experience: “After a major pipe burst last winter that caused over $30,000 in damage, I finally understood why you were so insistent about having the right coverage. Not only did Mitchell-Joseph help with the complicated claim process, but they adjusted my policy to better protect against similar incidents going forward.”
Which optional coverages should I add to a bare-bones policy?
While hunting for the cheapest home insurance New York options, be careful not to cut these valuable protections:
Water backup coverage is perhaps the most important optional add-on for New York homes. Standard policies don’t cover damage from backed-up sewers, drains, or failed sump pumps. For just $30-$100 annually (a couple of fancy coffees each month), you can protect against damage that often runs into the thousands.
Replacement cost for personal property ensures you can buy new items to replace damaged ones, rather than receiving only their depreciated value. Yes, it typically costs 10-15% more in premium, but the difference in payout when you need to replace a 5-year-old TV or furniture is substantial.
Ordinance or law coverage becomes crucial if your home needs repairs. This pays for upgrades required to meet current building codes—particularly important for New York’s charming but older housing stock. Without it, you could face major out-of-pocket expenses during rebuilding.
Scheduled personal property coverage protects high-value items like jewelry, art, or collectibles that exceed standard policy limits. While it does increase your premium, it provides crucial protection for those special possessions.
Identity theft protection has become increasingly important. For often just $25-$50 annually, this add-on provides resources and financial protection if your identity is compromised—a growing concern in our digital world.
I’ll never forget what happened to a client in Naples: “I initially declined water backup coverage to save $65 a year. Then my neighbor had a sewer backup that caused $18,000 in damage—none of it covered by their standard policy. I called Mitchell-Joseph that same day to add the coverage to my policy.”
Finding the right balance between affordability and protection doesn’t mean choosing the absolute cheapest option. It means finding the best value for your specific situation—something we’ve been helping New York homeowners do for over two decades.
Conclusion
Finding the cheapest home insurance New York offers while maintaining adequate protection isn’t just about pinching pennies—it’s about smart planning for your family’s security and peace of mind. After helping thousands of homeowners throughout the Finger Lakes region over the past two decades, we’ve seen how the right approach can save you hundreds or even thousands of dollars annually.
Think of insurance shopping like planning a road trip—you need to know where you’re going, compare different routes, and make smart choices along the way. At Mitchell-Joseph Insurance Agency, we’re your experienced travel companions in this journey.
Start by comparing quotes from multiple insurers. As your neighbors in the Finger Lakes, we’ve built relationships with 24 different insurance companies, allowing us to shop the market for you. Just last month, we helped a family in Victor save $740 annually simply by moving their policy to a different carrier—with better coverage than they had before!
Bundling your policies consistently delivers the biggest bang for your buck. When Sarah from Canandaigua combined her home and auto coverage through us, her savings paid for her family’s weekend getaway to the Adirondacks. Those multi-policy discounts often range from 15-25%, and that’s real money back in your pocket.
Consider choosing a higher deductible that aligns with your financial situation. One of our clients, a retired teacher from Pittsford, increased her deductible from $500 to $1,500 and saved $340 annually. She set that deductible amount aside in a dedicated savings account and has enjoyed lower premiums for years.
Don’t overlook the value of home improvements that reduce risk. New roof, updated electrical system, security system, water leak detectors—these investments often pay for themselves through insurance savings while making your home safer and more comfortable.
Your credit score and claims history matter more than you might think. We’ve seen premiums vary by as much as 47% based on credit scores alone. Paying bills on time and thinking carefully before filing small claims can keep your rates lower over time.
Whether you’re in a Victorian charmer in Honeoye Falls, a lakeside cottage in Canandaigua, or a modern home in Rochester’s suburbs, Mitchell-Joseph Insurance Agency understands the unique challenges New York homeowners face. Our team doesn’t just process policies—we build relationships, often spanning generations of the same family.
Ready to find how affordable your home protection can be? Reach out today for a personalized consultation. We’ll take the time to understand your specific situation, explain your options in plain English (not insurance jargon), and find you coverage that fits both your needs and budget.
For more information about coverage options, visit our Home Insurance page.

