

Business interruption insurance NY has taken on a pivotal role in ensuring commercial operations can withstand unforeseen disruptions. With recent legislative changes in New York, businesses now have access to expansive coverage options that go beyond traditional policies. Here’s what you need to know:
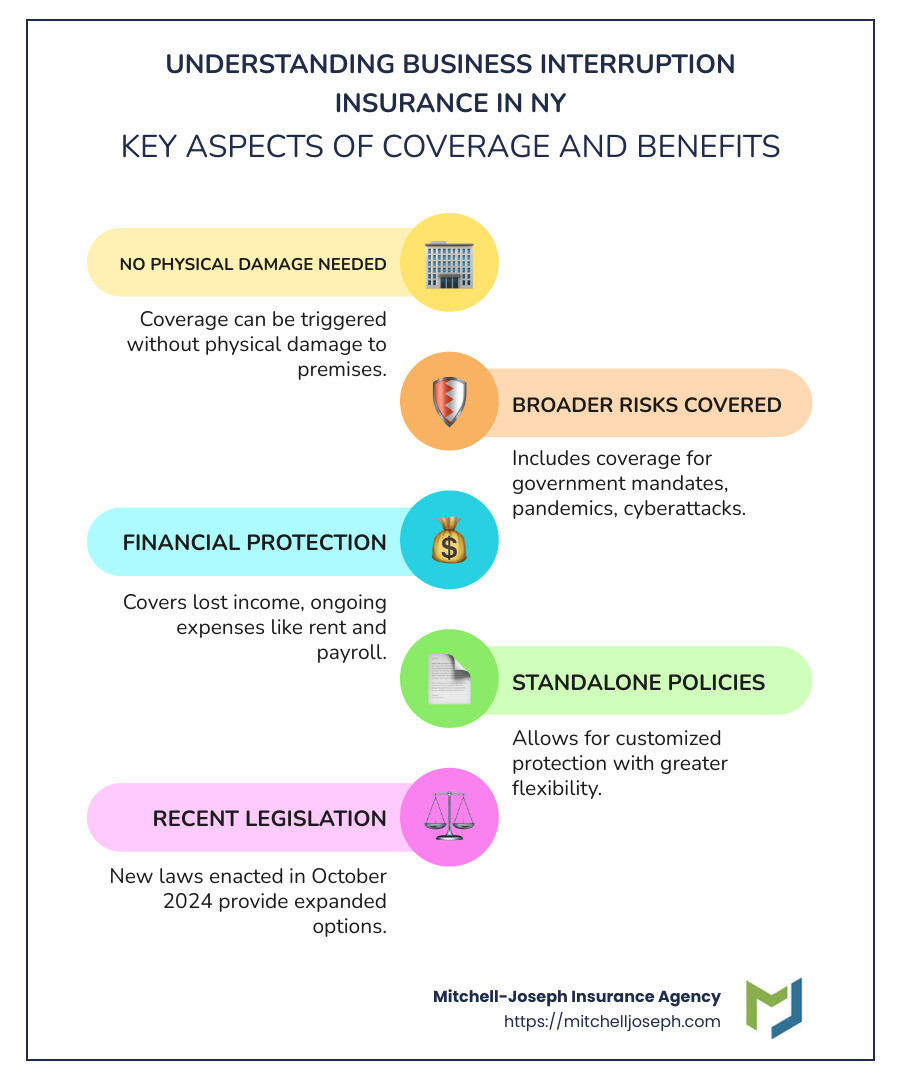
- No Physical Damage Needed: New York businesses can now purchase insurance that covers interruptions without requiring physical damage to their premises.
- Coverage for Broader Risks: Policies can cover disruptions due to government mandates, pandemics, cyberattacks, and more.
- Financial Protection: Business interruption insurance can help cover lost income, ongoing expenses like rent and payroll, and extra costs incurred during shutdowns.
In October 2024, New York enacted a law allowing stand-alone policies that don’t need a physical loss to trigger coverage. This is a game-changer for businesses in New York, providing newfound flexibility and security against various operational risks.
My name is Jeffrey Joseph, and I’ve been dedicated to providing comprehensive insurance solutions for the past 20 years at Mitchell-Joseph Insurance Agency. With our offices spread across upstate New York, we specialize in offering custom business interruption insurance NY to protect your business assets effectively. Join me as we explore this transformative shift in insurance policies.
Simple Business interruption insurance NY word guide:
Understanding Business Interruption Insurance
Business interruption insurance is a critical safety net for businesses, especially in unpredictable times. Let’s break down what this insurance covers and how it helps businesses stay afloat during disruptions.
Coverage Options
Business interruption insurance is designed to cover lost income and additional expenses when a business cannot operate due to unforeseen events. Traditionally, this type of insurance was tied to physical damage, like a fire or flood. But with recent changes in New York, the scope has expanded significantly.
- Lost Income: This is the income your business would have earned if the interruption hadn’t occurred. It’s calculated based on your financial records.
- Additional Expenses: These are the extra costs you might incur to keep your business running during a disruption. This could include renting a temporary location or setting up remote work capabilities.
What’s New in New York?
As of October 2024, New York law allows businesses to purchase stand-alone business interruption insurance. This means coverage isn’t limited to situations involving physical damage. Instead, it can also cover:
- Government Orders: If your business is forced to close due to a government mandate, you’re covered.
- Pandemics: Stand-alone policies can now include coverage for pandemics, a response to the challenges faced during COVID-19.
- Cyberattacks: With the rise of cyber threats, coverage can extend to interruptions caused by cyber incidents.
This flexibility allows businesses to tailor their insurance to specific risks relevant to their operations.
Why It Matters
Having a comprehensive business interruption insurance policy can be the difference between a temporary setback and a permanent closure. By covering lost income and necessary expenses, this insurance ensures that businesses can maintain payroll, pay rent, and continue operations even when the unexpected happens.
Recent Changes in NY Business Interruption Insurance
In 2024, New York made significant updates to its business interruption insurance landscape with the passage of Bill A10342. This legislation reshaped how businesses can protect themselves from unforeseen disruptions.
Bill A10342: A New Era for Business Protection
Signed into law by Governor Kathy Hochul on October 27, 2024, Bill A10342 allows businesses in New York to purchase stand-alone business interruption insurance. This is a game-changer, as it decouples business interruption coverage from property insurance. Previously, businesses had to bundle these policies, which often limited coverage to events involving physical damage, like fires or floods.
Standalone Policies: Custom to Your Needs
With standalone policies, businesses can now tailor their coverage to address specific risks without the need for a broader property insurance package. This flexibility means that businesses can choose coverage that fits their unique operational challenges, like:
-
Government Orders: If a government mandate forces your business to close, standalone policies can cover the resulting income loss. This is a crucial addition, especially after the widespread closures during the COVID-19 pandemic when many businesses found their policies didn’t cover such scenarios.
-
Acts of Violence: Coverage now includes losses from acts or threats of violence on the business premises. This is significant for businesses in areas prone to unrest or that face security threats.
-
Pandemics and Cyberattacks: Businesses can also opt for coverage against interruptions caused by pandemics or cyber incidents, which aren’t typically covered under traditional policies.
Access to a Broader Market
Bill A10342 also opens the door to excess line insurers, allowing licensed brokers to procure business interruption insurance from insurers not authorized to conduct business in New York. This broadens the market and gives businesses more options, especially if they struggle to find adequate coverage from in-state insurers.
Financial Safeguards
To ensure that insurers can meet their obligations, the law imposes new financial requirements. Insurers must maintain minimum capital and surplus levels, providing businesses with confidence that their claims will be honored.
These changes represent a significant shift in how New York businesses can protect themselves from disruptions. By allowing standalone policies, businesses now have the flexibility to choose the coverage that best suits their needs, ensuring they are better prepared for a range of potential interruptions.
Next, we’ll explore the benefits of these standalone policies and how they can be further customized to provide even more robust protection for your business.
Benefits of Standalone Business Interruption Insurance
Standalone business interruption insurance NY offers several advantages that can significantly improve your business’s resilience against unexpected disruptions. Let’s explore how these policies provide customized protection, access to diverse insurance markets, and ensure financial security.
Customized Protection
One of the main benefits of standalone business interruption insurance is the ability to tailor coverage specifically to your business needs. Unlike bundled policies that might include unnecessary coverages, standalone options allow businesses to choose exactly what they need. This means you can select coverage for:
-
Government-Mandated Closures: If your business is forced to close due to a government order, your custom policy can cover the income loss. This is especially relevant after the COVID-19 pandemic highlighted gaps in traditional coverage.
-
Acts of Violence and Cyberattacks: Businesses can opt for coverage against interruptions from violence or cyber incidents, offering peace of mind in uncertain times.
-
Pandemics and Natural Disasters: Customize your policy to include coverage for pandemics or natural disasters, ensuring your business is prepared for a wide range of potential threats.
Access to Excess Line Insurers
The new law also allows businesses to access excess line insurers. These insurers are not authorized to transact business in New York but can be accessed through licensed brokers. This change expands your options, especially if you’re struggling to find suitable coverage from traditional in-state insurers. More choices mean you can find a policy that offers the best terms and pricing for your specific needs.
Financial Requirements for Insurers
To safeguard your interests, insurers offering standalone business interruption insurance must meet strict financial requirements. They are required to maintain minimum capital and surplus levels. This ensures they have the financial reserves necessary to pay out claims, giving you confidence that your coverage will be effective when you need it most.
These benefits make standalone business interruption insurance a smart choice for businesses looking to protect themselves against a variety of disruptions. By customizing your coverage and having access to a broader range of insurers, you can ensure your business is well-prepared for whatever challenges may arise.
Next, we’ll discuss how to calculate and manage business interruption claims effectively, ensuring you receive the support you need during a disruption.
Calculating and Managing Business Interruption Claims
When your business faces an unexpected disruption, filing a business interruption insurance claim can be crucial to recovering lost income. But how do you ensure you’re getting the most out of your claim? Let’s break down the process into three key steps: financial analysis, claim documentation, and understanding lost profits.
Financial Analysis
First, you need a clear picture of the financial impact of the disruption. This means analyzing your business’s financial records to determine how much income was lost. You should look at:
- Historical Financial Data: Compare your current financial performance to previous periods to estimate the income you would have earned if the disruption hadn’t occurred.
- Sales Records: Analyze sales trends before, during, and after the event to quantify the loss.
- Expense Tracking: Keep a record of any extra expenses incurred due to the disruption, such as temporary relocation costs or additional payroll.
A thorough financial analysis helps in accurately assessing the financial impact, which is vital for calculating your claim amount.
Claim Documentation
Once you have a financial analysis, the next step is to document everything carefully. Proper documentation can make or break your claim. Here’s what you need:
- Financial Statements: Include income statements, balance sheets, and cash flow statements.
- Evidence of Disruption: Gather any official notices, such as government shutdown orders or police reports, that prove your business was impacted.
- Invoices and Receipts: Document all extra costs incurred during the disruption.
Having comprehensive documentation supports your claim and provides a solid foundation for negotiations with your insurer.
Understanding Lost Profits
Calculating lost profits can be complex, but it’s essential for a successful claim. Here’s how to approach it:
- Estimate Lost Revenue: Use your financial analysis to estimate the revenue you lost during the disruption period.
- Consider Ongoing Costs: Factor in fixed costs like rent and utilities that you still had to pay, even if your business wasn’t operating.
- Adjust for Mitigation: If you took steps to reduce losses, such as moving operations online, adjust your calculations to reflect these efforts.
By understanding lost profits, you can ensure your claim accurately reflects the true financial impact of the disruption on your business.
In summary, managing a business interruption claim requires a structured approach: perform a detailed financial analysis, compile thorough documentation, and accurately calculate lost profits. With these steps, you can maximize your claim and help your business recover more effectively.
Up next, we’ll address some frequently asked questions about business interruption insurance in New York, helping you understand what is covered and whether it’s worth the investment.
Frequently Asked Questions about Business Interruption Insurance NY
What is covered in business interruption insurance?
Business interruption insurance is designed to cover the financial gap when your business can’t operate due to a covered event. Here’s what it typically includes:
-
Lost Net Income: This is the income you would have earned if your business hadn’t been interrupted. It’s calculated using your historical financial data and sales trends.
-
Employee Wages: Even if your business is temporarily closed, you still need to pay your employees. This insurance helps cover those wages to keep your staff on board.
-
Taxes: Your tax obligations don’t stop during a business interruption. This coverage ensures you can meet those responsibilities without dipping into reserves.
Is business interruption insurance worth it?
Yes, business interruption insurance can be crucial for many businesses, especially when facing temporary closures or unexpected events like property damage. Here are a few reasons why it’s worth considering:
-
Temporary Closure: Whether due to a natural disaster, cyberattack, or government order, a temporary closure can halt your revenue stream. Insurance helps bridge that gap.
-
Property Damage: If your business premises are damaged, this insurance can help cover the costs of repairs and lost income during the downtime.
Having this coverage can mean the difference between a quick recovery and a prolonged financial struggle.
How much does business interruption insurance cost?
The cost of business interruption insurance varies based on several factors:
-
BOP Package: Many small businesses opt for a Business Owner’s Policy (BOP), which bundles business interruption insurance with other coverages like property and liability insurance, often at a reduced rate.
-
Small Businesses: For small businesses, the cost is influenced by the size of the business, industry type, and location. A small retail shop might pay less than a larger manufacturing facility due to differing risks.
To get an accurate estimate, it’s best to consult with an insurance agent who can tailor a package to your specific needs.
Business interruption insurance provides essential protection that can help your business stay afloat during challenging times. Next, we’ll explore how Mitchell-Joseph Insurance Agency can offer personalized service to meet your unique coverage needs.
Conclusion
At Mitchell-Joseph Insurance Agency, we understand that your business is more than just a source of income—it’s your livelihood. That’s why we offer custom coverage options that are custom to fit the unique needs of your business. Our experienced team, with over 200 years of combined expertise, is dedicated to providing you with the best personalized service and competitive quotes from 24 different insurance companies.
Our goal is to ensure that you have the right protection in place, especially when it comes to Business Interruption Insurance NY. With the recent legislative changes allowing for standalone policies, we can help you steer these new options to safeguard your business against unforeseen interruptions.
Whether you’re concerned about natural disasters, cyberattacks, or government-mandated closures, our team is here to guide you through the process of selecting and managing your business interruption insurance. We pride ourselves on our ability to offer personalized solutions that address the specific risks your business faces, ensuring you can maintain operations and recover swiftly from any disruption.
Don’t leave your business’s future to chance. Contact us at Mitchell-Joseph Insurance Agency to discuss how we can help protect your investment with custom insurance solutions.

