

Why Professional Photographers Need Liability Protection
The best liability insurance for photographers protects your creative business from costly lawsuits and unexpected damages. Whether you’re capturing wedding moments or running a portrait studio, your business faces unique risks every day. A client could trip over equipment, a memory card could fail, or a data breach could expose client information.
These aren’t just hypotheticals. One photographer faced a $16,000 lawsuit when a guest tripped over equipment, while another missed a major gig for lacking the required insurance. Standard homeowner’s policies won’t cover these professional risks. You need specialized protection for your craft.
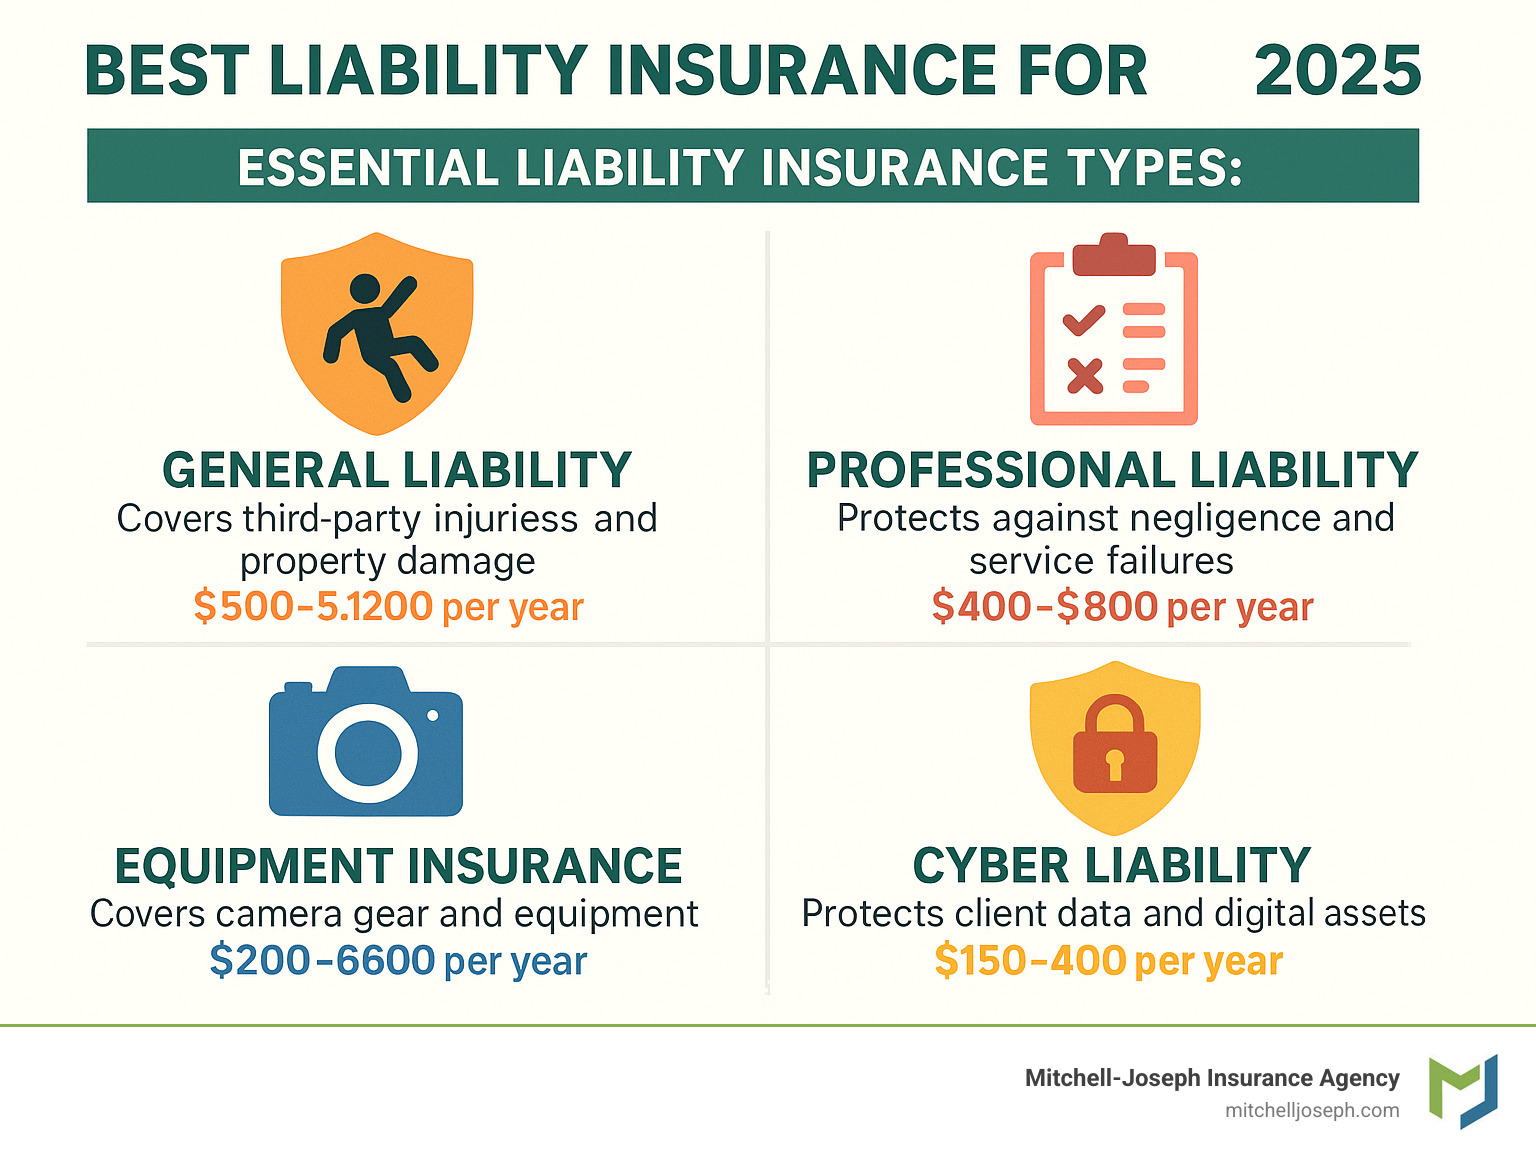
Essential Liability Insurance Types:
- General Liability: Covers third-party injuries and property damage.
- Professional Liability (E&O): Protects against negligence claims and service failures.
- Equipment Insurance: Covers camera gear theft and damage.
- Cyber Liability: Protects client data and digital assets.
I’m Jeffrey Joseph of Mitchell-Joseph Insurance Agency. For over two decades, I’ve helped photographers in the Finger Lakes region find the right coverage. Proper insurance allows you to focus on your art without worrying about financial risks.
Finding the Best Liability Insurance for Photographers: A Complete Guide
Choosing insurance is like setting up the perfect shot—you need the right settings for your specific situation. Understanding what each type of coverage protects is crucial for finding the best liability insurance for photographers.
General vs. Professional Liability: What’s the Difference?
These two coverages work together like a camera and lens—you need both for complete protection, but they serve different purposes.
General Liability Insurance (CGL)
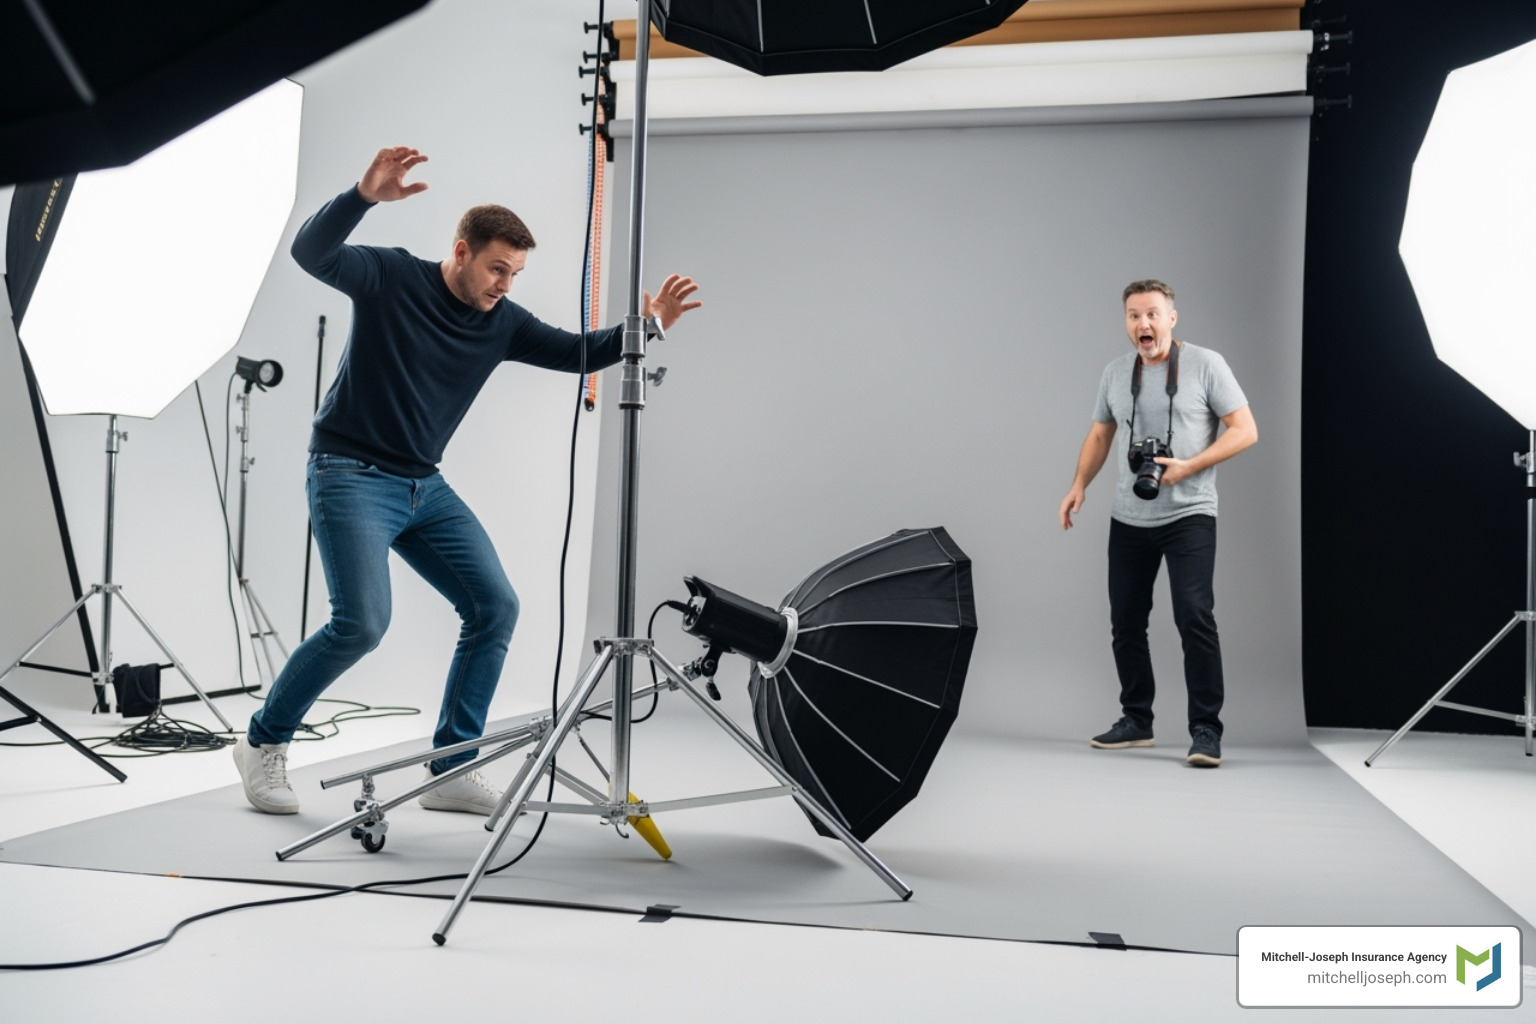
Think of this as your “slip-and-fall” coverage. It protects you when your business causes bodily injury or property damage to others. For example, if a wedding guest trips over your lighting cable and breaks their wrist, or your light stand damages a client’s TV, general liability covers medical bills, repair costs, and legal fees.
Real-world claims include a toddler knocking over a tripod and scratching hardwood floors or a light setup damaging antique wall paneling. Third-party bodily injury and property damage claims can be costly. Most venues require photographers to carry general liability, so you’ll likely need it to book jobs.
Professional Liability Insurance (E&O)
This coverage, also called Errors & Omissions (E&O) insurance, protects you from claims related to your actual photography services. It’s your lifeline when clients allege you made professional mistakes or failed to deliver as promised.
This covers scenarios like a corrupted memory card that loses wedding photos, missing a crucial shot the client requested, or general client dissatisfaction with the final portraits. Lost photos are a photographer’s worst nightmare, and lawsuits over failure to deliver services or other errors & omissions can cost thousands to resolve.
The key difference is simple: General liability handles physical accidents, while professional liability covers problems with your services. You need both.
For more details, see our guides on General Liability Insurance for Businesses and Professional Liability Insurance.
Essential Add-Ons: Equipment and Cyber Liability Coverage
Beyond core liability, photographers face two other major risks: equipment loss and cyber threats.
Equipment Insurance
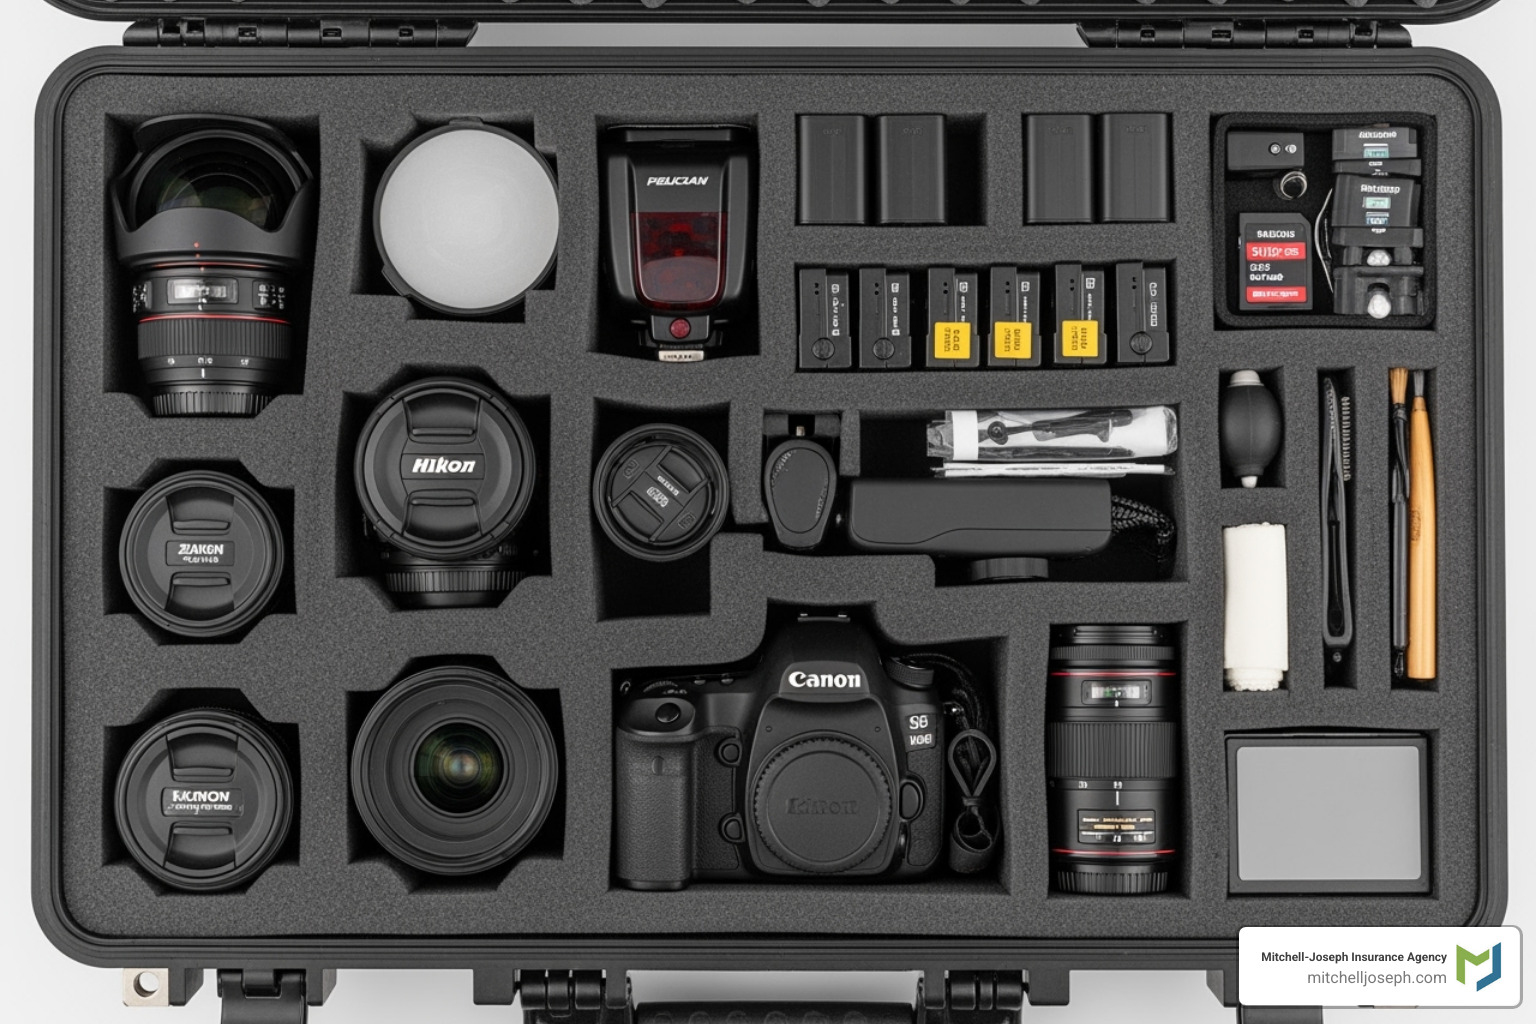
Your cameras, lenses, and lighting are your livelihood. Equipment insurance (or gear protection) covers the thousands of dollars invested in your gear against theft, accidental damage, fire, and other disasters. One photographer I know lost a $7,500 kit when it fell off a ferry; without insurance, it would have been a business-ending loss. Instead, their policy covered the replacement, and they were back to shooting in days.
Cyber Liability Insurance
Photographers handle sensitive client data, from personal info to private photos. Cyber liability insurance protects you if this data is compromised. Data breaches and ransomware attacks can be devastating, and this coverage helps pay for recovery costs, legal notifications, and client data protection measures.
Drone Photography Risks
Using drones for aerial photography introduces unique risks, as they can crash, cause injury, or damage property. Drone photography requires specialized liability coverage. You’ll need to comply with FAA Part 107 regulations and carry appropriate insurance, which can often be added to an existing policy. For more guidance, visit our page on Business Insurance for Photographers.
How to Choose the Best Liability Insurance for Photographers
Selecting the right insurance requires careful consideration of your business needs.
Policy Limits and Deductibles
Policy limits are the maximum your insurer will pay for a claim. Most photographers choose $1,000,000 or $2,000,000 in coverage. Deductibles are what you pay out-of-pocket before insurance kicks in. A higher deductible means lower premiums, but ensure you can afford it in an emergency.
Bundling Policies with a Business Owner’s Policy (BOP)
A Business Owner’s Policy (BOP) is a smart move for most photographers. It bundles general liability, commercial property (including equipment), and business interruption insurance into one package, often at a discount.
Niche-Specific Needs
Your specialty matters. Wedding photographers face high professional liability risks due to the irreplaceable nature of the event. Event photographers have higher general liability exposure. Studio photographers need robust property coverage. If you’re a freelancer, ensure your coverage is portable.
International Travel Coverage
For destination work, confirm your policy covers you abroad. Some policies require special endorsements for international assignments.
As an independent agency, we compare options from 24 insurers to customize a policy for you. The importance of business insurance for creative professionals cannot be overstated.
What is the Cost of the Best Liability Insurance for Photographers?
Insurance costs depend on factors like your business revenue, location, number of employees, and claims history. The type of photography you do also influences your risk profile and pricing.
Typical Cost Range
Based on industry data, here’s what you might expect:
- General Liability Insurance often costs around $18 per month.
- Professional Liability Insurance can start under $500 per year.
- A Business Owner’s Policy (BOP) that bundles coverages typically runs about $42 per month.
Many photographers pay between $650 to $1,000 annually for combined general and professional liability. You can often choose between monthly vs. annual premiums and may qualify for discounts through professional associations or by bundling policies.
| Coverage Type | Average Annual Cost | Typical Limits |
|---|---|---|
| General Liability | $216 – $504 | $1M – $2M |
| Professional Liability | $400 – $800 | $1M – $2M |
| Business Owner’s Policy | $504 – $1,000 | $1M + Property |
| Equipment Insurance | $200 – $600 | Varies by Value |
| Cyber Liability | $150 – $400 | Varies by Need |
These are average ranges. The best liability insurance for photographers is the policy that properly protects your unique business at a price you can afford.
Protect Your Passion and Your Business
Every time you pick up your camera, you’re running a business that faces real risks. You’ve invested years perfecting your craft and thousands in equipment; one accident or lawsuit could threaten it all. The best liability insurance for photographers isn’t an expense—it’s an investment in your creative freedom and peace of mind.
Proper coverage allows you to say yes to bigger clients and exciting venues without hesitation. A solid plan should include:
- General Liability for accidents and property damage.
- Professional Liability for service errors or dissatisfied clients.
- Equipment Insurance to protect your valuable gear.
- Cyber Liability to safeguard client data.
Finding the right policy means matching coverage to your specific work, whether you’re a wedding, event, or studio photographer. At Mitchell-Joseph Insurance Agency, we specialize in protecting creative professionals. As an independent agency, we work with 24 different insurers to build a policy that fits your unique risks and budget, from Rochester to the Finger Lakes.
When you know you’re covered, you can focus on what you do best: creating beautiful images. Stop worrying about worst-case scenarios and start shooting with confidence.
Ready to protect your passion and your business? We’re here to help.
Get a personalized quote for your photography business today!

