

Why Your Business Vehicle Needs More Than Personal Coverage
Business auto insurance quotes are essential for any company using vehicles for operations, as personal auto policies typically exclude coverage for business use. Here’s what you need to know about securing commercial auto coverage:
Quick Guide to Business Auto Insurance Quotes:
- Who needs it: Contractors, delivery services, real estate agents, and any business using vehicles for work
- Average costs: 44% of small businesses pay under $1,500 annually, 34% pay $1,500-$3,000, and 22% pay over $3,000
- Key coverage types: Liability, collision, comprehensive, and uninsured motorist protection
- Information needed: Business details, driver records, vehicle VINs, and desired coverage limits
- Money-saving tips: Bundle policies, maintain clean driving records, and work with independent agents
The stakes are high when it comes to business vehicle protection. Commercial auto insurance policies typically offer higher liability limits than personal policies due to the increased risk exposure businesses face. Unlike personal auto insurance, commercial policies cover vehicles used for business purposes 24/7. This means your delivery van is covered whether it’s making deliveries or parked overnight.
Nearly every state mandates commercial auto insurance for vehicles used in business operations. Personal auto policies won’t cover business-related incidents, leaving you exposed to potentially catastrophic liability.
As Jeffrey Joseph from Mitchell-Joseph Insurance Agency, I’ve helped countless upstate New York business owners steer the complexities of commercial auto coverage since 1999. My experience securing business auto insurance quotes for diverse industries has shown me that the right coverage strategy can save businesses thousands while providing essential protection.
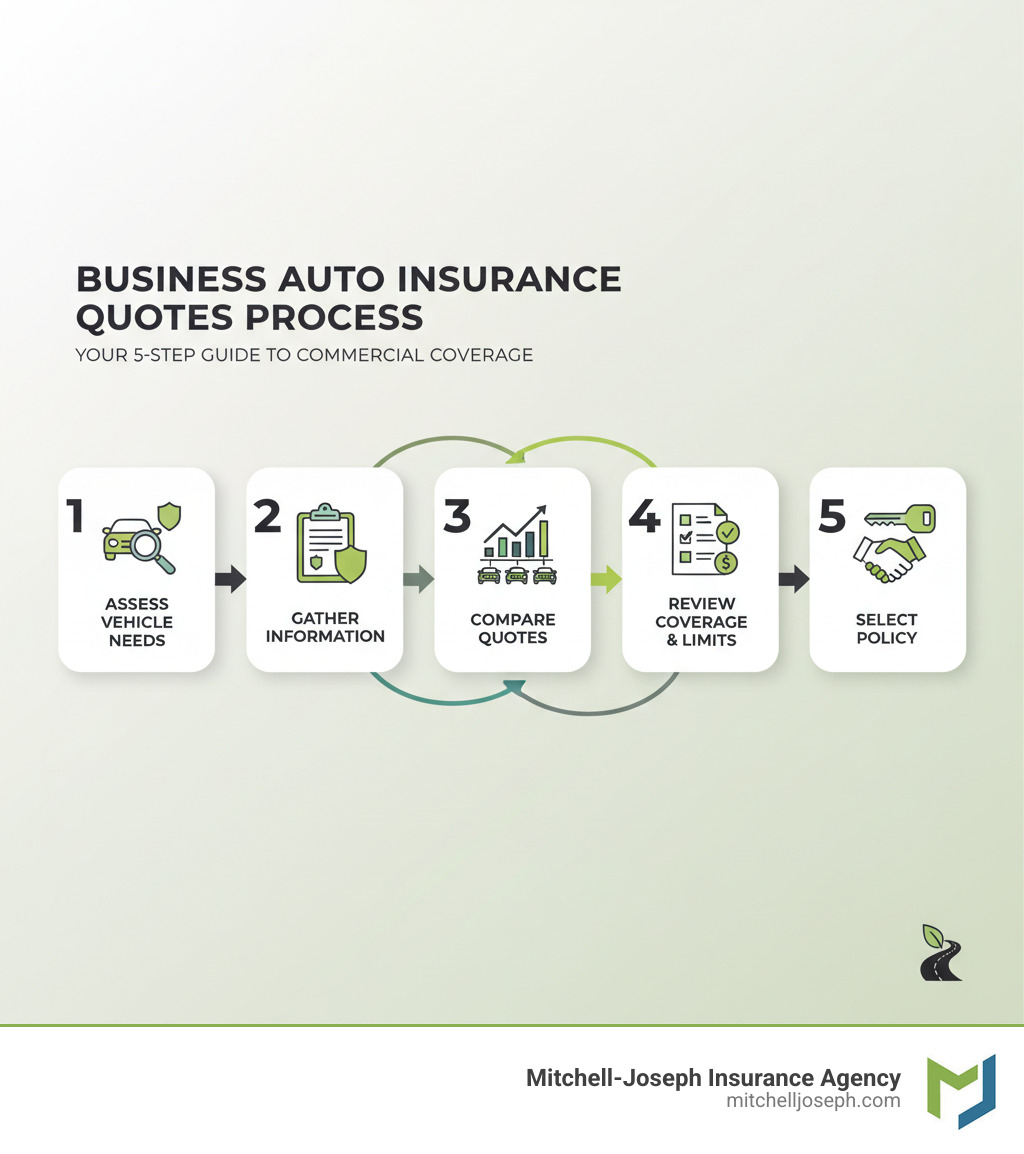
Commercial auto insurance is a specialized policy designed to protect your business vehicles, employees, and assets from the unique risks of commercial operations. It’s a critical shield for your financial stability.
What is Commercial Auto Insurance?
Commercial auto insurance is a policy that covers vehicles a company uses to conduct business. It’s designed for the demands of the business world, stepping in to cover damages, injuries, and other liabilities from accidents involving your company’s vehicles. Whether it’s a sedan for client meetings, a van for deliveries, or a heavy-duty truck, if it’s used for work, it needs commercial coverage.
Importance of Business Insurance
This specialized coverage is crucial for two main reasons: financial protection and legal compliance.
Financial Protection
An accident in a business vehicle can have substantial financial consequences. Commercial auto insurance protects your assets and reputation by covering:
- Property damage: Repairs to your vehicle or other property.
- Driver injury: Medical expenses for your employees or others injured.
- Legal fees: Costs associated with lawsuits.
Without it, your business would be directly responsible for these costs, which could be devastating.
Legal Compliance
Nearly every state legally requires commercial auto insurance for business vehicles, mandating specific liability coverage. Non-compliance can lead to hefty fines, license suspension, or worse. We help our clients meet these crucial legal requirements, keeping their operations compliant.
Personal Policy Gaps
A common, costly mistake is assuming personal auto insurance covers business use. Personal policies almost always have “business use” exclusions, meaning a claim during a work-related task will likely be denied. Commercial auto insurance is designed for these scenarios, offering the higher coverage limits needed to protect any business, from a sole proprietor to a large corporation.
We at Mitchell-Joseph Insurance Agency are here to simplify the process. Learn more about how we protect your wheeled assets on our page about Auto Insurance for Business Owners.
Here’s a quick comparison to highlight the key differences:
| Feature | Personal Auto Insurance | Commercial Auto Insurance |
|---|---|---|
| Coverage Limits | Lower, designed for individual risk | Higher, designed for greater business liability and risk |
| Covered Uses | Personal commuting, leisure, family errands | Business operations, deliveries, client visits, hauling goods |
| Who is Covered | Named drivers and household members for personal use | Employees driving for business, potentially unlisted drivers |
| Cost | Generally lower premiums | Generally higher premiums due to increased risk and liability |
Decoding Your Commercial Auto Policy and Its Cost
Let me break down what you’re actually paying for when you get business auto insurance quotes. A commercial auto policy is a collection of protections working together to keep your business safe.
What’s Covered? A Breakdown of Policy Options
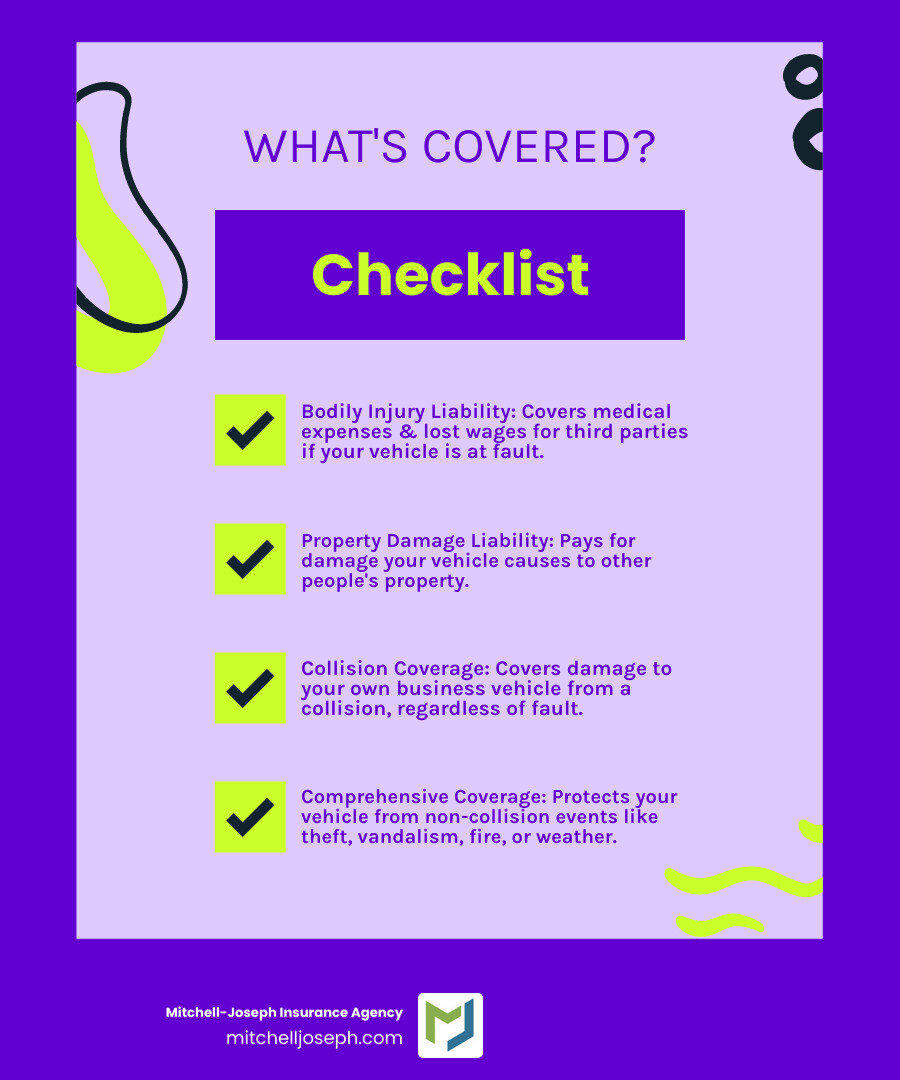
Here’s a look at the core components of a commercial auto policy:
- Bodily injury liability: Covers medical bills, lost wages, and legal costs if your business vehicle injures someone in an accident.
- Property damage liability: Pays for repairs to another person’s vehicle or property if your business vehicle is at fault.
- Collision coverage: Pays to repair your business vehicle after a collision, regardless of fault. It’s crucial for protecting valuable or specialized vehicles.
- Comprehensive coverage: Covers damage to your vehicle from non-collision events like theft, vandalism, storms, or hitting an animal.
- Uninsured/underinsured motorist coverage: Protects you and your employees if you’re hit by a driver with little or no insurance.
- Medical payments coverage: Pays for immediate medical expenses for you and your passengers, regardless of who is at fault.
- Hired and non-owned auto coverage: Provides liability protection when employees drive rented vehicles or their personal cars for business errands.
For more details on all your coverage options, visit our Insurance Coverage page.
Key Factors That Influence Your Premium
When we prepare business auto insurance quotes, several factors determine your cost:
- Vehicle type: Heavy-duty trucks and specialized vans cost more to insure than standard sedans due to higher repair costs and risk.
- Driving records: The history of your drivers is a major factor. Clean records lower your rates, while accidents and violations increase them.
- Industry risk: A business with vehicles on the road all day (like delivery or contracting) will have higher premiums than one where driving is infrequent.
- Business location: Rates are higher in urban areas with more traffic and in regions prone to severe weather, like the icy winters we see in upstate New York. Check out our Auto Insurance Rochester page for local insights.
- Coverage limits and deductibles: Higher limits increase your premium but provide more protection. A higher deductible (your out-of-pocket cost) will lower your premium.
- Fleet size and number of drivers: A larger fleet or more drivers naturally increases your exposure and your premium.
- Claims history: A history of frequent claims will lead to higher rates, while a clean record can earn you discounts.
Some good news about costs: 44% of small businesses pay under $1,500 annually for their commercial auto insurance, while 34% pay between $1,500 and $3,000. Only 22% pay over $3,000, typically businesses with larger fleets or higher-risk operations. Your actual cost depends entirely on your specific situation, which is why we create custom quotes through our Business Insurance Policy process.
Common Exclusions and What to Watch For
Knowing what’s not covered helps you avoid surprises. Key exclusions include:
- Tools and equipment: Your auto policy doesn’t cover items inside your vehicle. For that, you need inland marine coverage, often part of a Business Owners Policy.
- Unauthorized personal use: While some personal use may be permitted, unauthorized trips may not be covered.
- Intentional damage or illegal acts: Insurance covers accidents, not deliberate damage or criminal behavior.
- Racing or off-roading: Using a commercial vehicle for these activities is not covered.
- Unlisted drivers: An accident caused by a regular driver who isn’t listed on your policy could lead to a denied claim.
- Personal rental use: Your commercial policy won’t cover a vehicle you rent for personal use, like a vacation.
How to Get the Best Business Auto Insurance Quotes
Finding the best business auto insurance quotes is about finding the sweet spot where comprehensive coverage meets your budget. That’s where we love to help our clients succeed.
Who Needs Coverage and What Are the Legal Requirements?
If you use a vehicle for any business purpose, you almost certainly need commercial auto insurance. The need is broad and includes:
- Contractors and tradespeople (electricians, plumbers, landscapers) who haul tools and equipment. We specialize in this area with our Business Insurance for Contractors program.
- Delivery services of any kind, from food to documents.
- Real estate agents who drive clients to showings.
- Mobile service providers like pet groomers, cleaners, or caterers.
- Any business that transports employees, owns a vehicle, or has employees using personal cars for work errands (which requires hired and non-owned auto coverage).
Legally, nearly every state, including New York, mandates commercial auto insurance for business vehicles. Often, client contracts will require even higher liability limits than the state minimums. We can help you steer these contractual obligations and how they relate to your NY General liability insurance needs.
What Information Do I Need for Business Auto Insurance Quotes?
To get the most accurate and competitive business auto insurance quotes, it helps to have the following information ready:
- Business Details: Company name, address, business structure (e.g., LLC, sole proprietorship), and industry.
- Driver Information: Full name, date of birth, and driver’s license number for every potential driver.
- Vehicle Information: VIN, year, make, model, and gross vehicle weight for each vehicle. Also, describe its primary use, estimated annual mileage, and where it’s typically parked.
- Coverage and History: Your desired coverage limits, any recent claims history, and details of your current or prior insurance policy.
Our experienced team at Mitchell-Joseph Insurance Agency has streamlined this process to get you the competitive Business Insurance Quotes NY businesses trust.
Strategies for Lowering Your Business Auto Insurance Quotes
Saving money without sacrificing protection is the goal. Here are proven strategies that deliver real savings:
- Bundle your policies: Combining your commercial auto with other policies like general liability or a Business Owner’s Policy is one of the easiest ways to get a significant discount.
- Maintain clean driving records: A history of safe driving is key to low premiums. Implementing a formal driver safety program can also earn you additional discounts.
- Choose a higher deductible: If your cash flow allows, increasing your deductible (e.g., from $500 to $1,000) will lower your annual premium.
- Pay your premium annually: Paying in full for the year can help you avoid installment fees and may qualify you for a pay-in-full discount.
- Work with an independent agent: An independent agency like ours shops your policy with multiple carriers (we work with 24) to find the best combination of coverage and price.
- Improve vehicle security: Parking in secure, well-lit lots and installing anti-theft devices can reduce your rates.
When evaluating carriers, we encourage clients to check insurance company ratings with the Better Business Bureau. Strong financial ratings and good customer service matter. The bottom line is that with the right strategy and an experienced agent, you can secure comprehensive protection at a competitive rate.
Ready to see what we can do for your business? Get your Business Auto Insurance Quotes today and let’s start protecting what you’ve worked so hard to build.

