

Understanding the Real Cost of Protecting Your Rental
Average rental insurance costs in 2026 typically range from $12 to $30 per month (or $148 to $360 per year), depending on your location and coverage. Here’s a quick look:
- National Average: $24/month or $288/year for standard coverage
- Ontario Average: $197/year (about $16/month)
- Alberta Average: $218/year (about $18/month)
- Coverage Range: Most policies include $20,000-$40,000 in personal property coverage and $100,000-$300,000 in liability protection
- Cheapest States/Provinces: As low as $13/month in places like North Dakota, Wyoming, and Montana
- Most Expensive: Up to $36/month in Louisiana or $46/month in cities like Detroit
While not always top of mind, tenant insurance is crucial. Consider that replacing the contents of a one-bedroom apartment averages $20,000, and a single hotel night during displacement can cost $200. Tenant insurance protects your belongings, covers liability if someone is hurt in your rental, and pays for temporary housing after a disaster.
Your landlord’s insurance only covers the building, not your personal items. Renters insurance protects your furniture, electronics, and clothes—even when you’re traveling. It also shields you from lawsuits if a guest is injured or you accidentally damage the property.
I’m Jeffrey Joseph. Since 1999 at Mitchell-Joseph Insurance Agency, I’ve helped families in the Finger Lakes region find the right protection. Understanding average rental insurance costs is the first step to securing your belongings without overpaying. Whether you’re in Honeoye Falls, Naples, or anywhere in upstate New York, knowing what drives these costs is key to getting the right coverage at the right price.
Average rental insurance costs terms to learn:
Decoding the Average Rental Insurance Costs
Understanding the Average Rental Insurance Costs in 2026
The average rental insurance costs depend on several factors. The U.S. national average is about $24 per month ($288 annually) for a policy with $40,000 in personal property coverage, a $1,000 deductible, and $300,000 in liability protection. However, your specific cost will vary.
Location is a major factor. In New York, the average is around $15/month but can be higher in NYC. States prone to natural disasters, like Louisiana, have higher rates (up to $36/month), while lower-risk states like Wyoming and North Dakota can be as low as $13/month.
The key takeaway is that while the cost is generally affordable, it’s not a one-size-fits-all number.
Here’s how average annual premiums can look based on different personal property coverage levels across the U.S.:
| Personal Property Coverage | Average Annual Premium | Average Monthly Premium |
|---|---|---|
| $15,000 | $173 | $14 |
| $30,000 | $227 | $19 |
| $50,000 | $305 | $25 |
Note: These figures are based on a typical policy with $100,000 in liability coverage and a $2,000 deductible.
As the table shows, increasing your coverage is a cost-effective way to get comprehensive protection. For more details, visit our guide on Renters Insurance.
Key Factors That Influence Your Insurance Premium
To understand average rental insurance costs, you need to know the variables insurers use to calculate your premium. Here are the primary factors:
- Location: Areas with higher crime rates, disaster risks (like severe weather in New York), or older buildings can have higher premiums. A renter in Honeoye Falls might pay a different rate than one in Rochester.
- Coverage Limits: The more coverage you choose, the higher your premium. However, the increase is often small for a significant boost in protection.
- Deductible Amount: This is what you pay out-of-pocket before insurance pays. A higher deductible usually means a lower premium. Choose an amount you can comfortably afford.
- Credit History: In most states, including New York, a better credit score can lead to lower premiums.
- Claims History: A history of filing claims, especially recent ones, can increase your rates.
- Property Type and Age: The type of home (apartment, house) and its age affect costs. Newer buildings may have lower rates.
- Pet Ownership: Owning certain dog breeds can increase your premium due to higher liability risks.
- Safety and Security Features: Smoke detectors, burglar alarms, and deadbolt locks can qualify you for discounts.
These factors create your unique insurance profile. At Mitchell-Joseph Insurance Agency, we help you steer these elements to find competitive rates from our 24 partner companies. Learn more in our article on the Average Cost of Renters Insurance.
What’s Covered vs. What’s Not?
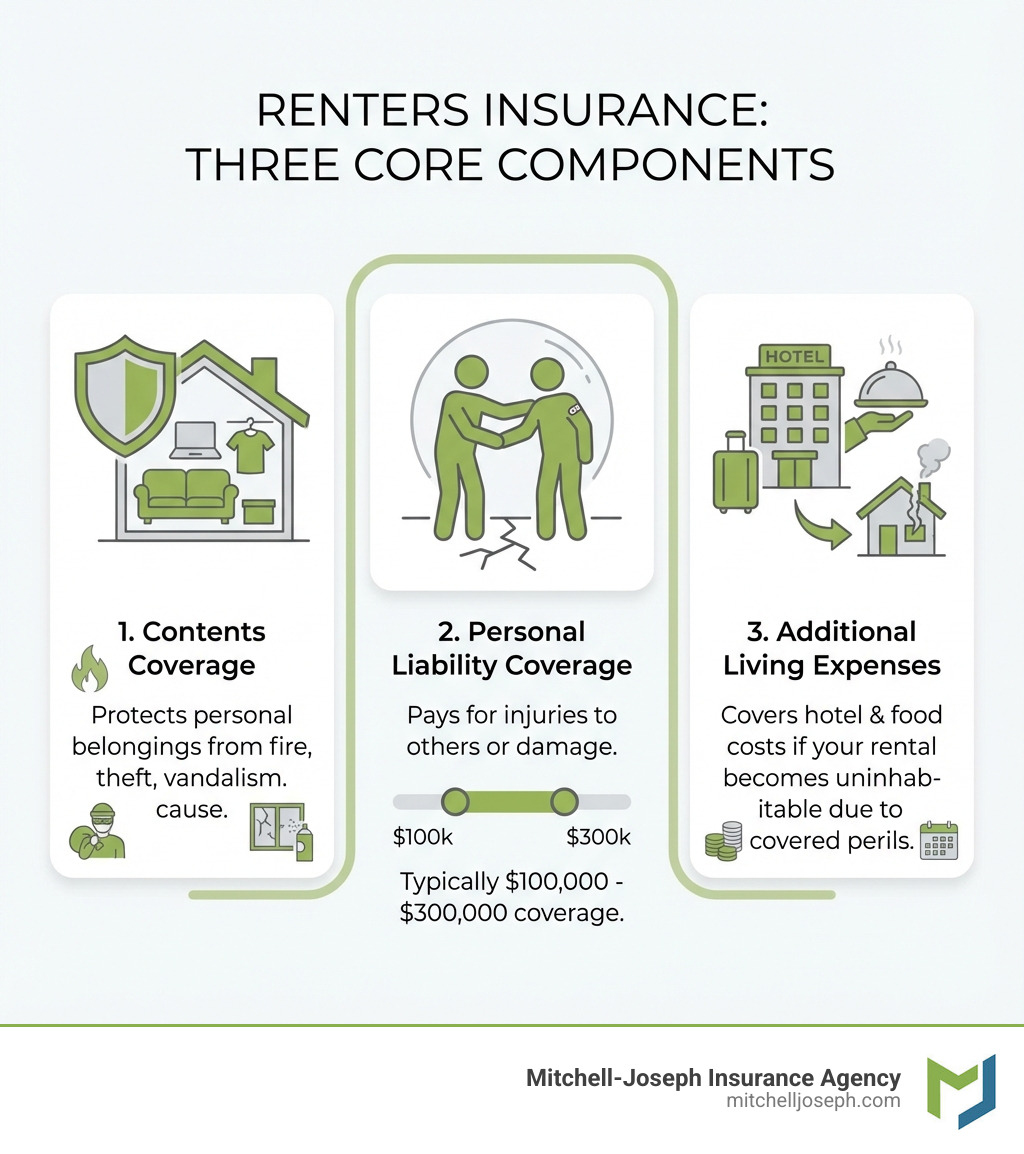
It’s crucial to understand what your tenant insurance policy covers. Typically, it provides three core protections:
- Personal Property Coverage: This protects your belongings (furniture, electronics, clothing) from perils like fire, theft, and certain types of water damage. Your property is often covered even outside your home.
- Personal Liability Coverage: This is critical. It protects you financially if you’re legally responsible for injuring someone or damaging their property. Most policies offer $100,000 to $300,000, but we often advise higher limits.
- Additional Living Expenses (ALE): If a covered event makes your rental uninhabitable, ALE helps pay for temporary housing, food, and other necessary expenses.
Standard policies have important exclusions you should know:
- Building Structure Damage: Your landlord’s insurance covers the building itself.
- Floods: Damage from natural floods is excluded. Separate flood insurance may be available. See Water Backup Insurance vs Flood Insurance.
- Earthquakes: Excluded, but can often be added as an endorsement.
- Pest Infestations: Issues like bed bugs or rodents are considered maintenance and are not covered.
- Maintenance Issues and Wear and Tear: Damage from lack of maintenance or normal aging is not covered.
- Intentional Damage or Criminal Acts: Damage you cause intentionally or during a criminal act is not covered.
Optional Coverages
You can often add endorsements for greater protection:
- Sewer Backup: Covers damage from water backing up through sewers or drains. Learn more: Does Tenant Insurance Cover Water Damage.
- Overland Water: Covers damage from fresh water entering your home from heavy rain or melting snow.
- Identity Theft: Reimburses costs associated with recovering from identity theft.
- Personal Valuables Floater: Provides extra coverage for high-value items like jewelry or art.
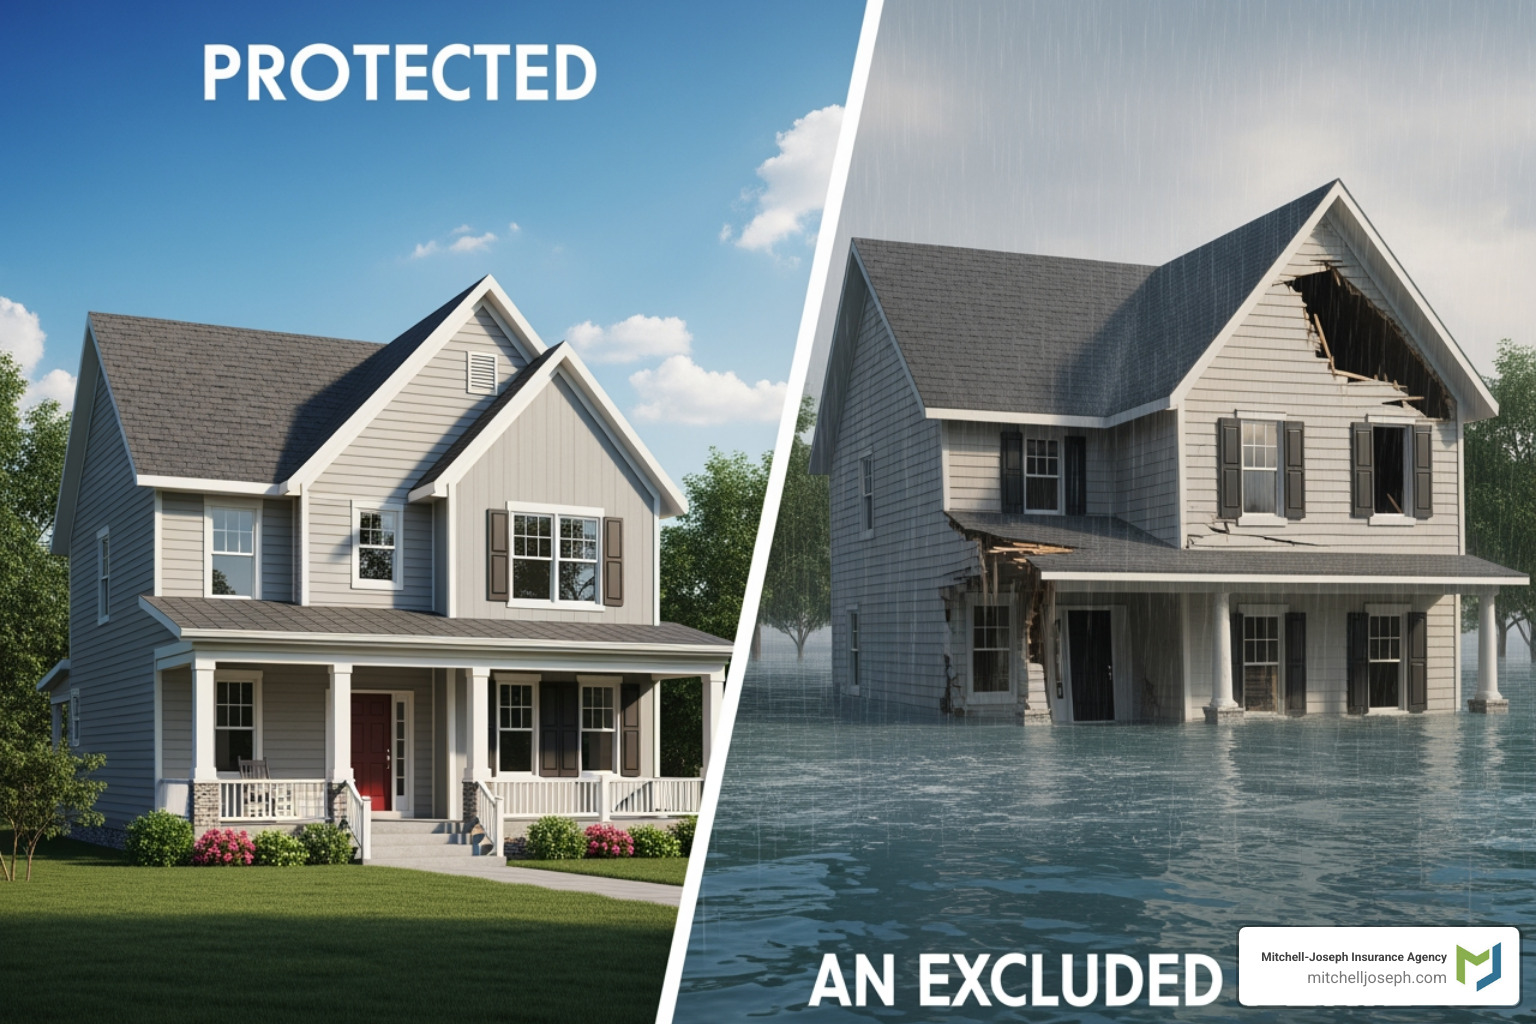
Understanding these distinctions is key to being prepared. At Mitchell-Joseph Insurance Agency, we can walk you through your options in Honeoye Falls, Rochester, and our other service areas to tailor a policy for your needs.
Securing Affordable Coverage and Making Smart Choices
How to Get Cheaper Tenant Insurance Rates
While average rental insurance costs are affordable, you can lower your premium further without sacrificing essential coverage. Here’s how:
- Shop Around and Compare Quotes: Different insurers have different pricing. We simplify this by comparing quotes from 24 companies to find you the best rate.
- Bundle Policies: Bundling your tenant and auto insurance can lead to significant savings, sometimes over $700 annually.
- Increase Your Deductible: A higher deductible lowers your premium. Increasing it from $500 to $1,000 can cut costs by up to 25%. Just ensure you can afford the out-of-pocket expense.
- Install Safety and Security Devices: Smoke detectors, fire extinguishers, and monitored security systems can earn you discounts.
- Maintain a Good Credit Score: In New York, a good credit history often leads to lower insurance rates.
- Avoid Small Claims: Filing frequent small claims can increase your premiums. For minor damages near your deductible, it may be cheaper to pay out-of-pocket.
- Pay Annually: Paying your annual premium upfront can sometimes earn you a discount over monthly payments.
- Ask for Other Discounts: Inquire about discounts for being claim-free, using paperless billing, setting up auto-pay, or being a retired renter.
Using these strategies can lower your average rental insurance costs. Many of these principles also apply to homeowners, as seen in our Homeowners Insurance Discounts guide.
Getting a Quote and Customizing Your Policy
Getting a tenant insurance quote is straightforward. We’ll ask for some key information to tailor a policy to your needs and budget:
- Personal Details: Your name, date of birth, and contact information.
- Property Address: The full address of your rental unit.
- Type of Dwelling: Whether it’s an apartment, house, townhouse, etc.
- Year the Building was Built: Newer buildings can mean lower rates.
- Combined Value of Your Possessions: An estimate of the cost to replace everything you own. A room-by-room inventory helps. The average for a one-bedroom is $20,000.
- Who You Live With: Roommates usually need their own policy or must be explicitly added to yours, which may increase the rate.
- Claims History: Details of any past insurance claims.
- Desired Coverage Limits and Deductible: Your preferences for property and liability coverage.
Recommended Liability Coverage Limits
We often recommend at least $1 million in liability coverage. Upgrading from $100,000 to $300,000 might only add about $1 per month to your premium, offering substantial protection for a minimal cost.
Replacement Cost vs. Actual Cash Value
Another important choice is how your property is valued after a claim:
- Actual Cash Value (ACV): Pays the depreciated value of your item. A 5-year-old laptop is valued at what it’s worth today, not its original price.
- Replacement Cost (RCV): Pays to replace your item with a brand-new one of similar quality. Though it may slightly increase your premium, we usually recommend RCV so you can fully replace what you’ve lost.
At Mitchell-Joseph Insurance Agency, we guide you through these choices to customize your policy. We can answer your questions whether you’re in Honeoye Falls, Naples, or Rochester, NY. Find more answers in our Renters Insurance FAQs.
The Real Cost of Skipping Insurance and Finding Help
Skipping tenant insurance to save a few dollars a month can lead to a crippling financial burden if a disaster strikes. The true cost is far greater than the premium.
Consider these potential costs:
- The average cost to replace the contents of a one-bedroom unit is $20,000.
- The average cost of a one-night hotel stay is $200, which adds up quickly if you’re displaced.
- Legal liability from a guest injury or accidental damage can lead to lawsuits costing hundreds of thousands of dollars.
Is Tenant Insurance Mandatory?
While not legally required in New York, many landlords mandate it in the lease. Even if not required, we strongly advise getting a policy. A 2020 poll from the Insurance Information Institute found that a large percentage of renters are uninsured, leaving them vulnerable. Your landlord’s insurance only covers the building, not your belongings or liability. This is a critical distinction, as we explain for landlords in our Business Insurance for Landlords guide.
Forgoing tenant insurance is a gamble with your financial security. Don’t risk a massive loss for a small monthly saving.
Finding Affordable Options
At Mitchell-Joseph Insurance Agency, we help you find affordable, comprehensive tenant insurance. With access to 24 insurance companies, we compare policies to find coverage that fits your needs and budget. Whether you’re in Honeoye Falls, Pittsford, Naples, or anywhere across New York, we provide personalized guidance. Reach out for a quote and let us help you protect what matters most.
Conclusion: Your Peace of Mind is Priceless
Navigating average rental insurance costs can feel overwhelming, but we hope this guide has made it clearer. We’ve covered what tenant insurance is, why it’s essential, what factors influence its cost, and how to find affordable coverage.
Tenant insurance is a small investment for significant peace of mind. It protects your belongings from perils like theft or fire and shields you from ruinous liability claims, ensuring you don’t face the financial fallout alone.
At Mitchell-Joseph Insurance Agency, we’re your neighbors in Honeoye Falls, Naples, Rochester, and the Finger Lakes region. Our experienced, family-owned business works with 24 insurance companies to find you the right coverage at competitive rates. We tailor your policy to your needs, giving you confidence that your home and future are secure.
Don’t leave your financial well-being to chance. Contact us today to understand your options and get the protection you deserve. We’re here to help.

