

Navigating the Road to Business Vehicle Protection
Auto insurance for business owners is a specialized coverage that protects vehicles used for business purposes against liability claims and physical damage. Unlike personal auto policies, commercial auto insurance offers higher liability limits and coverage custom specifically for business operations.
Quick Guide to Commercial Auto Insurance:
| Key Feature | What You Need to Know |
|---|---|
| Required When | You use vehicles for business beyond commuting, transport goods/people, or title vehicles to your business |
| Basic Coverage | Liability (bodily injury/property damage), physical damage (collision/comprehensive) |
| Average Cost | $147-$270 per month per vehicle (varies by business type and vehicle) |
| Key Difference | Higher liability limits than personal auto policies (recommended: at least $500,000) |
| Add-ons to Consider | Hired/non-owned auto coverage, cargo coverage, gap insurance |
When your personal vehicles cross into business territory—whether you’re delivering products, visiting clients, or transporting equipment—your personal auto policy likely won’t cover accidents or damages that occur during these activities. This creates a dangerous gap in your protection that could leave your business financially vulnerable.
Commercial auto insurance fills this critical gap by offering:
- Higher liability limits to protect business assets
- Coverage for multiple drivers using company vehicles
- Protection for specialized commercial vehicles
- Options for business equipment and cargo
The stakes are higher for business vehicles since they typically face greater exposure to risk and potential liability claims that could threaten your company’s financial stability.
I’m Jeffrey Joseph, owner of Mitchell-Joseph Insurance Agency, and I’ve helped countless business owners across the Finger Lakes Region find the right auto insurance for business owners to protect their vehicles and livelihoods since 1999. My decades of experience have taught me that proper commercial auto coverage isn’t just about compliance—it’s about safeguarding the vehicles that keep your business moving forward.
Understanding Auto Insurance for Business Owners
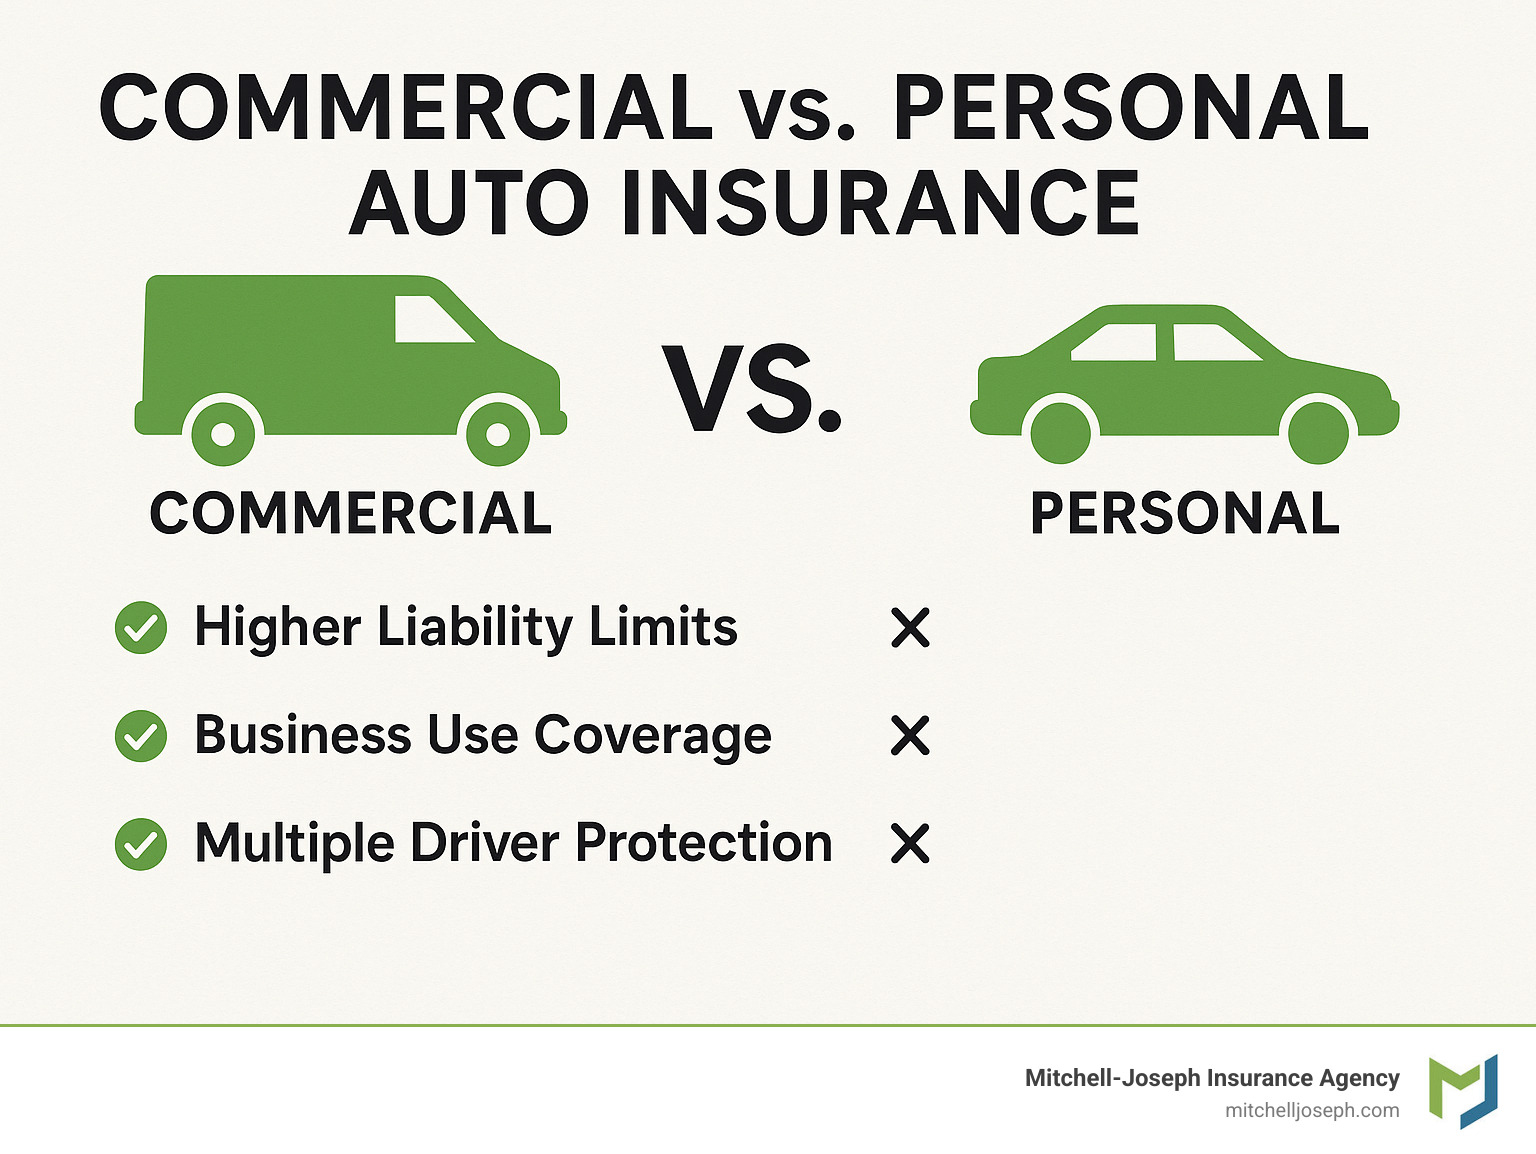
Let’s have a heart-to-heart about your business vehicles. Commercial auto insurance isn’t just a fancy version of your personal policy—it’s a completely different animal designed with your business needs in mind.
At Mitchell-Joseph Insurance Agency, we’ve sat across the table from too many business owners who finded—after an accident—that their personal policy left them high and dry. Let me help you avoid that sinking feeling:
| Feature | Personal Auto Insurance | Commercial Auto Insurance |
|---|---|---|
| Primary Use | Personal transportation, commuting | Business operations, deliveries, client visits |
| Vehicle Types | Personal cars, SUVs, trucks | Business vehicles, specialized equipment, fleets |
| Liability Limits | Typically lower (e.g., 100/300/100) | Higher limits available (500K to $1M+) |
| Named Drivers | Household members | Employees, contractors, specific drivers |
| Business Use | Limited or excluded | Primary coverage focus |
| Policy Ownership | Individual | Business entity |
| Premium Factors | Personal driving history, credit | Business type, vehicle use, employee records |
Here’s a simple truth: if your vehicle is titled to your business, you need commercial auto insurance. This isn’t just good advice—it’s a requirement, since personal policies explicitly exclude vehicles registered to businesses.
Why the Term “auto insurance for business owners” Matters
When you search for “auto insurance for business owners,” you’re looking for more than just a policy—you’re seeking protection that understands your business reality. This isn’t about splitting hairs over terminology; it’s about getting coverage that actually works when you need it.
Your business vehicles face challenges personal vehicles don’t:
– They rack up more miles on the road
– Multiple employees might drive them on any given day
– They often carry valuable tools, equipment, or products
– They represent your business, creating additional liability concerns
– They’re more likely to be involved in costlier claims
Beyond proper protection, having the right coverage keeps you compliant. Without it, you could face:
1. A claim denial right when you need help most
2. Potential violations of state insurance requirements
3. Breach of client contracts that specify coverage minimums
4. Personal financial exposure if your corporate shield gets compromised
As your neighbors here in Rochester, Canandaigua, and throughout the Finger Lakes region, we understand the local business landscape and insurance requirements that affect your day-to-day operations.
Key Differences Every Owner Should Know
When we get into the nitty-gritty, the differences between personal and commercial policies become even clearer:
Bodily Injury Liability offers much higher limits on commercial policies because, frankly, business accidents can turn into bigger headaches. While your personal policy might top out at $300,000, commercial policies routinely offer $1 million or more in protection—because your business deserves that cushion.
Property Damage Liability limits also jump significantly with commercial coverage. This matters when your work truck accidentally backs into expensive equipment or causes a multi-car pileup. Those costs add up fast, especially for contractors, delivery services, or businesses operating in high-value areas.
Hired and Non-Owned Auto Coverage is a commercial policy superpower that doesn’t exist in the personal insurance world. It covers vehicles your business rents or borrows, plus employee-owned vehicles used for business purposes—closing a massive gap that leaves many businesses vulnerable.
Combined Single Limits often replace the split limits of personal policies, giving you more flexibility in how your coverage applies. Instead of separate buckets for different types of damage (like 100/300/100), you might get a $1 million combined single limit that can be applied wherever it’s needed most.
Deductible Structures in commercial policies can be custom to your fleet size and financial situation, allowing you to balance monthly costs against out-of-pocket expenses when claims occur.
For a deeper dive into all your auto coverage options, check out our detailed auto insurance page.
What Does Commercial Auto Insurance Cover (and Not Cover)?
When you’re running a business with vehicles, knowing exactly what your commercial auto policy protects—and what it doesn’t—can make all the difference. Let’s take a drive through the essentials of auto insurance for business owners coverage:
Core Coverages You Can’t Skip
Think of liability coverage as the foundation of your commercial auto policy. It’s what protects your business when things go wrong on the road. This crucial protection pays for bodily injury and property damage you cause to others—covering medical expenses, property repairs, legal defense costs, and potential settlements.
Here at Mitchell-Joseph Insurance Agency, we’ve seen what happens when businesses skimp on liability protection. That’s why we typically recommend liability limits of at least $500,000 for most small businesses. If your company has substantial assets or higher risk exposure, we’ll often suggest $1 million or more in coverage.
Your vehicles themselves need protection too. That’s where physical damage coverage comes in, with two key components working together. Collision coverage has your back when your vehicle tangles with another car or object, regardless of who’s at fault. Meanwhile, comprehensive coverage steps in for those non-collision incidents that seem to happen at the worst times—theft, vandalism, fire damage, or that deer that appeared out of nowhere.
Don’t overlook Medical Payments or Personal Injury Protection (PIP). These coverages handle injuries to you and your passengers no matter who caused the accident. In New York, PIP isn’t just nice to have—it’s required by law, providing essential no-fault coverage for medical bills and lost wages.
One coverage that truly saves the day is Uninsured/Underinsured Motorist protection. I’ve seen too many business owners left holding the bag after accidents with drivers carrying minimal or no insurance. This coverage fills that gap, protecting your business from bearing costs that should rightfully be someone else’s responsibility.
For many of our clients, we recommend pairing commercial auto with a General Liability Policy for comprehensive business protection.
Common Exclusions & How to Fill the Gaps
Now for the surprise many business owners don’t see coming until it’s too late—what your commercial auto policy doesn’t cover.
That expensive equipment riding in your work van? Those products you’re delivering? The tools of your trade? Your auto insurance for business owners policy typically won’t cover these items if they’re damaged or stolen. This is probably the most common misconception I encounter when talking with new clients.
To properly protect these business essentials, you’ll need additional coverage like inland marine insurance for tools and equipment, specific cargo coverage for goods in transit, or business personal property coverage through a Business Owner’s Policy.
Be aware of personal use limitations too. Some commercial policies restrict coverage during personal use of business vehicles. We can help structure your policy to ensure you’re covered appropriately whether you’re heading to a job site or taking the family out for ice cream.
If your business services or repairs customer vehicles, standard commercial auto won’t cover damage to those vehicles while they’re in your care. You’ll need specialized garage liability or garagekeepers coverage instead.
And it probably goes without saying, but no commercial auto policy covers vehicles used in racing or damage caused intentionally. (Though I’m hoping your work trucks aren’t doing quarter-mile runs between job sites!)
For businesses that would face significant downtime and lost income if key vehicles were out of commission, I often recommend exploring Business Interruption Insurance NY. This provides crucial income protection while vehicles are being repaired or replaced after a covered loss.
Having helped hundreds of New York businesses steer these waters since 1999, I’ve found that understanding these coverage nuances isn’t just about compliance—it’s about sleeping better at night knowing your business vehicles are properly protected.
Cost, Requirements & Money-Saving Tips
Let’s talk dollars and sense when it comes to protecting your business vehicles. As a business owner, you’re always watching your bottom line, and commercial auto insurance is an investment that deserves careful consideration.
How Much Will You Pay for auto insurance for business owners?
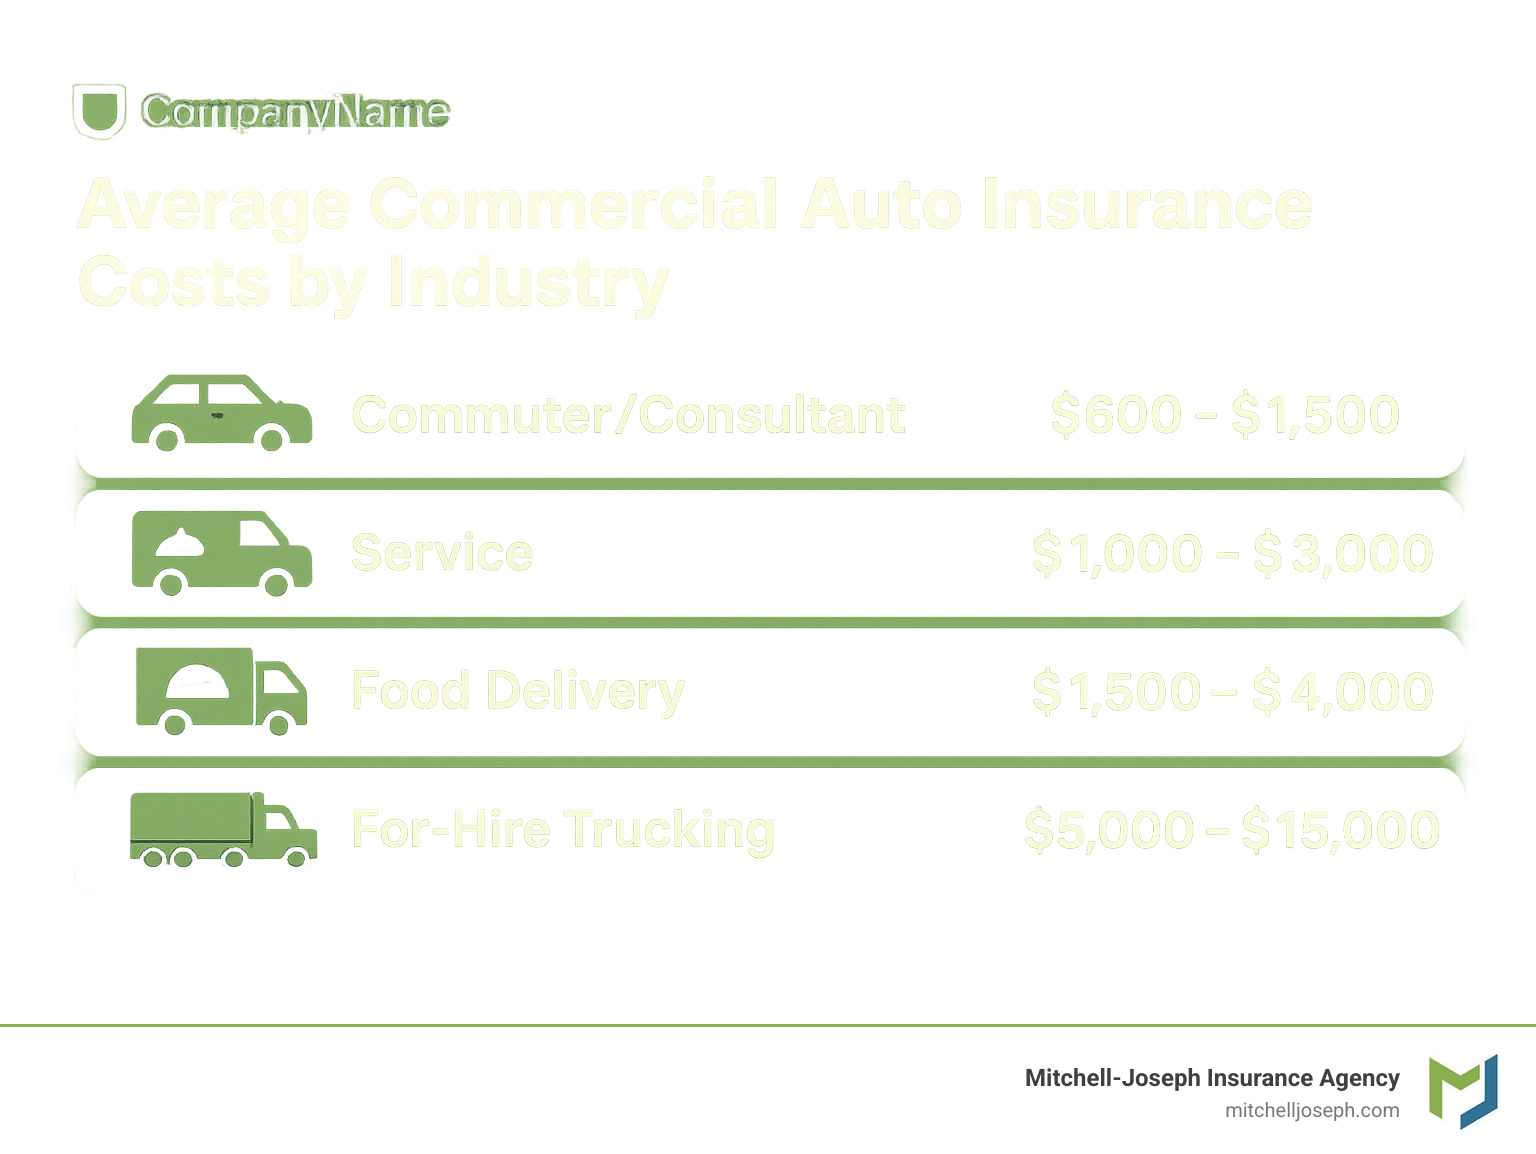
The truth about auto insurance for business owners is that costs can vary dramatically. Most businesses pay between $147 and $270 per month per vehicle, but your actual premium might look quite different based on your specific situation.
Think of your premium like a fingerprint—it’s uniquely yours based on several key factors:
Business Type and Vehicle Use plays a huge role in your costs. A consultant using a sedan for client visits might pay just $600-$1,500 annually, while a food truck might see $1,500-$4,000. Trucking companies face the highest premiums, often $5,000-$15,000 per vehicle annually—reflecting their greater exposure on the road.
Your vehicle’s characteristics matter too. That heavy-duty work truck with specialized equipment will cost more to insure than a standard cargo van. Newer vehicles with advanced safety features might help offset some costs, though their higher value can push premiums up.
Who’s behind the wheel makes a significant difference as well. Your drivers’ history follows your policy like a shadow—every ticket, every fender bender, every year of experience (or lack thereof) affects what you’ll pay.
Here in New York, our clients typically see premiums on the higher end due to our busy roads, particularly in Rochester and surrounding areas. The upside? That higher premium buys peace of mind in a state where accident costs can quickly escalate.
Smart Ways to Cut the Bill
You don’t have to choose between good coverage and affordable rates. I’ve helped hundreds of business owners find that sweet spot where protection meets practicality.
Safety programs pay dividends beyond just preventing accidents. Many carriers offer substantial discounts when you implement formal driver training and written safety policies. One of our landscaping clients saved nearly 15% after implementing a comprehensive safety program that included quarterly driver meetings and telematics monitoring.
Your driver selection process is more important than most business owners realize. Before handing over the keys to your company vehicles, run those Motor Vehicle Records checks! Establishing clear standards for acceptable driving records isn’t just smart risk management—it’s a premium-reducer. Consider creating a points system that flags high-risk behaviors before they become expensive problems.
Vehicle choice affects more than just your fuel budget. When building your fleet, consider vehicles with strong safety ratings and reasonable repair costs. I’ve seen businesses save thousands by standardizing their fleet, making maintenance more efficient and parts more interchangeable. Those anti-theft devices and tracking systems? They often qualify for discounts too.
Policy structure flexibility gives you control over your costs. If your business has healthy cash reserves, consider raising your deductibles—the premium savings can be substantial. Many of my clients review their coverage limits annually, adjusting based on current vehicle values and business needs rather than paying for unnecessary coverage.
Working with an independent agency like Mitchell-Joseph gives you an advantage most businesses miss—we can shop your coverage with multiple carriers to find the best value. Unlike captive agents who represent just one company, we can compare options from our 24 partner companies to find the perfect fit for your business.
Want to understand more about what drives your premium costs? Check out our guide on Factors That Determine Your Auto Insurance Premium. And if you’ve watched your rates climb recently, you’re not alone—our article Noticing Higher Auto Insurance Costs? explains the industry trends affecting businesses across New York.
The cheapest policy isn’t always the best value. The real measure is finding coverage that protects your business completely at a fair price—and that’s exactly where we excel.
Customizing & Managing Your Business Auto Policy
Every business uses vehicles differently. The contractor hauling equipment to job sites has completely different needs than the consultant driving to client meetings. That’s why tailoring your commercial auto policy is so important—it’s not one-size-fits-all protection.
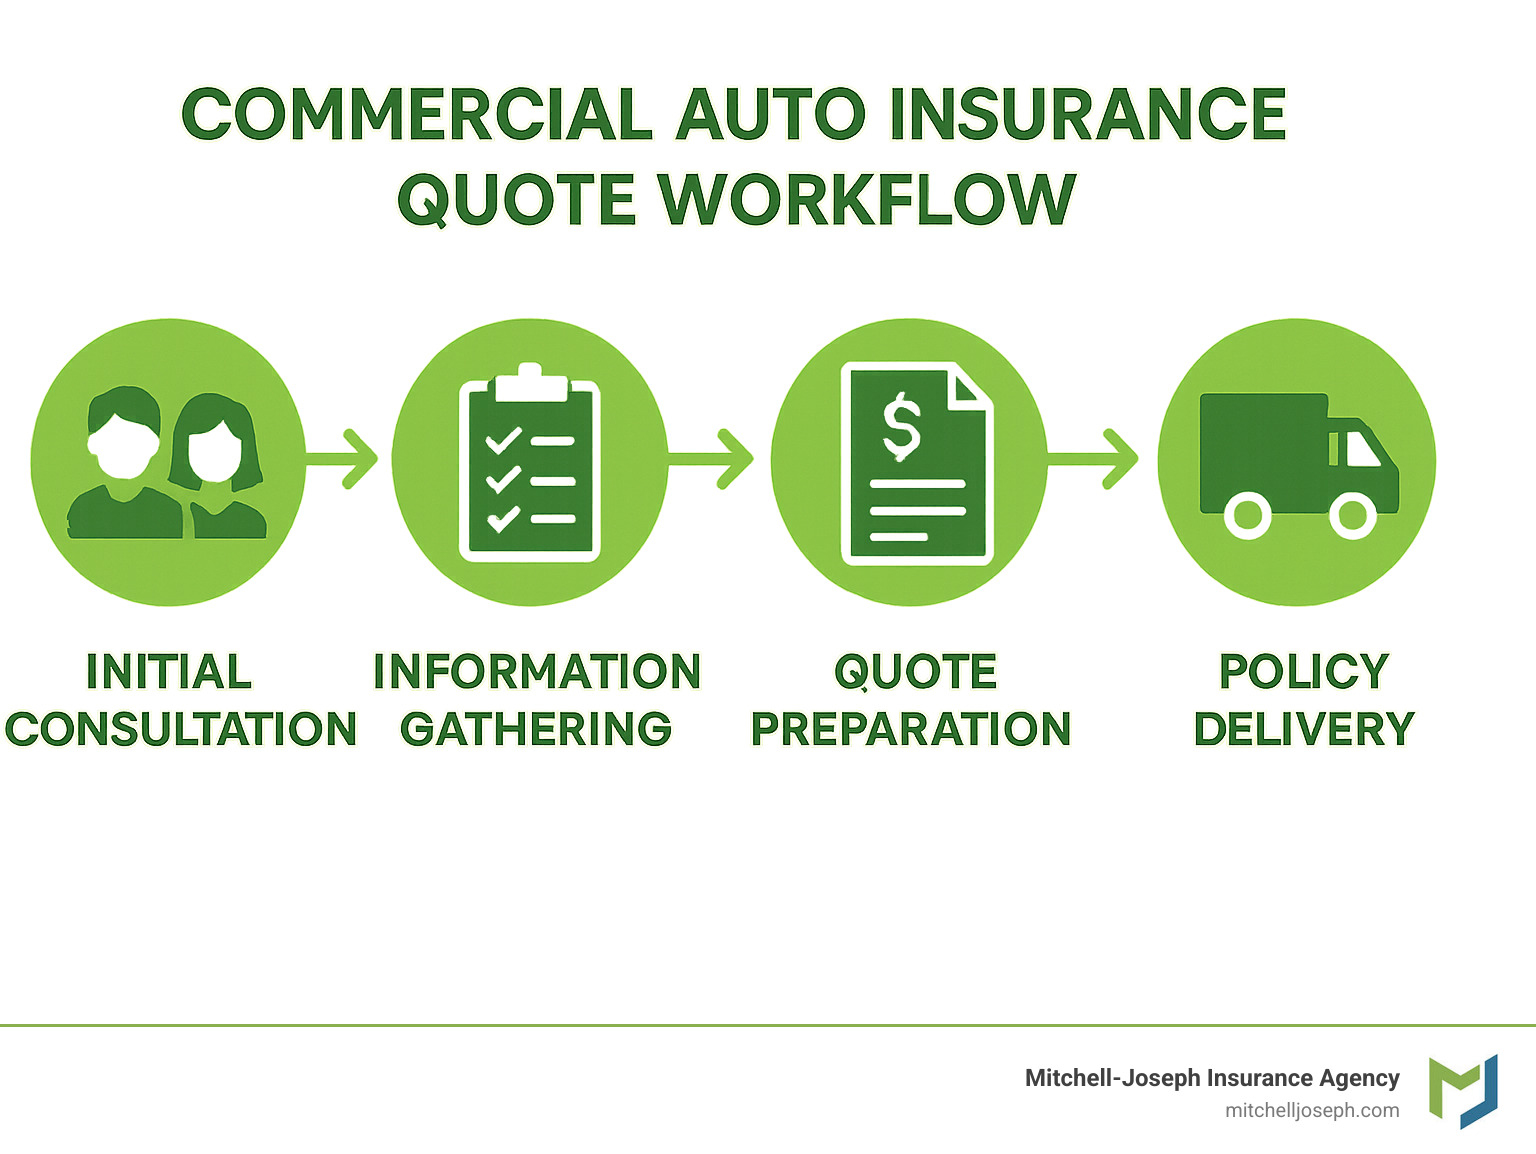
Steps to Get a Quote & File a Claim
Getting the right coverage starts with good information. When you’re ready for a quote, we’ll need to know about your vehicles, drivers, and how you use them for business.
Gathering your information beforehand makes the process smooth and ensures we find the perfect coverage. You’ll want to have your vehicle details (including VINs), driver information, and a general idea of how your vehicles are used in your business operations.
Once you have this information, reaching out is simple. You can call our office, visit one of our locations in Honeoye Falls or Pittsford, or complete our online quote form. The beauty of working with an independent agency like ours is that we’ll shop your coverage with multiple carriers—we work with 24 different insurance companies to find you the best fit.
When it comes to filing a claim, quick action matters. If you’re involved in an accident, safety comes first—make sure everyone is okay and call emergency services if needed. Then document everything: exchange information, take photos, and gather witness contacts if possible.
Report the claim to us promptly, and we’ll help guide you through the process. We’ll be your advocate during the claims process, helping you work with adjusters, arrange repairs, and get back to business as quickly as possible.
For businesses looking for protection beyond just their vehicles, we offer comprehensive Business Insurance Quotes NY covering all aspects of your operation.
Bundling with Other Business Coverages
Think of your insurance program like a well-designed puzzle—each piece should fit perfectly with the others to create complete protection. Bundling your auto insurance for business owners with other coverages not only saves money but also eliminates dangerous coverage gaps.
A Business Owner’s Policy (BOP) combines general liability and property coverage in one convenient package. Adding your commercial auto coverage to this bundle typically earns you a multi-policy discount while simplifying your paperwork and renewal process.
Workers’ compensation naturally complements your auto policy, especially when employees drive for your business. Having both policies with the same agency ensures there’s no confusion about which policy responds when an employee is injured in a vehicle accident.
Modern vehicles are rolling computers, making cyber liability an increasingly important consideration. If customer data is stored or accessed through vehicle systems, bundling cyber coverage provides crucial protection against data breaches.
For businesses facing potentially catastrophic claims, a commercial umbrella policy adds an extra layer of protection beyond your auto policy limits. This can be the difference between weathering a major claim and facing financial disaster.
Different businesses have unique insurance needs. Contractors might benefit from equipment breakdown coverage and inland marine for tools. Professionals might need errors and omissions coverage alongside their auto policy. Property managers can coordinate their auto coverage with specialized Business Insurance for Landlords.
For more information about insurance industry standards and best practices, you can visit the Insurance Information Institute, a trusted resource for insurance education and research.
At Mitchell-Joseph Insurance Agency, we take pride in creating comprehensive, customized insurance packages. With over 200 years of combined experience in our family-owned agency, we understand the unique risks facing businesses in the Finger Lakes region. We’re not just selling policies—we’re building protection plans that grow with your business.
Frequently Asked Questions about Commercial Auto Insurance
Is commercial auto insurance required by law?
Yes, commercial auto insurance is legally required in most circumstances. Just like your personal car, any vehicle on the road needs insurance – including the ones that keep your business running.
Here in New York, all vehicles must have minimum liability coverage, which includes $25,000 for bodily injury per person, $50,000 per accident, $10,000 for property damage, plus Personal Injury Protection and uninsured motorist coverage. But let’s be honest – these minimums are like bringing a water pistol to fight a house fire when it comes to protecting your business.
Most of our clients at Mitchell-Joseph find that carrying at least $500,000 in liability coverage makes more sense for small businesses. Larger operations or those with significant assets often benefit from $1 million or more in protection. Your business vehicles represent your livelihood – they deserve better than minimum coverage.
Some industries face additional requirements too. Interstate trucking companies need to comply with Federal Motor Carrier Safety Administration regulations, businesses hauling hazardous materials have specialized insurance requirements, and passenger transportation services have their own liability thresholds to meet.
Can employees drive their own cars under my policy?
This question comes up all the time, and the answer surprises many business owners: Your standard commercial auto policy typically does not cover employees’ personal vehicles. But don’t worry – there’s a solution called “Hired and Non-Owned Auto Insurance.”
This valuable coverage extension provides liability protection when your employees use their personal vehicles for business errands, when your team rents vehicles for temporary use, or when independent contractors drive their own vehicles on your behalf.
One important note: Hired and Non-Owned coverage only handles the liability side – it doesn’t cover damage to your employee’s actual vehicle. Their personal auto policy still takes care of that.
For the best protection when employees use personal vehicles, we recommend:
1. Verifying employees maintain adequate personal auto insurance
2. Creating clear written policies about business use of personal vehicles
3. Implementing fair mileage reimbursement that accounts for insurance costs
4. Adding coverage for valuable tools or equipment that might be in those personal vehicles
Does the policy cover tools, equipment, or goods?
Here’s a common misconception we clear up almost weekly: Commercial auto insurance generally does not cover tools, equipment, or goods being transported in your vehicles unless they’re permanently attached. That expensive table saw in the back of your truck? Not covered if someone breaks in and steals it.
To properly protect the items that make your business run, you’ll need additional coverage types. For tools and equipment, Inland Marine Insurance provides excellent protection while they’re in transit, at job sites, or in storage. Think of it as a “floater” policy that follows your equipment wherever it goes.
If you’re transporting products or merchandise, Cargo Insurance is what you’ll need. We recommend setting coverage limits that reflect the maximum value you typically transport. And if you’re carrying temperature-sensitive items or high-value goods, we’ll help you find specialized coverage options.
What about that ladder rack or built-in toolbox? Good news – items permanently attached to your vehicle are typically covered under the commercial auto policy. Just be sure to include these modifications when determining your vehicle’s insured value.
At Mitchell-Joseph Insurance Agency, we’ve helped countless businesses throughout Rochester, Canandaigua, and the entire Finger Lakes region develop protection plans that cover not just their vehicles, but everything they need to keep operations running smoothly. We understand that your commercial vehicles are more than just transportation – they’re mobile workspaces that deserve comprehensive protection.
Conclusion
Navigating the complexities of auto insurance for business owners doesn’t have to feel like driving through a maze. With the right guidance and a policy custom to your needs, you can hit the road with confidence knowing your business vehicles are properly protected.
At Mitchell-Joseph Insurance Agency, we bring over 200 years of combined insurance experience to business owners throughout New York’s Finger Lakes region. What makes us different from those faceless online quote generators? We’re your neighbors—real people who understand the unique challenges of operating vehicles in our area, whether you’re navigating Rochester’s busy streets or traveling the rural roads between Canandaigua and Naples.
As an independent agency, we have relationships with 24 different insurance companies. This means we don’t just offer you one option—we shop around to find the perfect coverage at competitive rates specifically designed for your business needs. Whether you run a fleet of delivery vans, a single work truck, or have employees using personal vehicles for business, we’ll find solutions that make sense for your operation.
When it comes to protecting your business vehicles, remember these essential points: commercial policies provide crucial protection that personal auto insurance simply doesn’t offer; your coverage should be custom to your specific operations; higher liability limits are typically necessary to properly shield your business assets; and you may need additional coverage for tools, equipment, and non-owned vehicles.
The road to business success has enough potholes—don’t let inadequate vehicle insurance create another one. Our team takes the time to understand your business operations, explain your options in plain English (not insurance jargon), and develop a comprehensive protection plan that safeguards not just your vehicles, but your entire business future.
Ready to get the wheels turning on better business auto coverage? Visit our website or stop by our office. We’re here to help you steer the road ahead with confidence and peace of mind—and maybe even save you some money along the way. After all, every dollar saved on insurance is another dollar you can invest back into growing your business.
For more information about our auto insurance services in Rochester and surrounding areas, visit our Auto Insurance Rochester services page.

