

Why Smart Farmers Choose Affordable Options for Their Machinery
Affordable farm equipment insurance protects your tractors, combines, and other machinery from theft, weather damage, and breakdowns without breaking your budget. Here’s what you need to know:
Quick Cost Facts:
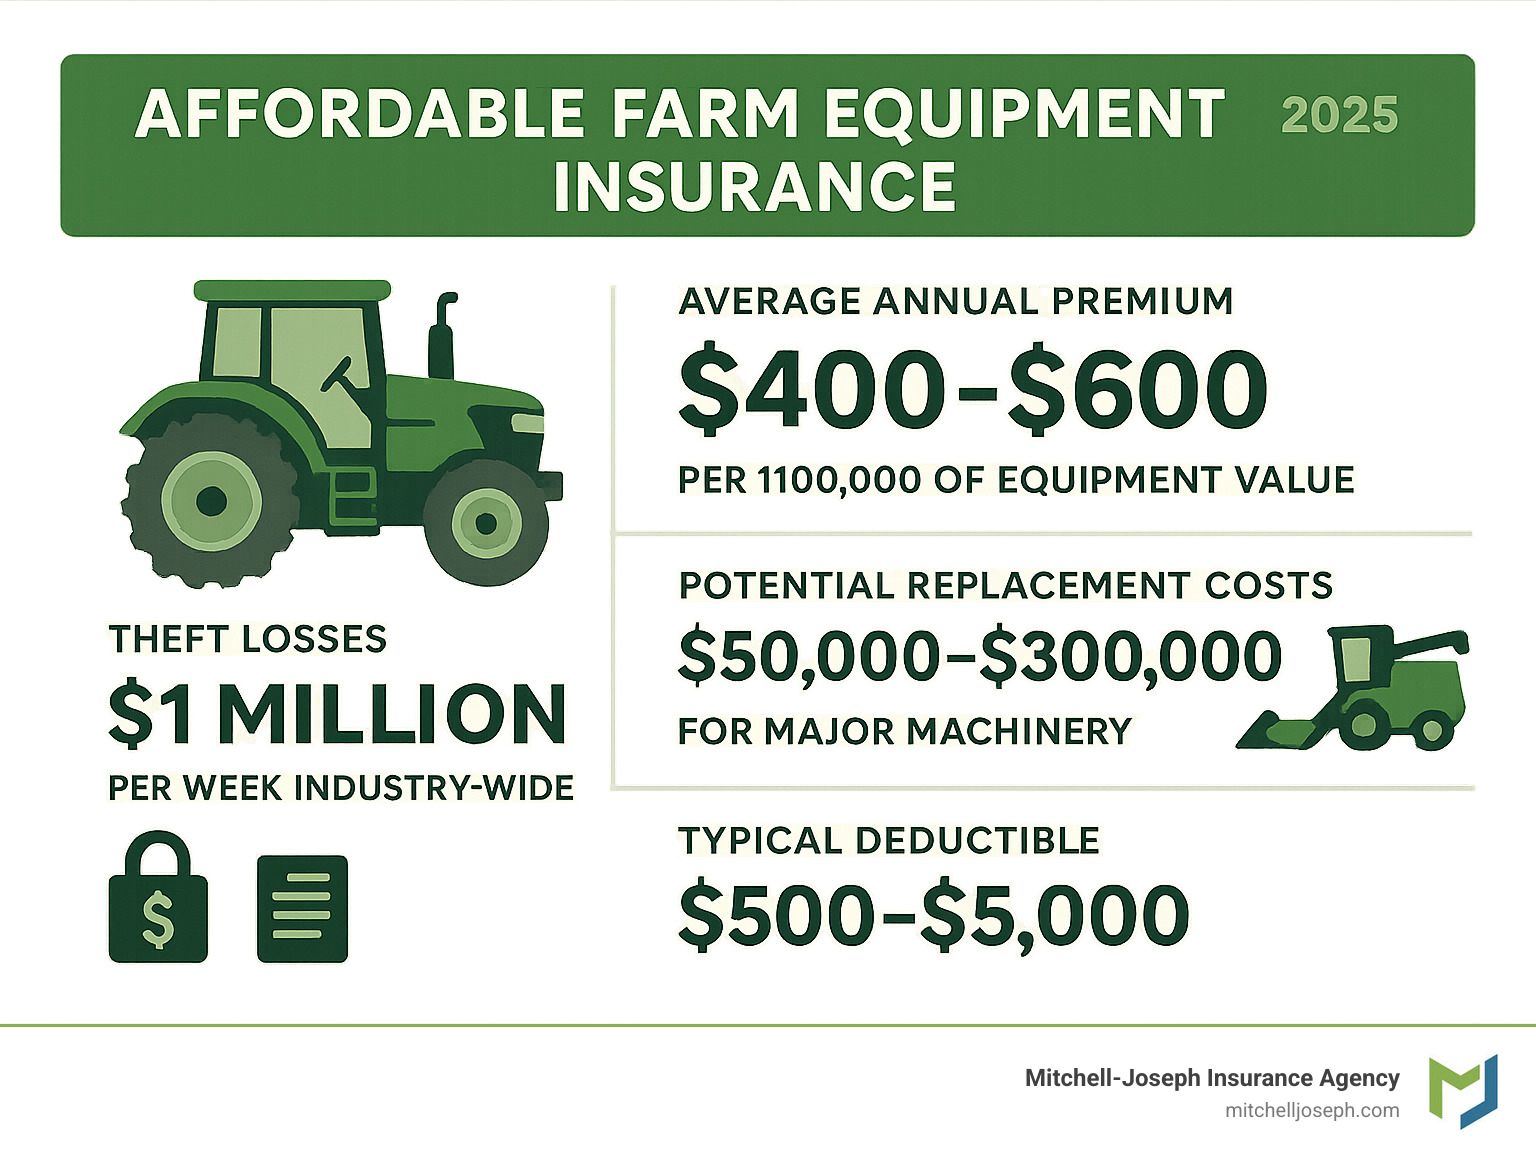
– Typical rates: $4-$6 per $1,000 of equipment value
– Starting coverage: As low as $75/year for basic liability on compact tractors
– Theft losses: Agriculture sees $1 million in equipment theft every week
– New equipment protection: Up to $250,000 covered within first 30 days
Money-Saving Strategies:
– Bundle with existing farm property insurance
– Choose higher deductibles to lower premiums
– Install security systems for discounts
– Schedule only high-value items individually
Your farm equipment is the backbone of your operation. Whether you’re running a small hobby farm or managing hundreds of acres, that combine harvester or tractor represents a major investment – often tens of thousands of dollars that could devastate your finances if lost to fire, theft, or storm damage.
With equipment theft costing farmers about $1 million every week nationwide, and the average economic life of farm machinery ranging from 10-15 years, protecting these assets isn’t just smart – it’s essential for keeping your operation running.
Smart farmers know how to find affordable options that deliver real protection when disaster strikes.
I’m Jeffrey Joseph, and I’ve been helping farmers across the Finger Lakes region secure affordable farm equipment insurance since 1999 through Mitchell-Joseph Insurance Agency.
Simple affordable farm equipment insurance glossary:
– farm insurance policy
– tractor insurance quote
What Is Farm Equipment Insurance & Why It Matters
Affordable farm equipment insurance is specialized coverage that protects the machinery powering your livelihood. This coverage goes beyond standard homeowner’s policies with liability protection for damages you might cause to others and property protection for your own machinery.
Your equipment has an economic life spanning 10-15 years, making it a significant long-term investment. If you’re financing equipment, lenders typically require insurance coverage. Even for owned machinery, downtime costs from uninsured losses can be devastating – especially during critical planting or harvest seasons.
Agriculture faces roughly $1 million in equipment theft losses every week nationwide. Quality farm equipment insurance addresses five key risk categories: Production risks (weather damage, equipment breakdowns), Financial risks (cash flow disruptions), Legal risks (liability protection), Human risks (operator injuries), and Market risks (commodity price changes affecting replacement ability).
Gear That Can Be Covered
Your policy can protect virtually every piece of machinery keeping your farm running. Heavy-duty workhorses like tractors, combines and harvesters, balers and hay equipment, plus cultivators and tillage tools form most policies’ backbone.
Specialized equipment includes seeders and planters, sprayers and applicators, irrigation equipment, and manure spreaders. Modern farms increasingly rely on GPS guidance systems, precision agriculture equipment, and computer-controlled implements that can cost more than older tractors.
Supporting equipment like wagons and trailers, hand tools, shop equipment, and portable generators also deserve protection. Maintain detailed inventories with make, model, serial numbers, and current values for everything you want covered.
Key Perils Policies Tackle
Weather tops the list of equipment destroyers. Hail can turn machinery into scrap metal in minutes. Lightning strikes fry electrical systems. Floods don’t discriminate between new and old equipment. Severe winds can flip heavy machinery.
Theft and vandalism have become major concerns. Equipment theft continues rising as thieves target isolated farms. Copper theft from electrical components has become persistent.
Operational hazards include fires from overheating engines, collision damage during field work, rollover accidents on slopes, and mechanical breakdowns causing secondary damage.
Transport risks include accidents while moving equipment on public roads, damage during loading/unloading, and theft during transport to remote fields.
Coverage Building Blocks & Smart Add-Ons
Building the right affordable farm equipment insurance policy requires choosing between blanket and scheduled coverage. Blanket coverage sets one total limit protecting all equipment up to that amount. Scheduled coverage lists each piece individually with its own coverage amount.
| Coverage Type | Best For | Cost | Flexibility |
|---|---|---|---|
| Blanket | Most farms with varied equipment | Lower premium | High – covers all listed items |
| Scheduled | Farms with few high-value items | Higher premium | Limited to listed items only |
| Combination | Large operations with mixed values | Moderate | Maximum protection |
Most farmers find blanket coverage gives the best value, especially for mixed equipment.
Replacement cost versus actual cash value is your next choice. Replacement cost pays what it actually costs to replace equipment. Actual cash value subtracts depreciation, giving less money but lower premiums. For newer equipment, replacement cost usually makes sense.
The newly-acquired equipment clause automatically covers new purchases up to $250,000 for the first 30 days. Rental reimbursement coverage pays for substitute equipment when yours is in the shop.
Other valuable additions include loss of use coverage for lost income, liability extensions for road travel, pollution liability for environmental damage, agritourism endorsements for visitor liability, and agreed value coverage for vintage equipment collectors.
Optional Boosters Worth Considering
Equipment breakdown coverage protects when things just stop working – no crash, no fire, just mechanical failure. Modern equipment with computers and hydraulics can fail in expensive ways basic coverage won’t touch.
Non-owned and rented machinery coverage protects when you borrow your neighbor’s planter or rent extra capacity for harvest.
Cyber coverage for GPS systems protects precision agriculture systems as hackers increasingly target agricultural technology.
Increased fire department charges covers extra costs for long-distance rural fire department responses.
Work with someone who understands farming to pick add-ons that make sense for your operation.
Making Affordable Farm Equipment Insurance a Reality
The premium math for affordable farm equipment insurance typically runs $4-$6 per $1,000 of equipment value. A $100,000 tractor costs roughly $400-600 per year for coverage.
Your deductible choice is your biggest cost control lever. Choosing a $2,500 deductible instead of $500 can slash premiums by 20-30%. Claims history affects rates for 3-5 years. Location matters – distance from fire departments increases risk and rates.
Operator training and security measures like CESAR tagging earn meaningful discounts. With over 650,000 machines registered, CESAR improves recovery rates and earns security discounts.
Bundling coverage with farm property insurance saves 10-15% on total premiums. At Mitchell-Joseph Insurance Agency, we work with 24 different insurance companies to find the best bundle deals.
Annual reviews save money by adjusting coverage as equipment values change. We recommend yearly policy reviews with formal appraisals every 3-5 years.
Scientific research on equipment valuation
Low-Cost Hacks for Affordable Farm Equipment Insurance
Higher deductible strategy works well for larger operations. Handling a $5,000 deductible instead of $1,000 might save $500-800 annually.
Security system discounts are easier to earn than ever. Installing cameras, alarms, or GPS tracking earns 5-10% discounts.
Telematics programs offer discounts for equipment monitoring systems tracking usage and maintenance.
Multi-policy bundling saves 10-20% compared to separate policies from different companies.
Strategic scheduling covers highest-value equipment individually while using blanket coverage for everything else.
Safe storage rebates reward storing equipment in locked buildings when not in use.
When “Affordable Farm Equipment Insurance” Isn’t Optional
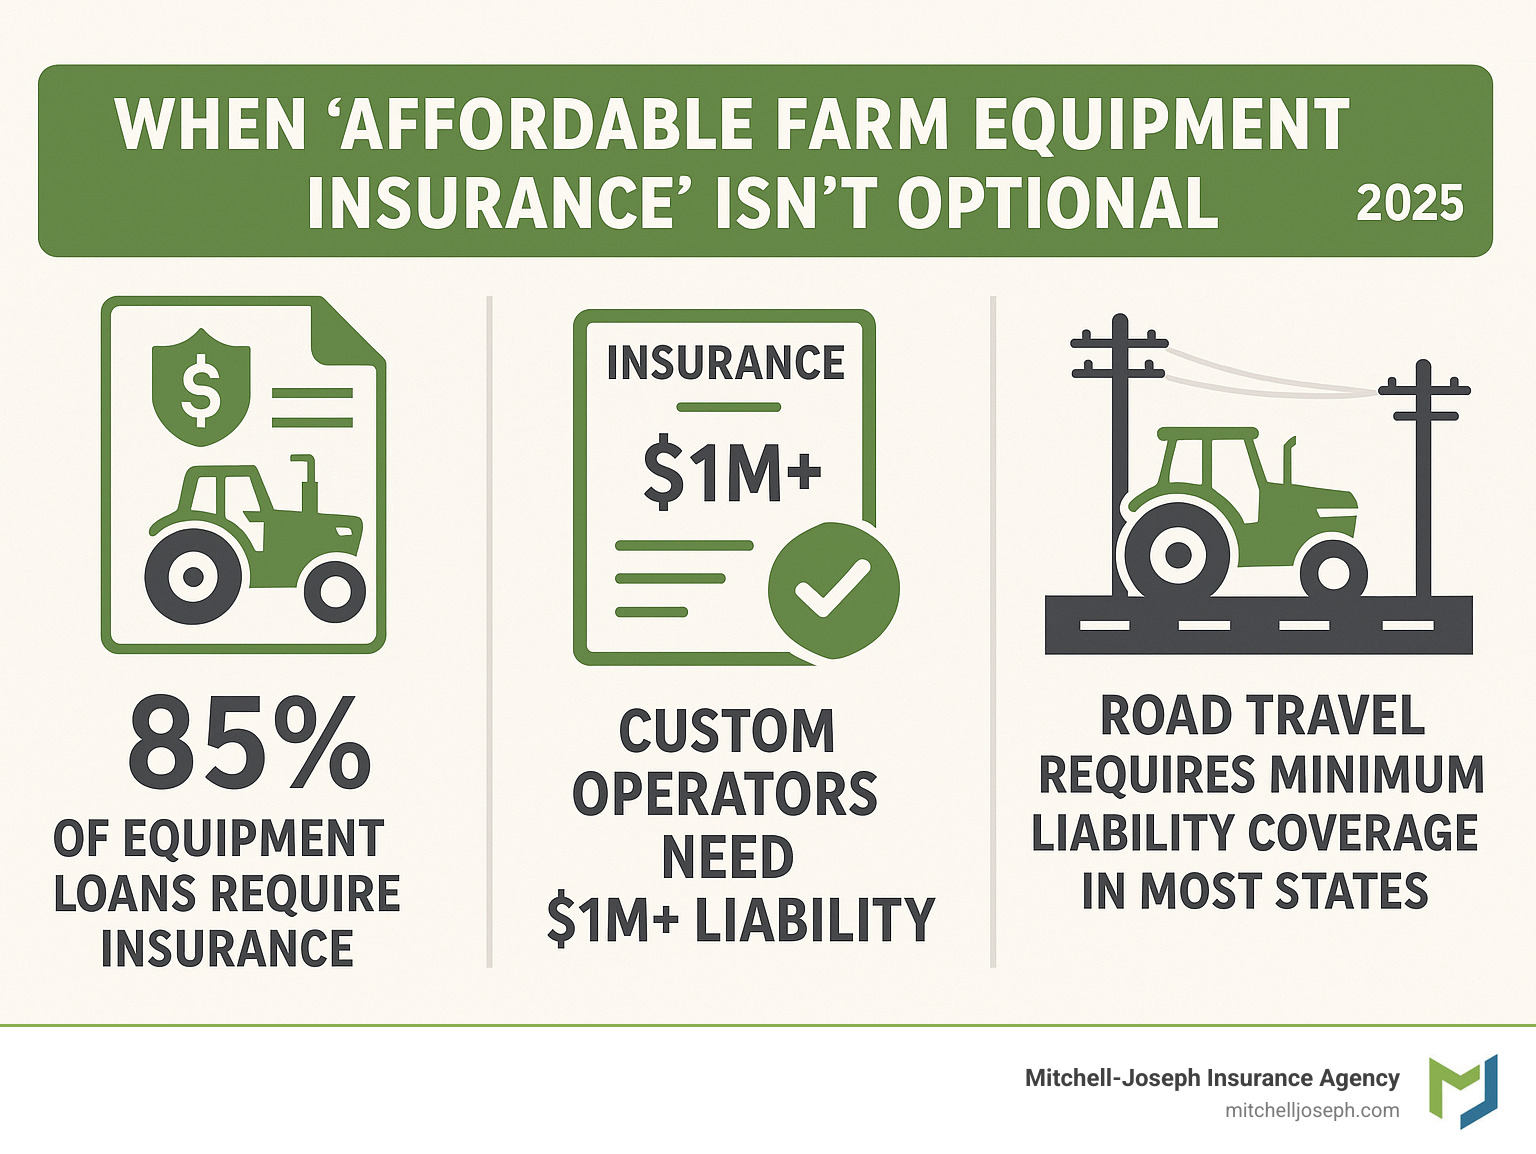
Loan collateral requirements are non-negotiable. Lenders almost always require insurance on financed equipment equal to your loan balance.
Custom-hire contracts often demand proof of equipment insurance before other farmers will sign contracts.
Road travel requirements catch many farmers off guard. Operating farm equipment on public roads often requires liability coverage.
Valuing Gear Correctly & Smooth Claim Filing
Getting equipment values right is essential for affordable farm equipment insurance that delivers when disaster strikes. Too little coverage leaves you short when replacing expensive equipment. Too much coverage wastes money on unnecessary premiums.
Professional appraisals make sense for equipment worth more than $5,000. Certified appraisers understand real-world depreciation and provide documentation insurers accept without argument.
The 3-5 year update rule keeps coverage in sync with reality. Equipment values change due to market conditions, supply shortages, or technology advances.
Smart documentation saves headaches. Keep serial number logs organized. Take annual photos from multiple angles. Maintain maintenance records showing proper equipment care.
When disaster strikes, you have a 24-hour window to report most claims. Call your agent immediately, even on weekends.
Step-by-Step Claim Roadmap for Affordable Farm Equipment Insurance
Safety comes first. Secure the area around damaged equipment and prevent additional damage. Take photos of everything – damage, scene, and surrounding area.
Call your insurance agent within 24 hours. Even at 2 AM on Sunday, leave a message. Missing notification deadlines can jeopardize your entire claim.
Gather maintenance records before the adjuster arrives. These prove proper maintenance and help establish value.
Don’t move damaged equipment unless it creates safety hazards or blocks critical operations. Take extensive photos first if you must move anything.
Activate rental coverage immediately if included in your policy. During planting or harvest, every day without equipment costs money.
Farmers who stay organized from day one get through claims fastest. Complete files with photos, serial numbers, maintenance records, and repair estimates speed settlements.
Review settlement offers carefully before accepting. Ensure coverage includes equipment, additional damage, cleanup costs, and rental expenses.
Picking the Perfect Policy & Provider
Finding the right partner for affordable farm equipment insurance requires choosing someone who understands your needs and will be there when things go wrong.
Look for insurers with A.M. Best ratings of A- or better for financial strength. Agricultural expertise makes all the difference – generic agents often don’t understand farming’s unique risks.
At Mitchell-Joseph Insurance Agency, we’ve worked with Finger Lakes farmers since 1999 because we understand farming isn’t just business – it’s a way of life with unique challenges.
Important service features include flexible deductible options, digital policy management portals, 24/7 claim reporting, and fast claim processing with local adjusters who understand farm equipment.
Watch for red flags like pressure to buy unnecessary coverage or unwillingness to explain policy details clearly. Extremely low prices that seem too good to be true usually are.
Special Cases: Hobby, Commercial & Vintage Operations
Hobby farms generating under $10,000 in revenue often qualify for simplified policies with lower liability limits and can frequently bundle with homeowner’s insurance.
Commercial row-crop operations need higher liability limits and more comprehensive coverage. Consider umbrella policies for catastrophic protection when operating millions of dollars worth of equipment.
Vintage tractor collections require agreed-value coverage rather than actual cash value, since standard depreciation doesn’t account for collectible value.
Livestock operations face additional pollution liability risks from manure handling requiring specialized endorsements.
Agritourism operations need additional liability coverage for visitors attending farm tours, corn mazes, or harvest festivals.
More info about provider selection
Frequently Asked Questions about Farm Equipment Insurance
Is affordable farm equipment insurance required by law?
No state legally requires farm equipment insurance. However, your lender will require coverage if you’ve financed equipment. Coverage typically needs to equal at least the outstanding loan balance.
If you do custom work, you’ll need liability coverage to protect clients. Most farmers won’t hire custom operators without proof of insurance.
Road travel creates another practical requirement. Moving equipment between fields on public roads requires liability coverage.
While law might not require coverage, farming’s financial reality makes affordable farm equipment insurance essential rather than optional.
How is my tractor’s value calculated at renewal?
Insurance companies use depreciation schedules based on several factors reflecting real-world values. Your original purchase price serves as the starting point, then adjusters consider age and maintenance quality.
Current market values for similar equipment play a huge role. If used tractors are selling for higher prices due to supply shortages, valuations should reflect that reality.
Modifications or improvements can increase value. GPS systems or engine overhauls should be factored into equations.
For newer equipment, replacement cost coverage protects against rapid depreciation. For older machinery, agreed value coverage might work better.
We recommend professional appraisals every 3-5 years for equipment worth more than $5,000.
Can I insure rented or borrowed machinery for planting season?
Absolutely. Most affordable farm equipment insurance policies offer several options for non-owned equipment.
Non-owned equipment coverage protects borrowed machinery from neighbors. Hired equipment coverage handles commercially rented machinery. Care, custody, and control coverage protects any equipment temporarily in your possession.
This matters because the equipment owner’s insurance often won’t cover damage while machinery is in your hands. Their policy might exclude coverage when someone else operates their equipment, leaving you potentially liable for full replacement costs.
Conclusion
Your farm equipment works around the clock – shouldn’t your insurance work just as hard? Affordable farm equipment insurance isn’t about cutting corners. It’s about smart protection that fits your budget while covering what matters most.
With $1 million in equipment theft hitting agriculture weekly, and tractors and combines built to last 10-15 years, these machines represent serious long-term investments. Losing equipment during critical seasons can devastate both your harvest and finances.
After helping Finger Lakes farmers for decades, we’ve learned: the right coverage strategy protects your livelihood without emptying your wallet.
Your yearly game plan should include reviewing coverage as values shift, combining security measures with maintenance for premium discounts, considering higher deductibles for cash flow, and bundling equipment coverage with other farm insurance for maximum savings.
At Mitchell-Joseph Insurance Agency, our team brings over 200 years of combined experience. We understand farming because we work with farmers daily. Our relationships with 24 insurance companies mean we shop around to find coverage that makes sense for your operation.
Whether you’re working 50 acres near Honeoye or managing a large spread in Canandaigua, the insurance strategy that works is designed around your specific needs and budget. Your equipment doesn’t take days off during planting and harvest – neither should your protection.
Don’t wait for stolen equipment or storm damage to realize your coverage isn’t adequate. Your machinery has earned its keep season after season. Now ensure it’s protected by insurance that works just as reliably.
Ready to see what real affordable farm equipment insurance looks like for your operation? Let’s talk. Protecting your farm’s future shouldn’t cost a fortune – it should just make sense.
More info about farm insurance coverage
Your equipment keeps your farm running. Make sure your insurance keeps your equipment running too.

